Letter and information from Ian MacLaurin Chairman of Tesco to shareholders of Hilards page 2 of 6 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
                       W H AT             T H E   P R O F E S S I O N A L S     T H I N K

                                      T H E     I N D E P E N D E N T
                                                  28th      April,     1987

                                          Tesco   piles     it      high  for Hillards
TESCO'S        contested  bid  for Hillards now   looks  all    over bar the  shouting. Chairman Ian MacLaurin    yesterday
pitched in his expected increased final offer for the beleaguered regional grocery group which the City felt
would    carry     the day.
                  The deal now on the table is more than 13 per cent, higher than the Tesco's first offer in March. The new
offer puts a 355p valuation on Hillards which represents a premium of nearly 60 per cent, over the pre-bid
share price. Hillards shares yesterday firmed lip to 345p on the market yesterday while Tesco eased 1p to
481p.
                   Tesco's new offer is more generous than most City expectations. It has improved its paper terms to 14 of
its own shares for every 19 of Hillards. It was previously offering 13 for every 20.
                    This puts a price tag of more than £175m on the ordinary shares. Add on the terms for preference shares
(19 Hillards for every 7 Tesco) and the value of the bid tops £200m. The cash deal has been improved to
342.6p.
    The war of words          -the bid  target    yesterday     described the improved  terms as a   "derisory     discount
offer"   -will    now step    up as    both Tesco    and Hillards    canvass  investors. Tesco now speaks for  just   under
10  per     cent, of shares.
           Nearly 35 per cent, of Hillards shares are controlled by the family interests of Peter Hartley who will continue
to put up a fight. So interest will focus on the floating voters who may now have been offered enough financial
incentive   to     accept  the  increased   offer.
                          Tesco yesterday backed the revised offer with a pledge to create more than 10,000 jobs in a £500m
development programme over the next two years.
    At the new offer     price     Hillards would not be     a cheap acquisition -     it will be on a prospective     exit
earnings multiple of around 27 although there should be minimal earnings dilution.
    The arguments for Tesco buying Hillards are well rehearsed; but the bid target                     has not yet put up a
convincing     rebuff     to  the  logic behind    the   takeover.   As a    national   chain Tesco could bring     obvious
economies of scale and buying power. In addition it would allow the bidder                        to expand into Yorkshire-
one      of the    few  regions   where  Tesco    is under-represented   ....
         Hillards  shareholders   have  plenty of time   to  make    up their minds,    the offer does not close until 15th
May, but it is                       hard to see how the company can now persuade those floating voters to come down on its
s i d e .


                                  WOOD MACKENZIE,                                                      Stockbrokers
                                                  28th       April,         1987

                                            HILLARDS holders face substantial downside should the bid lapse. Despite what the heart might say,
the     offer     should be   accepted
Assuming that the £15m forecast retains credibility if Hillards wins the battle to stay Independent, then we
would envisage at least 25 per cent, downside in the Hillards price judged on fundamentals. This looks a
high     price to pay for independence. ...
....                                     In the table below we attempt to assess the fairness of this offer against recent transactions in the
industry.     Using the  current  Tesco     price of  494p,  this       values the     bid    at   £208.4m.
                                                             E x i t    P E R   P r i c e  P e r   P r i c e  P e r   P r i c e  P e r
                                                             H i s t o r i c    S t o r e  s q .   f t .   o f   £    o f    S a l e s
                                                                                    £ m            s a l e s     ( E x         V A T )
                                                                                                       £                             £

H i l l a r d s                   3 1 . 1             5 . 2 1                       2 6 1                                      0 . 7 8
A r g y l l / S a f e w a y           2 5 . 2                        5  . 1 6       3 4 1                                      0 . 7 0
D e e / F i n e               F a r e             2 6 . 3                   1 . 3 6                1 4 8                       0 . 4 9
This    comparison shows that         Hillards'   shareholders          are    being   offered     an extremely            generous exit      PE,
particularly       if one compares it     both    with the   prospective            multiple     of 14-15X,           at   which     Hillards has
traditionally traded, and also the whole sector's rating. In terms of the price being paid for the assets, the
valuation of the selling space looks fair: the Safeway sales area was better positioned, 47 per cent, being
located in the South-East, whilst Fine Fare's sales space. In particular that of Shoppers' Paradise, was
undoubtedly inferior. The very high goodwill element in Tesco's offer is also to be noted. The relatively high
price being offered in relation to Hillards' turnover highlights Hillards' current weak trading position. There
is    little     doubt that Hillards'    shareholders should      feel    fortunate    to  receive     such      a            handsome offer.
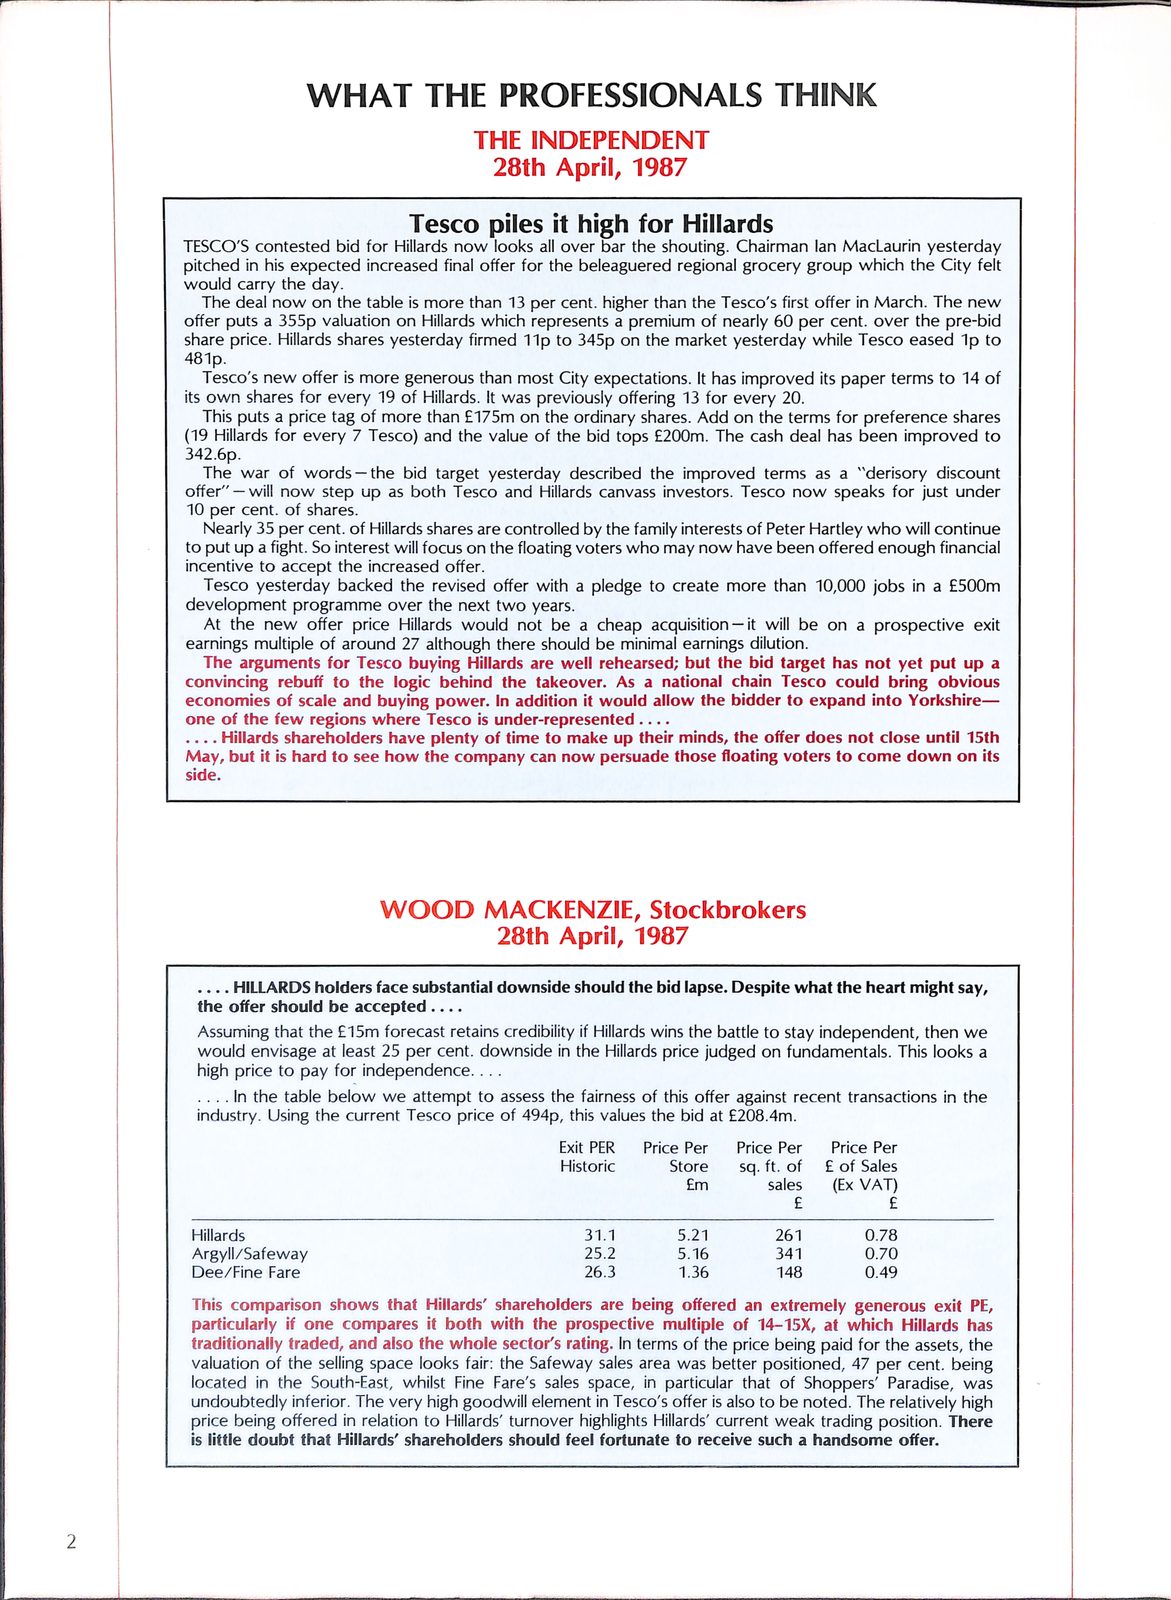
W H AT THEPROFESSIONALSTHINK THEINDEPENDENT 28th April,1987 Tesco piles it high for Hillards TESCO'S contested bid for Hillards now looks all over bar the shouting. Chairman Ian MacLaurin yesterday pitched in his expected increased final offer for the beleaguered regional grocery group which the City felt would carry the day. The deal now on the table is more than 13 per cent, higher than the Tesco's first offer in March. The new offer puts a 355p valuation on Hillards which represents a premium of nearly 60 per cent, over the pre-bid share price. Hillards shares yesterday firmed lip to 345p on the market yesterday while Tesco eased 1p to 481p. Tesco's new offer is more generous than most City expectations. It has improved its paper terms to 14 of its own shares for every 19 of Hillards. It was previously offering 13 for every20. This puts a price tag of more than £175m on the ordinary shares. Add on the terms for preference shares (19Hillards for every 7 Tesco) and the value of the bid tops £200m. The cash deal has been improved to 342.6p. The war of words -the bid target yesterday described the improved terms as a "derisory discount offer" -will now step up as both Tesco and Hillards canvass investors. Tesco now speaks for just under 10 per cent, of shares. Nearly 35 per cent, of Hillards shares are controlled by the family interests of Peter Hartley who will continue to put up a fight. So interest will focus on the floating voters who may now have been offered enough financial incentive to accept the increased offer. Tesco yesterday backed the revised offer with a pledge to create more than10,000 jobs in a £500m development programme over the next two years. At the new offer price Hillards would not be a cheap acquisition - it will be on a prospective exit earnings multiple of around 27 although there should be minimal earnings dilution. The arguments for Tesco buying Hillards are well rehearsed; but the bid target has not yet put up a convincing rebuff to the logic behind the takeover. As a national chain Tesco could bring obvious economies of scale and buying power. In addition it would allow the bidder to expand into Yorkshire- one of the few regions where Tesco is under-represented .... Hillards shareholders have plenty of time to make up their minds, the offer does not close until 15th May, but it is hard to see how the company can now persuade those floating voters to come down on its side . WOOD MACKENZIE, Stockbrokers 28th April,1987 HILLARDS holders face substantial downside should the bid lapse. Despite what the heart might say, the offer should be accepted Assuming that the£15m forecast retains credibility if Hillards wins the battle to stay Independent, then we would envisage at least 25 per cent, downside in the Hillards price judged on fundamentals. This looks a high price to pay for independence.... .... In the table below we attempt to assess the fairness of this offer against recent transactions in the industry. Using the current Tesco price of 494p, this values the bid at £208.4m. ExitPERPricePerPricePerPricePer HistoricStoresq . f t . of£ofSales £msales ( ExVAT ) £ £ Hillards31 . 1 5 . 212610 . 7 8 Argyll / Safeway25 . 2 5 . 163410 . 7 0 Dee / FineFare26 . 3 1 . 361480 . 4 9 This comparison shows that Hillards' shareholders are being offered an extremely generous exit PE, particularly if one compares it both with the prospective multiple of 14-15X, at which Hillards has traditionally traded, and also the whole sector's rating. In terms of the price being paid for the assets, the valuation of the selling space looks fair: the Safeway sales area was better positioned, 47 per cent, being located in the South-East, whilst Fine Fare's sales space. In particular that of Shoppers' Paradise, was undoubtedly inferior. The very high goodwill element in Tesco's offer is also to be noted. The relatively high price being offered in relation to Hillards' turnover highlights Hillards' current weak trading position. There is little doubt that Hillards' shareholders should feel fortunate to receive such a handsome offer.
Read by machine highest quality of the three
WHAT THE PROFESSIONALS THINK

       THE INDEPENDENT
                           28th April,                               1987

                           Tesco piles it high for Hillards
    TESCO’S contested bid for Hillards     now     looks all over  bar the shouting.             Chairman lan MacLaurin yesterday
    pitched in his  expected increased final offer for the       beleaguered regional grocery group           which the City felt
    would   carry  the day.
       The deal   now on  the table is   more   than 13  per cent. higher than the Tesco’s first    offer in  March. The      new
    offer puts  a  355p valuation on     Hillards which  represents a   premium of nearly 60    per    cent.  over    the pre-bid
    share price.   Hillards shares yesterday firmed  11p to 345p     on   the market yesterday while Tesco eased            1p to

       Tesco’s new     offer is more generous   than most City     expectations. It has improved its   paper    terms to    14 of
its own shares for every 19 of Hillards. It was previously offering 13 for every 20.
       This puts  a price tag   of more  than £175m  on  the ordinary shares. Add    on   the   terms       for preference shares
    19 Hillards for    every    7 Tesco) and the value of the bid   tops    £200m. The cash deal has been         improved     to
    342.6p.
       The  war    of  words—the bid     target    yesterday  described    the improved   terms  as    a “derisory       discount
           — will  now      both Tesco and Hillards                           investors. Tesco      speaks      for just    under
    offer’              step    up as                              canvass                      now
    10 per  cent.   of shares.
       Nearly 35   per cent. of Hillards shares are         controlled by the family interests of Peter Hartley who will continue
    to put  up a  fight. So interest will focus on the floating  voters who   may now          have been offered enough financial
    incentive  to accept      the increased offer.
       Tesco yesterday backed        the   revised offer with    a pledge  to create more than       10,000   jobs in a     £500m
    development     programme over         the next two  years.
       At  the   new   offer    price Hillards would not be      a  cheap  acquisition—it will  be     on a   prospective    exit
    earnings multiple of around 27 although there should be minimal earnings dilution.
       The arguments for Tesco buying Hillards           are well  rehearsed; but    the bid    target has  not yet   put    up a
    convincing     rebuff to    the logic behind    the  takeover.  As    a   national   chain  Tesco  could  bring       obvious
    economies of scale and buying     power.     In                  addition it would allow the bidder to expand into Yorkshire—
    one   of the  few regions where Tesco is under-represented          ....
    ....Hillards shareholders have plenty of time        to make    up  their minds, the offer does     not close     until  15th
    May, but it is hard to     see  how the    company can now     persuade those floating voters to     come     down    on  its
    side.


                           WOOD MACKENZIE, Stockbrokers
                           28th April,                                1987

    ....  HILLARDS holders face substantial downside should the bid lapse. Despite what the heart might                    say,
    the offer should be accepted....

    Assuming that the £15m forecast retains credibility if Hillards wins the battle     to stay      independent, then       we
    would envisage        at least 25 per cent.  downside in the Hillards price judged     on     fundamentals. This looks    a
    high price     to  pay    for independence.  . . .
    ....In the      table  below   we attempt to     assess the fairness of this    offer against recent    transactions in the
 industry. Using the current Tesco price of 494p, this values the bid at £208.4m.
                                                             Exit  PER   Price    Per   — Price  Per    Price  Per
                                                              Historic          Store                £    of Sales
                                                                                   £m      sales     (Ex      VAT)
                                                                                                  £              £

    Hillards                                                      31.1           5.21            261          0.78
    Argyll/Safeway                                                25.2           5.16            341          0.70
    Dee/Fine Fare                                                 26.3           1.36            148          0.49

    This  comparison       shows   that Hillards’    shareholders   are  being offered    an     extremely  generous exit   PE,
    particularly    if one   compares    it both   with  the    prospective   multiple    of    14-15X, at  which  Hillards has
    traditionally    traded, and also the whole              rating.  In terms of the price being paid for the     assets,  the
    valuation    of  the selling space  looks fair:  the   Safeway sales area     was    better positioned, 47 per cent.  being
    located     in the   South-East,  whilst Fine    Fare’s sales space,  in particular   that   of   Shoppers’ Paradise,   was
    undoubtedly inferior. The     very   high goodwill element in Tesco’s offer is also     to    be noted. The relatively high
    price being offered in   relation   to   Hillards’ turnover  highlights Hillards’    current   weak trading position. There
is little doubt that Hillards’ shareholders should feel fortunate to receive such a handsome offer.
WHAT THE PROFESSIONALS THINK THE INDEPENDENT 28th April,1987 Tesco piles it high for Hillards TESCO'S contested bid for Hillards now looks all over bar the shouting. Chairman lan MacLaurin yesterday pitched in his expected increased final offer for the beleaguered regional grocery group which the City felt would carry the day. The deal now on the table is more than 13 per cent. higher than the Tesco's first offer in March. The new offer puts a 355p valuation on Hillards which represents a premium of nearly 60 per cent. over the pre-bid share price. Hillards shares yesterday firmed 11p to 345p on the market yesterday while Tesco eased 1p to Tesco's new offer is more generous than most City expectations. It has improved its paper terms to 14 of its own shares for every 19 of Hillards. It was previously offering 13 for every20. This puts a price tag of more than £175m on the ordinary shares. Add on the terms for preference shares 19 Hillards for every 7 Tesco) and the value of the bid tops £200m. The cash deal has been improved to 342.6p. The war of words-the bid target yesterday described the improved terms as a "derisory discount - will now both Tesco and Hillards investors. Tesco speaks for just under offer' step up as canvass now 10 per cent. of shares. Nearly 35 per cent. of Hillards shares are controlled by the family interests of Peter Hartley who will continue to put up a fight. So interest will focus on the floating voters who may now have been offered enough financial incentive to accept the increased offer. Tesco yesterday backed the revised offer with a pledge to create more than10,000 jobs in a £500m development programme over the next two years. At the new offer price Hillards would not be a cheap acquisition-it will be on a prospective exit earnings multiple of around 27 although there should be minimal earnings dilution. The arguments for Tesco buying Hillards are well rehearsed; but the bid target has not yet put up a convincing rebuff to the logic behind the takeover. As a national chain Tesco could bring obvious economies of scale and buying power. In addition it would allow the bidder to expand into Yorkshire- one of the few regions where Tesco is under-represented .... ....Hillards shareholders have plenty of time to make up their minds, the offer does not close until 15th May, but it is hard to see how the company can now persuade those floating voters to come down on its side. WOOD MACKENZIE, Stockbrokers 28th April,1987 ....HILLARDS holders face substantial downside should the bid lapse. Despite what the heart might say, the offer should be accepted.... Assuming that the£15m forecast retains credibility if Hillards wins the battle to stay independent, then we would envisage at least 25 per cent. downside in the Hillards price judged on fundamentals. This looks a high price to pay for independence. . . . ....In the table below we attempt to assess the fairness of this offer against recent transactions in the industry. Using the current Tesco price of 494p, this values the bid at £208.4m. Exit PER Price Per - Price Per Price Per Historic Store £ of Sales £m sales (Ex VAT) £ £ Hillards31.15.21 261 0.78 Argyll/Safeway 25.2 5.16 341 0.70 Dee/Fine Fare26.31.36 148 0.49 This comparison shows that Hillards' shareholders are being offered an extremely generous exit PE, particularly if one compares it both with the prospective multiple of 14-15X, at which Hillards has traditionally traded, and also the whole rating. In terms of the price being paid for the assets, the valuation of the selling space looks fair: the Safeway sales area was better positioned, 47 per cent. being located in the South-East, whilst Fine Fare's sales space, in particular that of Shoppers' Paradise, was undoubtedly inferior. The very high goodwill element in Tesco's offer is also to be noted. The relatively high price being offered in relation to Hillards' turnover highlights Hillards' current weak trading position. There is little doubt that Hillards' shareholders should feel fortunate to receive such a handsome offer.
Read by machine, contrast corrected
WHAT THE PROFESSIONALS THINK

       THE INDEPENDENT
                           28th April,                               1987

                           Tesco piles it high for Hillards
    TESCO’S contested bid for Hillards     now     looks all over  bar the shouting.             Chairman lan MacLaurin yesterday
    pitched in his  expected increased final offer for the       beleaguered regional grocery group           which the City felt
    would   carry  the day.
       The deal   now on  the table is   more   than 13  per cent. higher than the Tesco’s first    offer in  March. The      new
    offer puts  a  355p valuation on     Hillards which  represents a   premium of nearly 60    per    cent.  over    the pre-bid
    share price.   Hillards shares yesterday firmed  11p to 345p     on   the market yesterday while Tesco eased            1p to
    48 1p.
       Tesco’s new     offer is more generous   than most City     expectations. It has improved its   paper    terms to    14 of
its own shares for every 19 of Hillards. It was previously offering 13 for every 20.
       This puts  a price tag   of more  than £175m  on  the ordinary shares. Add    on   the   terms       for preference shares
    19 Hillards for    every    7 Tesco) and the value of the bid   tops    £200m. The cash deal has been         improved     to
    342.6p.
       The  war    of  words—the bid     target    yesterday  described    the improved   terms  as    a “derisory       discount
           — will  now      both Tesco and Hillards                           investors. Tesco      speaks      for just    under
    offer’              step    up as                              canvass                      now
    10 per  cent.   of shares.
       Nearly 35   per cent. of Hillards shares are         controlled by the family interests of Peter Hartley who will continue
    to put  up a  fight. So interest will focus on the floating  voters who   may now          have been offered enough financial
    incentive  to accept      the increased offer.
       Tesco yesterday backed        the   revised offer with    a pledge  to create more than       10,000   jobs in a     £500m
    development     programme over         the next two  years.
       At  the   new   offer    price Hillards would not be      a  cheap  acquisition—it will  be     on a   prospective    exit
    earnings multiple of around 27 although there should be minimal earnings dilution.
       The arguments for Tesco buying Hillards           are well  rehearsed; but    the bid    target has  not yet   put    up a
    convincing     rebuff to    the logic behind    the  takeover.  As    a   national   chain  Tesco  could  bring       obvious
    economies of scale and buying     power.     In                  addition it would allow the bidder to expand into Yorkshire—
    one   of the  few regions where Tesco is under-represented          ....
    ....Hillards shareholders have plenty of time        to make    up  their minds, the offer does     not close     until  15th
    May, but it is hard to     see  how the    company can now     persuade those floating voters to     come     down    on  its
    side.


                           WOOD MACKENZIE, Stockbrokers
                           28th April,                                1987

    ....  HILLARDS holders face substantial downside should the bid lapse. Despite what the heart might                    say,
    the offer should be accepted....

    Assuming that the £15m forecast retains credibility if Hillards wins the battle     to stay      independent, then       we
    would envisage        at least 25 per cent.  downside in the Hillards price judged   on      fundamentals. This looks     a
    high price     to  pay    for independence.  . . .
    ....In the      table  below   we attempt to     assess the fairness of this offer   against recent     transactions in the
 industry. Using the current Tesco price of 494p, this values the bid at £208.4m.

                                                             Exit  PER   Price    Per    Price   Per  Price    Per
                                                              Historic          Store                £    of Sales
                                                                                   £m    sales       (Ex      VAT)
                                                                                                 £               £

    Hillards                                                      31.1           5.21            261          0.78
    Argyll/Safeway                                                25.2           5.16            341          0.70
    Dee/Fine Fare                                                 26.3           1.36            148          0.49

    This  comparison       shows   that Hillards’    shareholders   are  being offered   an extremely     generous exit     PE,
    particularly    if one   compares    it both   with  the    prospective   multiple   of 14-15X,   at    which  Hillards has
    traditionally    traded, and also the whole              rating.  In terms of the price being paid for the     assets,  the
    valuation    of  the selling space  looks fair:  the   Safeway sales area     was    better positioned, 47 per cent.  being
    located     in the   South-East,  whilst Fine    Fare’s sales space,  in particular  that    of   Shoppers’ Paradise,   was
    undoubtedly inferior. The     very   high goodwill element in Tesco’s offer is also     to    be noted. The relatively high
    price being offered in   relation   to   Hillards’ turnover  highlights Hillards’    current   weak trading position. There
is little doubt that Hillards’ shareholders should feel fortunate to receive such a handsome offer.
WHAT THE PROFESSIONALS THINK THE INDEPENDENT 28th April,1987 Tesco piles it high for Hillards TESCO'S contested bid for Hillards now looks all over bar the shouting. Chairman lan MacLaurin yesterday pitched in his expected increased final offer for the beleaguered regional grocery group which the City felt would carry the day. The deal now on the table is more than 13 per cent. higher than the Tesco's first offer in March. The new offer puts a 355p valuation on Hillards which represents a premium of nearly 60 per cent. over the pre-bid share price. Hillards shares yesterday firmed 11p to 345p on the market yesterday while Tesco eased 1p to 48 1p. Tesco's new offer is more generous than most City expectations. It has improved its paper terms to 14 of its own shares for every 19 of Hillards. It was previously offering 13 for every20. This puts a price tag of more than £175m on the ordinary shares. Add on the terms for preference shares 19 Hillards for every 7 Tesco) and the value of the bid tops £200m. The cash deal has been improved to 342.6p. The war of words-the bid target yesterday described the improved terms as a "derisory discount - will now both Tesco and Hillards investors. Tesco speaks for just under offer' step up as canvass now 10 per cent. of shares. Nearly 35 per cent. of Hillards shares are controlled by the family interests of Peter Hartley who will continue to put up a fight. So interest will focus on the floating voters who may now have been offered enough financial incentive to accept the increased offer. Tesco yesterday backed the revised offer with a pledge to create more than10,000 jobs in a £500m development programme over the next two years. At the new offer price Hillards would not be a cheap acquisition-it will be on a prospective exit earnings multiple of around 27 although there should be minimal earnings dilution. The arguments for Tesco buying Hillards are well rehearsed; but the bid target has not yet put up a convincing rebuff to the logic behind the takeover. As a national chain Tesco could bring obvious economies of scale and buying power. In addition it would allow the bidder to expand into Yorkshire- one of the few regions where Tesco is under-represented .... ....Hillards shareholders have plenty of time to make up their minds, the offer does not close until 15th May, but it is hard to see how the company can now persuade those floating voters to come down on its side. WOOD MACKENZIE, Stockbrokers 28th April,1987 ....HILLARDS holders face substantial downside should the bid lapse. Despite what the heart might say, the offer should be accepted.... Assuming that the£15m forecast retains credibility if Hillards wins the battle to stay independent, then we would envisage at least 25 per cent. downside in the Hillards price judged on fundamentals. This looks a high price to pay for independence. . . . ....In the table below we attempt to assess the fairness of this offer against recent transactions in the industry. Using the current Tesco price of 494p, this values the bid at £208.4m. Exit PER Price Per Price Per Price Per Historic Store £ of Sales £m sales (Ex VAT) £ £ Hillards31.15.21 261 0.78 Argyll/Safeway 25.2 5.16 341 0.70 Dee/Fine Fare26.31.36 148 0.49 This comparison shows that Hillards' shareholders are being offered an extremely generous exit PE, particularly if one compares it both with the prospective multiple of 14-15X, at which Hillards has traditionally traded, and also the whole rating. In terms of the price being paid for the assets, the valuation of the selling space looks fair: the Safeway sales area was better positioned, 47 per cent. being located in the South-East, whilst Fine Fare's sales space, in particular that of Shoppers' Paradise, was undoubtedly inferior. The very high goodwill element in Tesco's offer is also to be noted. The relatively high price being offered in relation to Hillards' turnover highlights Hillards' current weak trading position. There is little doubt that Hillards' shareholders should feel fortunate to receive such a handsome offer.