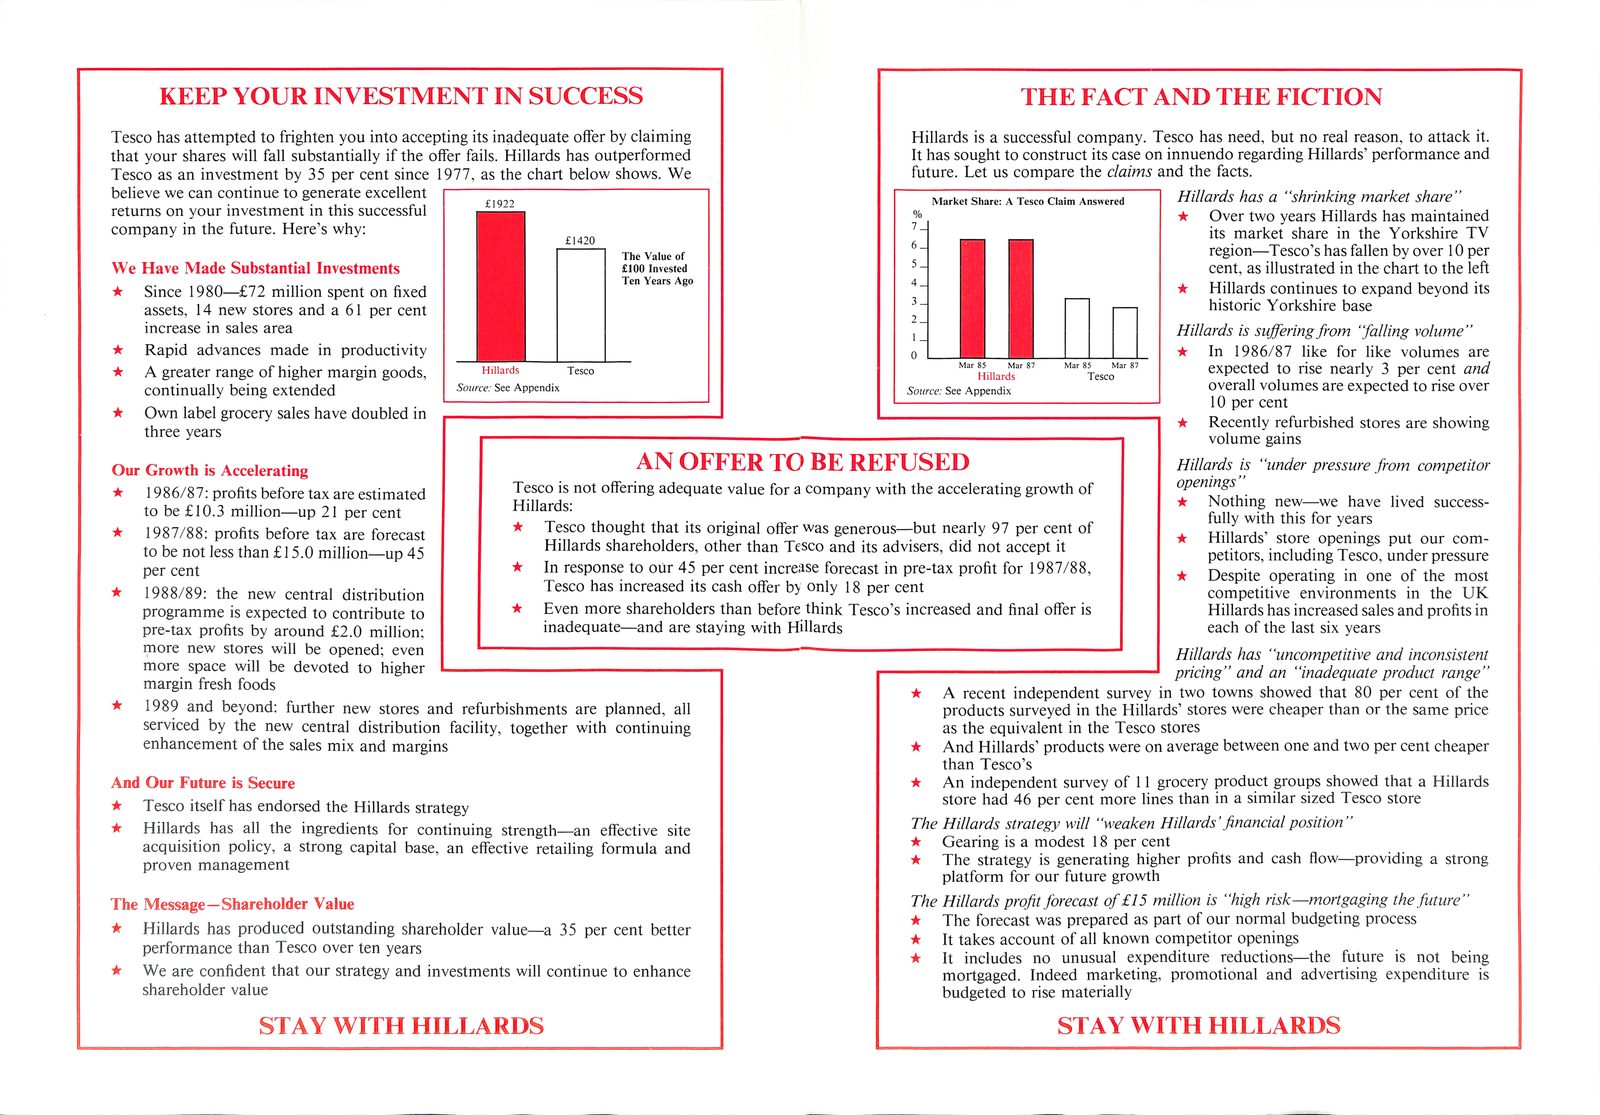
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
K E E P Y O U R I N V E S T M E N T I N S U C C E S S T H E F A C T A N D T H E F I C T I O N
Tesco has attempted to frighten you into accepting its inadequate offer by claiming Hillards is a successful company. Tesco has need, but no real reason, to attack it.
that your shares will fall substantially if the offer fails. Hillards has outperformed It has sought to construct its case on innuendo regarding Hillards' performance and
Tesco as an investment by 35 per cent since 1977, as the chart below shows. We future. Let us compare the claims and the facts.
believe we can continue to generate excellent M a r k e t S h a r e ; A Te s c o C l a i m A n s w e r e d Hillards has a "shrinking market share"
returns on your investment in this successful £1 9 2 2 ★ Over two years Hillards has maintained
company in the future. Here's why: £1 4 2 0 i t s m a r k e t s h a r e i n t h e Yo r k s h i r e T V
Th e Va l u e o f region-Tesco's has fallen by over 10 per
W e H a v e M a d e S u b s t a n t i a l I n v e s t m e n t s £ i o o i n v e s t e d cent, as illustrated in the chart to the left
★ Since 1980-£72 million spent on fixed Ten Years Ago ★ Hillards continues to expand beyond its
assets, 14 new stores and a 61 per cent h i s t o r i c Yo r k s h i r e b a s e
i n c r e a s e i n s a l e s a r e a Hillards is suffering from "falling volume"
★ Rapid advances made in productivity ★ I n 1 9 8 6 / 8 7 l i k e f o r l i k e v o l u m e s a r e
★ A greater range of higher margin goods, H M a r 8 5 M a r 8 7 M a r 8 5 M a r 8 7 expected to rise nearly 3 per cent and
i l l a r d s T e s c o H i l l a r d s Te s c o
continually being extended Source: See Appendix Source: See Appendix overall volumes are expected to rise over
★ Own label grocery sales have doubled in 10 per cent
★ Recently refurbished stores are showing
three years volume gains
Our Growth is Accelerating A N O F E E R T O B E R E F U S E D Hillards is "under pressure from competitor
★ f 986/87: profits before tax are estimated Tesco is not offering adequate value for a company with the accelerating growth of openings"
H i l l a r d s: ★ Nothing new-we have lived success
to be £10.3 million-up 21 per cent fully with this for years
★ 1987/88: profits before tax are forecast ★ Tesco thought that its original offer was generous-but nearly 97 per cent of ★ Hillards' store openings put our com
to be not less than £15.0 million-up 45 Hillards shareholders, other than Tesco and its advisers, did not accept it
★ In response to our 45 per cent increase forecast in pre-tax profit for 1987/88, petitors, including Tesco, under pressure
per cent ★ Despite operating in one of the most
★ 1988/89: t he new ce nt ra l d ist r ib ut io n ★ Tesco has increased its cash offer by only 18 per cent competitive environments in the UK
programme is expected to contribute to Even more shareholders than before think Tesco's increased and final offer is Hillards has increased sales and profits in
pre-tax profits by around £2.0 million; inadequate-and are staying with Hillards each of the last six years
more new stores will be opened; even Hillards has "uncompetitive and inconsistent
more space will be devoted to higher pricing" and an "inadequate product range"
margin fresh foods ★ A recent independent survey in two towns showed that 80 per cent of the
★ 1989 and beyond: further new stores and refurbishments are planned, all products surveyed in the Hillards' stores were cheaper than or the same price
serviced by the new central distribution facility, together with continuing as the equivalent in the Tesco stores
enhancement of the sales mix and margins ★ And Hillards' products were on average between one and two per cent cheaper
t h a n Te s c o ' s
And Ou r Futu re is Secu re ★ An independent survey of 11 grocery product groups showed that a Hillards
★ Tesco itself has endorsed the Hillards strategy store had 46 per cent more lines than in a similar sized Tesco store
★ Hillards has all the ingredients for continuing strength-an effective site The Hillards strategy will "weaken Hillards' financial position"
acquisition policy, a strong capital base, an effective retailing formula and ★ Gearing is a modest 18 per cent
proven management ★ The strategy is generating higher profits and cash flow-providing a strong
platform for our future growth
The Message-Shareholder Value The Hillards profit forecast of £15 million is "high risk-mortgaging the future"
★ Hillards has produced outstanding shareholder value-a 35 per cent better ★ The forecast was prepared as part of our normal budgeting process
★ It takes account of all known competitor openings
performance than Tesco over ten years ★ It includes no unusual expenditure reductions-the future is not being
★ We are confident that our strategy and investments will continue to enhance mortgaged. Indeed marketing, promotional and advertising expenditure is
s h a r e h o l d e r v a l u e budgeted to rise materially
S T A Y W I T H H I L L A R D S S T A Y W I T H H I L L A R D SKEEPYOURINVESTMENTINSUCCESSTHEFACTANDTHEFICTION Tesco has attempted to frighten you into accepting its inadequate offer by claiming Hillards is a successful company. Tesco has need, but no real reason, to attack it. that your shares will fall substantially if the offer fails. Hillards has outperformed It has sought to construct its case on innuendo regarding Hillards' performance and Tesco as an investment by 35 per cent since1977, as the chart below shows. We future. Let us compare the claims and the facts. believe we can continue to generate excellent MarketShare ; A Te scoClaimAnswered Hillards has a "shrinking market share" returns on your investment in this successful£1922 ★ Over two years Hillards has maintained company in the future. Here's why: £1 420itsmarketshareinthe Yo rkshireTV Th e Va lueof region-Tesco's has fallen by over 10 per WeHaveMadeSubstantialInvestments£iooinvested cent, as illustrated in the chart to the left ★Since1980-£72 million spent on fixed Ten Years Ago ★ Hillards continues to expand beyond its assets, 14 new stores and a 61 per cent historic Yo rkshirebase increaseinsalesarea Hillards is suffering from "falling volume" ★ Rapid advances made in productivity ★ In1986 / 87likeforlikevolumesare ★ A greater range of higher margin goods, HMar85Mar87Mar85Mar87 expected to rise nearly 3 per cent and illardsTescoHillards Tesco continually being extended Source: See Appendix Source: See Appendix overall volumes are expected to rise over ★ Own label grocery sales have doubled in 10 per cent ★ Recently refurbished stores are showing three years volume gains Our Growth is Accelerating ANOFEERTOBEREFUSED Hillards is "under pressure from competitor ★ f 986/87:profits before tax are estimated Tesco is not offering adequate value for a company with the accelerating growth of openings" Hillard s: ★ Nothing new-we have lived success to be £10.3 million-up 21 per cent fully with this for years ★1987/88:profits before tax are forecast ★ Tesco thought that its original offer was generous-but nearly 97 per cent of ★ Hillards' store openings put our com to be not less than£15.0 million-up 45 Hillards shareholders, other than Tesco and its advisers, did not accept it ★ In response to our 45 per cent increase forecast in pre-tax profit for 1987/88, petitors, including Tesco, under pressure per cent ★ Despite operating in one of the most ★ 1988/89: t he new ce nt ra l d ist r ib ut io n ★ Tesco has increased its cash offer by only 18 per cent competitive environments in the UK programme is expected to contribute to Even more shareholders than before think Tesco's increased and final offer is Hillards has increased sales and profits in pre-tax profits by around£2.0 million; inadequate-and are staying with Hillards each of the last six years more new stores will be opened; even Hillards has "uncompetitive and inconsistent more space will be devoted to higher pricing" and an "inadequate product range" margin fresh foods ★ A recent independent survey in two towns showed that 80 per cent of the ★ 1989 and beyond: further new stores and refurbishments are planned, all products surveyed in the Hillards' stores were cheaper than or the same price serviced by the new central distribution facility, together with continuing as the equivalent in the Tesco stores enhancement of the sales mix and margins ★ And Hillards' products were on average between one and two per cent cheaper than Tesco' s And Ou r Future is Secure★ An independent survey of 11 grocery product groups showed that a Hillards ★ Tesco itself has endorsed the Hillards strategy store had 46 per cent more lines than in a similar sized Tesco store ★ Hillards has all the ingredients for continuing strength-an effective site The Hillards strategy will "weaken Hillards' financial position" acquisition policy, a strong capital base, an effective retailing formula and ★ Gearing is a modest 18 per cent proven management ★ The strategy is generating higher profits and cash flow-providing a strong platform for our future growth The Message-Shareholder Value The Hillards profit forecast of £15million is "high risk-mortgaging the future" ★ Hillards has produced outstanding shareholder value-a 35 per cent better ★ The forecast was prepared as part of our normal budgeting process ★ It takes account of all known competitor openings performance than Tesco over ten years ★ It includes no unusual expenditure reductions-the future is not being ★ We are confident that our strategy and investments will continue to enhance mortgaged. Indeed marketing, promotional and advertising expenditure is shareholdervalue budgeted to rise materially STAYWITHHILLARDSSTAYWITHHILLARDS
Read by machine
KEEP YOUR INVESTMENT IN SUCCESS THE FACT AND THE FICTION
Tesco has attempted to frighten you into accepting its inadequate offer by claiming Hillards is a successful company. Tesco has need, but no real reason, to attack it.
that your shares will fall substantially if the offer fails. Hillards has outperformed It has sought to construct its case on innuendo regarding Hillards’ performance and
Tesco as an investment by 35 per cent since 1977, as the chart below shows. We future. Let us compare the claims and the facts.
believe we can continue to generate excellent £1922 Market Share: A Tesco Claim Answered Hillards has a “shrinking market
returns on your investment in this successful % * Over two years Hillards has maintained
company in the future. Here’s why: £1420 6_| its market share in the Yorkshire TV
The Value of region—Tesco’s has fallen by over 10 per
We Have Made Substantial Investments £100 Invested 5_| cent, as illustrated in the chart to the left
* Since 1980—£72 million spent on fixed Ten Years Ago 3_] * Hillards continues to expand beyond its
assets, 14 new stores and a 61 per cent 2 historic Yorkshire base
increase in sales area 1 Hillards is suffering from volume”’
+ Rapid advances made in productivity 0 * In 1986/87 like for like volumes are
A greater range of higher margin goods, Hillards Tesco expected to rise nearly 3 per cent and
continually being extended Source: See Appendix Source: See Appendix overall volumes are expected to rise over
Own label grocery sales have doubled in 10 per cent
* Recently refurbished stores are showing
three years volume gains
Our Growth is Accelerating AN OFFER TO BE REFUSED Hillards is “under pressure from competitor
* 1986/87: profits before tax are estimated Tesco is not offering adequate value for a Company with the accelerating growth of *x Nothing new—we have lived
to be £10.3 million—up 21 per cent Hillards: success-
* 1987/88: profits before tax are forecast * Tesco thought that its original offer was generous—but nearly 97 per cent of fully with this for years
to be less than £15.0 Hillards shareholders, other than Tesco and its advisers, did not accept it * store openings put our com-
not million—up 45 petitors, including Tesco, under pressure
per cent * In response to our 45 per cent increase forecast in pre-tax profit for 1987/88, * Despite operating in one of the most
1988/89: the new central distribution Tesco has increased its cash offer by Only 18 per cent competitive environments in the UK
programme is expected to contribute to * Even more shareholders than before think Tesco’s increased and final offer is Hillards has increased sales and profits in
pre-tax profits by around £2.0 million; inadequate—and are staying with Hillards each of the last six years
more new stores will be opened; even Hillards has “uncompetitive and inconsistent
more space will be devoted to higher pricing” and an
margin fresh foods A “inadequate product range”
1989 and beyond: further new * recent independent survey in two towns showed that 80 per cent of the
stores and refurbishments are planned, all products surveyed in the Hillards’ stores were cheaper than or the same price
serviced by the new central distribution facility, together with continuing as the equivalent in the Tesco stores
enhancement of the sales mix and margins * And Hillards’ products were on average between one and two per cent cheaper
than Tesco’s
And Our Future is Secure * An independent survey of 11 grocery product groups showed that a Hillards
* Tesco itself has endorsed the Hillards strategy store had 46 per cent more lines than in a similar sized Tesco store
* Hillards has all the ingredients for continuing strength—an effective site The Hillards strategy will “weaken Hillards’ financial position”’
acquisition policy, a strong capital base, an effective retailing formula and * Gearing is a modest 18 per cent
proven management * The strategy is generating higher profits and cash flow—providing a strong
platform for our future growth
The Message—Shareholder Value The Hillards profit forecast of £15 million is “high risk—mortgaging the
* has produced outstanding shareholder value—a 35 per cent better * The forecast was prepared as part of our normal budgeting process
performance than Tesco over ten years * It takes account of all known competitor openings
* We are confident that our strategy and investments will continue to enhance * It includes no unusual expenditure reductions—the future is not being
mortgaged. Indeed marketing, promotional and advertising expenditure is
shareholder value budgeted to rise materially
STAY WITH HILLARDS STAY WITH HILLARDSKEEP YOUR INVESTMENT IN SUCCESS THE FACT AND THE FICTION Tesco has attempted to frighten you into accepting its inadequate offer by claiming Hillards is a successful company. Tesco has need, but no real reason, to attack it. that your shares will fall substantially if the offer fails. Hillards has outperformed It has sought to construct its case on innuendo regarding Hillards' performance and Tesco as an investment by 35 per cent since1977, as the chart below shows. We future. Let us compare the claims and the facts. believe we can continue to generate excellent£1922 Market Share: A Tesco Claim Answered Hillards has a "shrinking market returns on your investment in this successful % * Over two years Hillards has maintained company in the future. Here's why: £1420 6_| its market share in the Yorkshire TV The Value of region-Tesco's has fallen by over 10 per We Have Made Substantial Investments£100 Invested5_| cent, as illustrated in the chart to the left *Since1980-£72 million spent on fixed Ten Years Ago 3_]*Hillards continues to expand beyond its assets, 14 new stores and a 61 per cent 2 historic Yorkshire base increase in sales area 1 Hillards is suffering from volume"' + Rapid advances made in productivity 0 * In 1986/87like for like volumes are A greater range of higher margin goods, Hillards Tesco expected to rise nearly 3 per cent and continually being extended Source: See Appendix Source: See Appendix overall volumes are expected to rise over Own label grocery sales have doubled in 10 per cent * Recently refurbished stores are showing three years volume gains Our Growth is Accelerating AN OFFER TO BE REFUSED Hillards is "under pressure from competitor *1986/87:profits before tax are estimated Tesco is not offering adequate value for a Company with the accelerating growth of *x Nothing new-we have lived to be £10.3 million-up 21 per cent Hillards: success- *1987/88:profits before tax are forecast * Tesco thought that its original offer was generous-but nearly 97 per cent of fully with this for years to be less than£15.0 Hillards shareholders, other than Tesco and its advisers, did not accept it * store openings put our com- not million-up 45 petitors, including Tesco, under pressure per cent * In response to our 45 per cent increase forecast in pre-tax profit for 1987/88,*Despite operating in one of the most 1988/89: the new central distribution Tesco has increased its cash offer by Only 18 per cent competitive environments in the UK programme is expected to contribute to * Even more shareholders than before think Tesco's increased and final offer is Hillards has increased sales and profits in pre-tax profits by around£2.0 million; inadequate-and are staying with Hillards each of the last six years more new stores will be opened; even Hillards has "uncompetitive and inconsistent more space will be devoted to higher pricing" and an margin fresh foods A "inadequate product range" 1989 and beyond: further new * recent independent survey in two towns showed that 80 per cent of the stores and refurbishments are planned, all products surveyed in the Hillards' stores were cheaper than or the same price serviced by the new central distribution facility, together with continuing as the equivalent in the Tesco stores enhancement of the sales mix and margins * And Hillards' products were on average between one and two per cent cheaper than Tesco's And Our Future is Secure * An independent survey of 11 grocery product groups showed that a Hillards * Tesco itself has endorsed the Hillards strategy store had 46 per cent more lines than in a similar sized Tesco store * Hillards has all the ingredients for continuing strength-an effective site The Hillards strategy will "weaken Hillards' financial position"' acquisition policy, a strong capital base, an effective retailing formula and * Gearing is a modest 18 per cent proven management * The strategy is generating higher profits and cash flow-providing a strong platform for our future growth The Message-Shareholder Value The Hillards profit forecast of £15million is "high risk-mortgaging the * has produced outstanding shareholder value-a 35 per cent better * The forecast was prepared as part of our normal budgeting process performance than Tesco over ten years * It takes account of all known competitor openings * We are confident that our strategy and investments will continue to enhance * It includes no unusual expenditure reductions-the future is not being mortgaged. Indeed marketing, promotional and advertising expenditure is shareholder value budgeted to rise materially STAY WITH HILLARDS STAY WITH HILLARDS
Read by machine, contrast corrected highest quality of the three
KEEP YOUR INVESTMENT IN SUCCESS THE FACT AND THE FICTION
Tesco has attempted to frighten you into accepting its inadequate offer by claiming Hillards is a successful company. Tesco has need, but no real reason, to attack it.
that your shares will fall substantially if the offer fails. Hillards has outperformed It has sought to construct its case on innuendo regarding Hillards’ performance and
Tesco as an investment by 35 per cent since 1977, as the chart below shows. We future. Let us compare the claims and the facts.
believe we can continue to generate excellent £1922 Market Share: A Tesco Claim Answered Hillards has a “shrinking market share”
returns on your investment in this successful % * Over two years Hillards has maintained
company in the future. Here’s why: £1420 6_| its market share in the Yorkshire TV
The Value of region—Tesco’s has fallen by over 10 per
We Have Made Substantial Investments £100 Invested 5_| cent, as illustrated in the chart to the left
* Since 1980—£72 million spent on fixed Ten Years Ago 45 * Hillards continues to expand beyond its
assets, 14 new stores and a 61 per cent 34 historic Yorkshire base
increase in sales area 2 Hillards is
1 suffering from volume’”’
+ Rapid advances made in productivity 0 Mar 87 * In 1986/87 like for like volumes are
A greater range of higher margin goods, Hillards Tesco Hillards Tesco expected to rise nearly 3 per cent and
continually being extended Source: ll 1 expected
See Appendix Source: See Appendix overall volumes are to rise over
Own label grocery sales have doubled in 10 per cent
* Recently refurbished stores are showing
three years volume gains
Our Growth is Accelerating AN OFFER TO BE REFUSED Hillards is “under pressure from competitor
* 1986/87: profits before tax are estimated Tesco is not offering adequate value for a Company with the accelerating growth of *x Nothing new—we have lived
to be £10.3 million—up 21 per cent Hillards: success-
* 1987/88: profits before tax are forecast * Tesco thought that its original offer was generous—but nearly 97 per cent of fully with this for years
to be less than £15.0 Hillards shareholders, other than Tesco and its advisers, did not accept it * store openings put our com-
not million—up 45 petitors, including Tesco, under pressure
per cent * In response to our 45 per cent increase forecast in pre-tax profit for 1987/88, * Despite operating in one of the most
1988/89: the new central distribution Tesco has increased its cash offer by Only 18 per cent competitive environments in the UK
programme is expected to contribute to * Even more shareholders than before think Tesco’s increased and final offer is Hillards has increased sales and profits in
pre-tax profits by around £2.0 million; inadequate—and are staying with Hillards each of the last six years
more new stores will be opened; even Hillards has “uncompetitive and inconsistent
more space will be devoted to higher pricing” and an
margin fresh foods A “inadequate product
1989 and beyond: further new * recent independent survey in two towns showed that 80 per cent of the
stores and refurbishments are planned, all products surveyed in the Hillards’ stores were cheaper than or the same price
serviced by the new central distribution facility, together with continuing as the equivalent in the Tesco stores
enhancement of the sales mix and margins * And Hillards’ products were on average between one and two per cent cheaper
than Tesco’s
And Our Future is Secure * An independent survey of 11 grocery product groups showed that a Hillards
* Tesco itself has endorsed the Hillards strategy store had 46 per cent more lines than in a similar sized Tesco store
* Hillards has all the ingredients for continuing strength—an effective site The Hillards strategy will “weaken Hillards’ financial position”’
acquisition policy, a strong capital base, an effective retailing formula and * Gearing is a modest 18 per cent
proven management * The strategy is generating higher profits and cash flow—providing a strong
platform for our future growth
The Message—Shareholder Value The Hillards profit forecast of £15 million is “high risk—mortgaging the
* Hillards has produced outstanding shareholder value—a 35 per cent better * The forecast was prepared as part of our normal budgeting process
performance than Tesco over ten years * takes account of all known competitor openings
* We are confident that our strategy and investments will continue to enhance * It includes no unusual expenditure reductions—the future is not being
mortgaged. Indeed marketing, promotional and advertising expenditure is
shareholder value budgeted to rise materially
STAY WITH HILLARDS STAY WITH HILLARDSKEEP YOUR INVESTMENT IN SUCCESS THE FACT AND THE FICTION Tesco has attempted to frighten you into accepting its inadequate offer by claiming Hillards is a successful company. Tesco has need, but no real reason, to attack it. that your shares will fall substantially if the offer fails. Hillards has outperformed It has sought to construct its case on innuendo regarding Hillards' performance and Tesco as an investment by 35 per cent since1977, as the chart below shows. We future. Let us compare the claims and the facts. believe we can continue to generate excellent£1922 Market Share: A Tesco Claim Answered Hillards has a "shrinking market share" returns on your investment in this successful % * Over two years Hillards has maintained company in the future. Here's why: £1420 6_| its market share in the Yorkshire TV The Value of region-Tesco's has fallen by over 10 per We Have Made Substantial Investments£100 Invested5_| cent, as illustrated in the chart to the left *Since1980-£72 million spent on fixed Ten Years Ago 45 * Hillards continues to expand beyond its assets, 14 new stores and a 61 per cent 34 historic Yorkshire base increase in sales area 2 Hillards is 1 suffering from volume'"' + Rapid advances made in productivity 0 Mar 87 * In 1986/87like for like volumes are A greater range of higher margin goods, Hillards Tesco Hillards Tesco expected to rise nearly 3 per cent and continually being extended Source: ll 1 expected See Appendix Source: See Appendix overall volumes are to rise over Own label grocery sales have doubled in 10 per cent * Recently refurbished stores are showing three years volume gains Our Growth is Accelerating AN OFFER TO BE REFUSED Hillards is "under pressure from competitor *1986/87:profits before tax are estimated Tesco is not offering adequate value for a Company with the accelerating growth of *x Nothing new-we have lived to be £10.3 million-up 21 per cent Hillards: success- *1987/88:profits before tax are forecast * Tesco thought that its original offer was generous-but nearly 97 per cent of fully with this for years to be less than£15.0 Hillards shareholders, other than Tesco and its advisers, did not accept it * store openings put our com- not million-up 45 petitors, including Tesco, under pressure per cent * In response to our 45 per cent increase forecast in pre-tax profit for 1987/88,*Despite operating in one of the most 1988/89: the new central distribution Tesco has increased its cash offer by Only 18 per cent competitive environments in the UK programme is expected to contribute to * Even more shareholders than before think Tesco's increased and final offer is Hillards has increased sales and profits in pre-tax profits by around£2.0 million; inadequate-and are staying with Hillards each of the last six years more new stores will be opened; even Hillards has "uncompetitive and inconsistent more space will be devoted to higher pricing" and an margin fresh foods A "inadequate product 1989 and beyond: further new * recent independent survey in two towns showed that 80 per cent of the stores and refurbishments are planned, all products surveyed in the Hillards' stores were cheaper than or the same price serviced by the new central distribution facility, together with continuing as the equivalent in the Tesco stores enhancement of the sales mix and margins * And Hillards' products were on average between one and two per cent cheaper than Tesco's And Our Future is Secure * An independent survey of 11 grocery product groups showed that a Hillards * Tesco itself has endorsed the Hillards strategy store had 46 per cent more lines than in a similar sized Tesco store * Hillards has all the ingredients for continuing strength-an effective site The Hillards strategy will "weaken Hillards' financial position"' acquisition policy, a strong capital base, an effective retailing formula and * Gearing is a modest 18 per cent proven management * The strategy is generating higher profits and cash flow-providing a strong platform for our future growth The Message-Shareholder Value The Hillards profit forecast of £15million is "high risk-mortgaging the * Hillards has produced outstanding shareholder value-a 35 per cent better * The forecast was prepared as part of our normal budgeting process performance than Tesco over ten years * takes account of all known competitor openings * We are confident that our strategy and investments will continue to enhance * It includes no unusual expenditure reductions-the future is not being mortgaged. Indeed marketing, promotional and advertising expenditure is shareholder value budgeted to rise materially STAY WITH HILLARDS STAY WITH HILLARDS