Hillards Eight Years of Succesive Growth Report page 4 of 24 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
                                            SPEN LANE, GOMERSAL, CLECKHEATON,  WEST YORKS, BD19 4PW
P E T E R H A R T L E Y C h a i r m a n
                                                                               23    April     1987
To     Shareholders     and,     for information only. Share     Option             Holders


It     is     now    a     month           since             I wrote             to you     in detail            about            the            wholly
unwelcome and     opportunist                                bid from             Tesco.     The            fact that          Tesco               have
                                                                               been able to buy only 6.5 per cent of Hillards shares and that almost 97
per         cent     of     the     remaining            Hillards            shareholders               have not                           accepted the
offer         shows     conclusively                     what   you,             the  owners            of     Hillards,       think              about
t h e       Te s c o o f f e r.

By now          I   would              have     hoped that                   the     Chairman               of     Tesco       would               have
                                                                                   withdrawn the offer thus saving the shareholders of both companies a
great           deal of     expense                      and    the          managements                    a large                   amount  of
non-productive     time.
I N         J U L Y     T H I S        Y E A R               W E     S H A L L B E                                   R E C O M M E N D I N G          A
EINAL             DIVIDEND                 OF            2.825p      FOR                       1986/87, MAKING                    4.0p              FOR
THE YEAR, AN INCREASE OF                                             21                                                         PER CENT OVER THE TOTAL
D I V I D E N D     F O R              T H E             P R E V I O U S         Y E A R .

YO U R          BOA RD                 IS     NOW FO R ECAST ING                 THAT                       P RO F IT                        B E FO R E
                                                                                                  TAX FOR THE YEAR 1987/88 WILL INCREASE BY 45 PER CENT
T O         N O T    L E S S           T H A N           £ 1 5 M I L L I O N .
                                                                                    You will recently have received a further document from Tesco which
is     both     emotional                  and           threatening-it                           bases     the Tesco             case               on
unfounded innuendo                         regarding                       the long term                future   of            Hillards.             In
addition        the                      Tesco document                    contains     numerous            half-truths                             and
                                                                                 misrepresentations and is totally unworthy of a company that claims so
m u c h         f o r i t s e l f .

F o r       i n s t a n c e :
                                                                                    ★ Tesco claims that the Hillards strategy will weaken our financial
                                                                                position and that the rights issue is evidence of balance sheet strain.
                                                                                  This is clearly nonsense: gearing is now modest and the rights issue,
            the first     for     fifteen                years,   together       with     the outstanding                                        growth
                                                                                 forecast in profits provide a strong financial platform to support our
                                                                                    progress into the 1990s. Incidentally Tesco raised £150 million via
            a    rights     issue           in May,      1985.
★ Te s c o      c l a i m s                t h a t       H i l l a r d s '       p r i c i n g a n d        p r o d u c t      r a n g e          a r e
                                                                                     uncompetitive and inadequate and that we find it difficult both to
            afford    the     best         sites         and   to     generate     adequate                 returns            from               them.
            The evidence is to the contrary. The surveys described in                                                                              this
            document                      show that      Hillards'           pricing     against         Tesco                 in stores      of
            comparable                    size is     more competitive           and     that          Hillards                has a              wider
                                                                                 Droduct range. As far as sites are concerned, the very fact that Tesco
            las  bid for                  your company is                    proof    that     Hillards   has                 succeeded              in
            finding sites                        where   Tesco   has         failed.     As for         adequate               returns,             our
            profit             record  and           a   strong            profit growth     generated                    from                new store
            openings     speak for                       themselves.
Dlftttorj   P.AH MARTLET ChjJrrrun R  J.DOWDS M»rn|ln| F R.OEE DJ.FLEMMING f .C.A J.P FROST A. A GREEN J.LYLES C 0 £ J.P  0 Sc A.G.MARTIN F C A RWSTQTT
                                                             Re|lJte/ed Number 24301 i Enjlind
SPEN LANE, GOMERSAL, CLECKHEATON, WEST YORKS, BD19 4PW PETERHARTLEYChairman 23April1987 To Shareholders and, for information only. Share Option Holders It is now a month since I wrote to you in detail about the wholly unwelcome and opportunist bid from Tesco. The fact that Tesco have been able to buy only6.5 per cent of Hillards shares and that almost 97 per cent of the remaining Hillards shareholders have not accepted the offer shows conclusively what you, the owners of Hillards, think about the Te scooffe r. By now I would have hoped that the Chairman of Tesco would have withdrawn the offer thus saving the shareholders of both companies a great deal of expense and the managements a large amount of non-productive time. INJULYTHISYEARWESHALLBERECOMMENDINGA EINAL DIVIDEND OF 2.825p FOR 1986/87,MAKING 4.0p FOR THE YEAR, AN INCREASE OF 21 PER CENT OVER THE TOTAL DIVIDENDFORTHEPREVIOUSYEAR . YO U R BOA RD IS NOW FORECAST ING THAT P RO F IT B E FO R E TAX FOR THE YEAR1987/88 WILL INCREASE BY 45 PER CENT TONOTLESSTHAN£15MILLION . You will recently have received a further document from Tesco which is both emotional and threatening-it bases the Tesco case on unfounded innuendo regarding the long term future of Hillards. In addition the Tesco document contains numerous half-truths and misrepresentations and is totally unworthy of a company that claims so muchforitself . Forinstance : ★ Tesco claims that the Hillards strategy will weaken our financial position and that the rights issue is evidence of balance sheet strain. This is clearly nonsense: gearing is now modest and the rights issue, the first for fifteen years, together with the outstanding growth forecast in profits provide a strong financial platform to support our progress into the 1990s. Incidentally Tesco raised£150 million via a rights issue in May, 1985. ★ Te scoclaimsthatHillards ' pricingandproductrangeare uncompetitive and inadequate and that we find it difficult both to afford the best sites and to generate adequate returns from them. The evidence is to the contrary. The surveys described in this document show that Hillards' pricing against Tesco in stores of comparable size is more competitive and that Hillards has a wider Droduct range. As far as sites are concerned, the very fact that Tesco las bid for your company is proof that Hillards has succeeded in finding sites where Tesco has failed. As for adequate returns, our profit record and a strong profit growth generated from new store openings speak for themselves. Dlftttorj P.AH MARTLET ChjJrrrun R J.DOWDS M»rn|ln| F R.OEE DJ.FLEMMING f .C.A J.P FROST A. A GREEN J.LYLES C0£ J.P 0 Sc A.G.MARTIN FCA RWSTQTT Re|lJte/ed Number24301 i Enjlind
Read by machine
HILLARDS pic

                                                                          AE     OFFICE
                                                                      SPEN LANE, GOMERSAL, CLECKHEATON, WEST YORKS, BD19 4PW
    PETER HARTLEY  Chairman
                                                                                                         23 April       1987
    To Shareholders and, for information only, Share Option                                              Holders

    Dear
    It  is     now a month     since                I     wrote          to     you     in     detail about the       wholly
    unwelcome and opportunist bid from Tesco. The                         fact that Tesco                               have
    been able     to buy only 6.5               per                   cent  of Hillards shares and that almost            97
    per  cent  of the     remaining Hillards shareholders have not                                              accepted the
    offer shows conclusively what                                     you, the     owners     of Hillards,       think about
    the Tesco offer.

    By  now    I   would have hoped that the Chairman                                                    of Tesco would have
    withdrawn the offer thus saving the shareholders of both                                             companies         a
    great     deal   of expense                 and                   the  managements     a     large      amount      of
    non-productive time.
    IN   JULY THIS YEAR WE SHALL                                          BE                                  RECOMMENDING A
    FINAL DIVIDEND OF 2.825p FOR                                          1986/87,                           MAKING 4.0p FOR
THE YEAR, AN INCREASE OF 21 PER CENT OVER THE TOTAL
DIVIDEND FOR THE PREVIOUS YEAR.

    YOUR BOARD IS NOW FORECASTING THAT                                                                         PROFIT BEFORE
    TAX FOR THE YEAR 1987/88 WILL                                         INCREASE BY 45                            PER CENT
    TO NOT LESS THAN £15 MILLION.

    You will recently have received                                      a further document     from Tesco             which
    is  both     emotional     and                  threatening—it        bases     the                 Tesco case        on
    unfounded     innuendo     regarding                                 the     long   term     future  of Hillards.     In
    addition     the    Tesco     document                                contains     numerous         half-truths      and
    misrepresentations and is totally unworthy of                         a     company                  that claims      so
    much for itself.

    For instance:

    *    Tesco claims     that     the              Hillards              strategy     will     weaken   our       financial
         position and that the rights issue is                            evidence of balance               sheet    strain.
         This is clearly     nonsense:              gearing is            now     modest and the            rights    issue,
         the   first for    fifteen             years,                   together     with     the    outstanding     growth
         forecast in profits provide                                  a  strong     financial platform to       support  our
         progress into the     1990s.               Incidentally Tesco                              raised £150 million  via
         a     rights issue     in     May,         1985.
         Tesco     claims     that              Hillards’                 pricing     and     product       range        are
         uncompetitive and inadequate and that                                       we     find it difficult     both    to
         afford    the  best     sites          and                   to generate adequate     returns            from them.
         The evidence     is     to             the                   contrary.     The     surveys   described   in    this
    document show that Hillards’ pricing against Tesco in stores of
         comparable size is     more                                  competitive and that Hillards has     a     wider
         product     range.     As far          as     sites             are     concerned, the     very     fact that Tesco
         has bid for     your company                                    is proof that     Hillards   has succeeded       in
         finding sites     where Tesco has failed.                        As for adequate returns,                       our
         profit record    and     a     strong                          profit growth     generated from     new       store
         openings speak for themselves.

    Directors: PAH. HARTLEY Executive Charman — R.J.OOWDS Managing        J.P                           BSc AGMARTINFCA
                                                                      Registered Number 24301! England
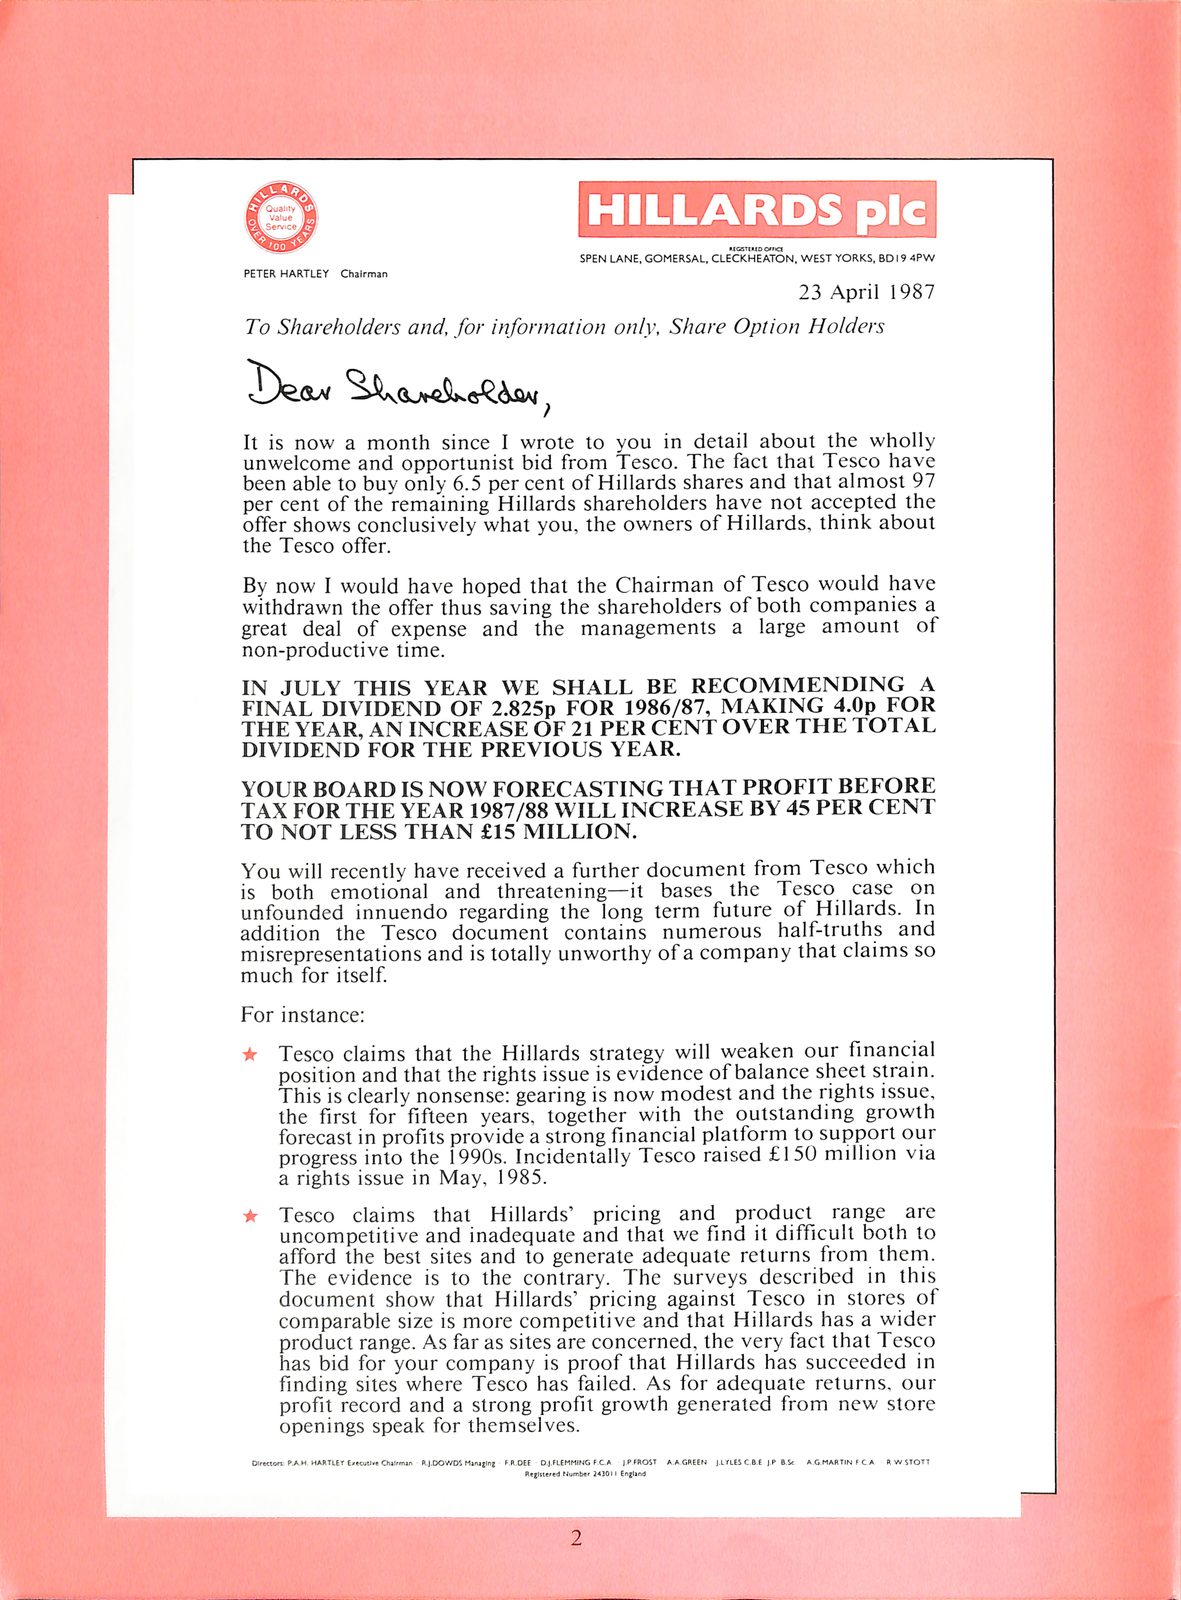
HILLARDS pic AE OFFICE SPEN LANE, GOMERSAL, CLECKHEATON, WEST YORKS, BD19 4PW PETER HARTLEY Chairman 23April1987 To Shareholders and, for information only, Share Option Holders Dear It is now a month since I wrote to you in detail about the wholly unwelcome and opportunist bid from Tesco. The fact that Tesco have been able to buy only6.5 per cent of Hillards shares and that almost 97 per cent of the remaining Hillards shareholders have not accepted the offer shows conclusively what you, the owners of Hillards, think about the Tesco offer. By now I would have hoped that the Chairman of Tesco would have withdrawn the offer thus saving the shareholders of both companies a great deal of expense and the managements a large amount of non-productive time. IN JULY THIS YEAR WE SHALL BE RECOMMENDING A FINAL DIVIDEND OF 2.825p FOR 1986/87,MAKING 4.0p FOR THE YEAR, AN INCREASE OF 21 PER CENT OVER THE TOTAL DIVIDEND FOR THE PREVIOUS YEAR. YOUR BOARD IS NOW FORECASTING THAT PROFIT BEFORE TAX FOR THE YEAR1987/88 WILL INCREASE BY 45 PER CENT TO NOT LESS THAN£15 MILLION. You will recently have received a further document from Tesco which is both emotional and threatening-it bases the Tesco case on unfounded innuendo regarding the long term future of Hillards. In addition the Tesco document contains numerous half-truths and misrepresentations and is totally unworthy of a company that claims so much for itself. For instance: * Tesco claims that the Hillards strategy will weaken our financial position and that the rights issue is evidence of balance sheet strain. This is clearly nonsense: gearing is now modest and the rights issue, the first for fifteen years, together with the outstanding growth forecast in profits provide a strong financial platform to support our progress into the 1990s. Incidentally Tesco raised£150 million via a rights issue in May, 1985. Tesco claims that Hillards' pricing and product range are uncompetitive and inadequate and that we find it difficult both to afford the best sites and to generate adequate returns from them. The evidence is to the contrary. The surveys described in this document show that Hillards' pricing against Tesco in stores of comparable size is more competitive and that Hillards has a wider product range. As far as sites are concerned, the very fact that Tesco has bid for your company is proof that Hillards has succeeded in finding sites where Tesco has failed. As for adequate returns, our profit record and a strong profit growth generated from new store openings speak for themselves. Directors: PAH. HARTLEY Executive Charman - R.J.OOWDS Managing J.P BSc AGMARTINFCA Registered Number24301! England
Read by machine, contrast corrected highest quality of the three
HILLARDS pic

                                                                       Ae     OFFICE
                                                                   SPEN LANE, GOMERSAL, CLECKHEATON, WEST YORKS, BD19 4PW
    PETER HARTLEY  Chairman
                                                                                                    23 April         1987
    To Shareholders and, for information only, Share Option                                         Holders

    Dear                                                           ;
    It  is     now a month     since                    I     wrote   to     you  in     detail about the          wholly
    unwelcome and opportunist bid from Tesco. The                      fact that Tesco                               have
    been able     to buy only 6.5                   per         cent  of Hillards shares and that almost               97
    per  cent  of the remaining Hillards shareholders have not                                               accepted the
    offer shows conclusively what                               you,  the     owners     of Hillards,         think about
    the Tesco offer.

    By  now    I   would have hoped that the Chairman                                                 of Tesco would have
    withdrawn the offer thus saving the shareholders of both                                        companies           a
    great     deal   of expense                     and         the   managements     a     large     amount        of
    non-productive time.
    IN   JULY THIS YEAR WE SHALL                                       BE                                  RECOMMENDING A
    FINAL DIVIDEND OF 2.825p FOR                                       1986/87,                           MAKING 4.0p FOR
THE YEAR, AN INCREASE OF 21 PER CENT OVER THE TOTAL
DIVIDEND FOR THE PREVIOUS YEAR.

    YOUR BOARD IS NOW FORECASTING THAT                                                                      PROFIT BEFORE
    TAX FOR THE YEAR 1987/88 WILL                                      INCREASE BY 45                            PER CENT
    TO NOT LESS THAN £15 MILLION.

    You will recently have received                                 a further document     from Tesco               which
    is  both     emotional     and                      threatening—it     bases     the           Tesco case          on
    unfounded     innuendo     regarding                              the     long term     future  of Hillards.       In
    addition     the    Tesco     document                            contains     numerous        half-truths        and
    misrepresentations and is totally unworthy of                      a     company                that claims        so
    much for itself.

    For instance:

    *    Tesco claims     that     the                  Hillards       strategy     will     weaken our         financial
         position and that the rights issue is                         evidence of balance            sheet       strain.
         This is clearly     nonsense:                  gearing is     now     modest and the         rights       issue,
         the   first for    fifteen                 years,         together     with     the    outstanding        growth
         forecast in profits provide                            a  strong     financial platform to         support   our
         progress into the     1990s.                   Incidentally Tesco                      raised £150 million   via
         a     rights issue     in     May,             1985.
         Tesco     claims     that                  Hillards’          pricing     and     product    range           are
         uncompetitive and inadequate and that                                  we     find it difficult    both       to
         afford    the  best     sites              and         to  generate adequate     returns              from them.
         The evidence     is     to                 the         contrary.     The     surveys   described   in       this
    document show that Hillards’ pricing against Tesco in stores of
         comparable size is     more                             competitive and that Hillards has     a     wider
         product     range.     As far              as     sites    are     concerned, the     very       fact that Tesco
         has bid for     your company                              is proof that     Hillards   has succeeded          in
         finding sites     where Tesco has failed.                     As for adequate returns,                       our
         profit record    and     a     strong                    profit growth     generated from     new          store
         openings speak for themselves.

    Directors: PAH. HARTLEY Executive Chairman —    Managing           J.P                         BSc AGMARTINF.CA
                                                                Registered Number 24301! England
HILLARDS pic Ae OFFICE SPEN LANE, GOMERSAL, CLECKHEATON, WEST YORKS, BD19 4PW PETER HARTLEY Chairman 23April1987 To Shareholders and, for information only, Share Option Holders Dear ; It is now a month since I wrote to you in detail about the wholly unwelcome and opportunist bid from Tesco. The fact that Tesco have been able to buy only6.5 per cent of Hillards shares and that almost 97 per cent of the remaining Hillards shareholders have not accepted the offer shows conclusively what you, the owners of Hillards, think about the Tesco offer. By now I would have hoped that the Chairman of Tesco would have withdrawn the offer thus saving the shareholders of both companies a great deal of expense and the managements a large amount of non-productive time. IN JULY THIS YEAR WE SHALL BE RECOMMENDING A FINAL DIVIDEND OF 2.825p FOR 1986/87,MAKING 4.0p FOR THE YEAR, AN INCREASE OF 21 PER CENT OVER THE TOTAL DIVIDEND FOR THE PREVIOUS YEAR. YOUR BOARD IS NOW FORECASTING THAT PROFIT BEFORE TAX FOR THE YEAR1987/88 WILL INCREASE BY 45 PER CENT TO NOT LESS THAN£15 MILLION. You will recently have received a further document from Tesco which is both emotional and threatening-it bases the Tesco case on unfounded innuendo regarding the long term future of Hillards. In addition the Tesco document contains numerous half-truths and misrepresentations and is totally unworthy of a company that claims so much for itself. For instance: * Tesco claims that the Hillards strategy will weaken our financial position and that the rights issue is evidence of balance sheet strain. This is clearly nonsense: gearing is now modest and the rights issue, the first for fifteen years, together with the outstanding growth forecast in profits provide a strong financial platform to support our progress into the 1990s. Incidentally Tesco raised£150 million via a rights issue in May, 1985. Tesco claims that Hillards' pricing and product range are uncompetitive and inadequate and that we find it difficult both to afford the best sites and to generate adequate returns from them. The evidence is to the contrary. The surveys described in this document show that Hillards' pricing against Tesco in stores of comparable size is more competitive and that Hillards has a wider product range. As far as sites are concerned, the very fact that Tesco has bid for your company is proof that Hillards has succeeded in finding sites where Tesco has failed. As for adequate returns, our profit record and a strong profit growth generated from new store openings speak for themselves. Directors: PAH. HARTLEY Executive Chairman - Managing J.P BSc AGMARTINF.CA Registered Number24301! England