Tesco plc Annual Report and Accounts 1986 page 36 of 48 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Read by machine highest quality of the three
    NOTES TO THE ACCOUNTS


    3. Interest

                                                              1986                                         1985
                                                                                                       £m  £m

Interest receivable and similar income on Money Market investments and
    deposits                                                  26.7                                         7.4
Deduct interest payable on: Short term bank loans and overdrafts repayable
                                      within 5 years         (15.2)                                       (2.7)
                                      Finance charges payable on finance leases                   (0.1)   (0.1)
                                      9% Convertible unsecured loan stock 2002/2007               (5.0)   (5.0)
                                      Interest capitalised    12.4                                             —

                                                                                                          (7.8)
                                                              18.8                                        (0.4)

 Interest payable on funds used to finance the initial acquisition and development of land and buildings
has been capitalised. No adjustment has been made to the results for the previous year as the amount
involved would have been immaterial.

    4, Taxation

                                                                                                     1986  1985
                                                               £m                                            £m

    United Kingdom taxation
    Corporation tax at 40.5%     1985 — 45.5%                                                    50.1      30.8
    Deferred taxation                                         (1.5)                                         1.3
    Prior year  adjustments                                   (1.5)                                        (2.0)
                                                                                                 47.1      30.1

    Overseas taxation
    Corporate taxes                                                                               0.1       0.2
                                                                                                 47.2      30.3

After deducting tax relief of £4.8m 1985 — £nil) on interest capitalised, the net amount of £45.3m
less advance corporation tax is the corporation tax payable in January, 1987.
    The group   tax charge for the year has been reduced by £2.1m 1985     —   £4.1m) in respect of accelerated
    capital allowances   on  which no provision for deferred tax is required. Net surplus on sale of properties
is net of taxation amounting to £0.2m 1985 — £0.9m). Where possible taxation on capital gains has
been or will be deferred by rollover relief under the provisions of the Taxes Acts (Note 14).

    5. Extraordinary items after taxation
                                                                                                 1986
                                                                                                   £m        £m
    Net surplus on disposal    of the Victor Value business    8.6                                            —
    Provision for deficit    on disposal of Tesco Stores Ireland Limited        (16.2)                        —

    Less: taxation effect                                      0.2                                            —


    34
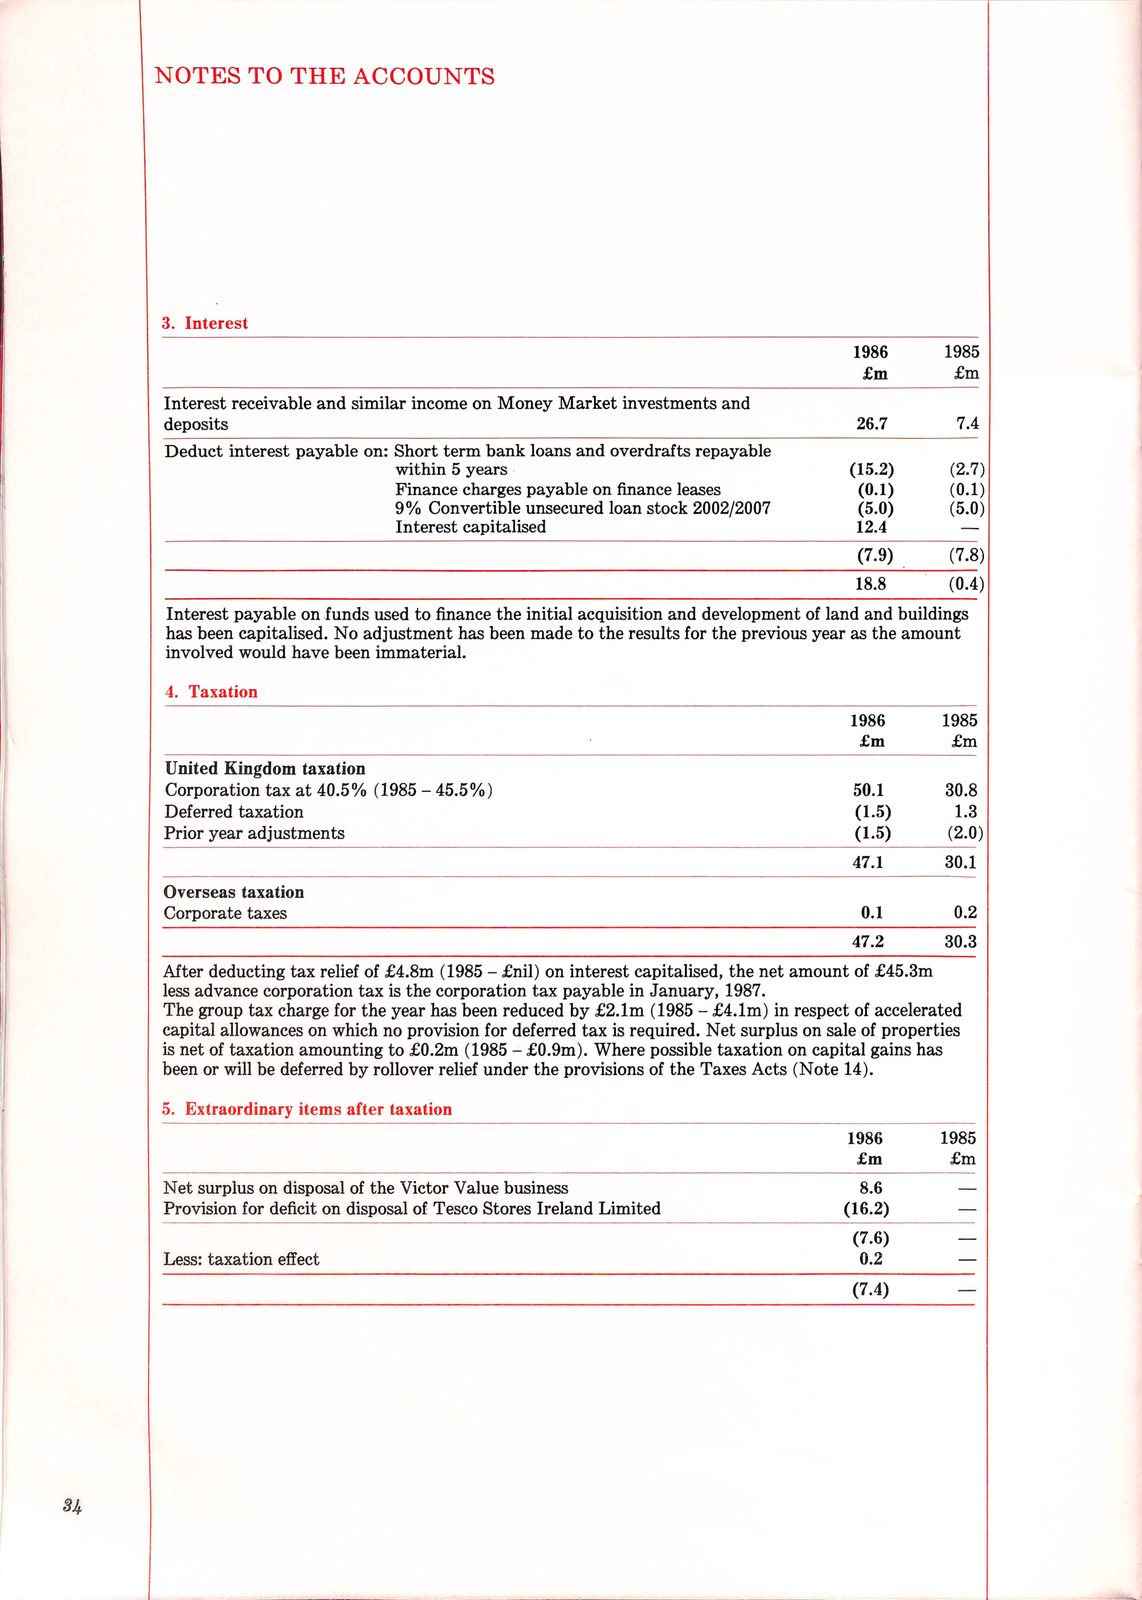
NOTES TO THE ACCOUNTS 3. Interest 1986 1985 £m £m Interest receivable and similar income on Money Market investments and deposits26.77.4 Deduct interest payable on: Short term bank loans and overdrafts repayable within 5years(15.2) (2.7) Finance charges payable on finance leases(0.1)(0.1) 9% Convertible unsecured loan stock2002/2007(5.0) (5.0) Interest capitalised12.4- (7.8) 18.8 (0.4) Interest payable on funds used to finance the initial acquisition and development of land and buildings has been capitalised. No adjustment has been made to the results for the previous year as the amount involved would have been immaterial. 4, Taxation 1986 1985 £m £m United Kingdom taxation Corporation tax at 40.5% 1985 - 45.5% 50.1 30.8 Deferred taxation(1.5)1.3 Prior year adjustments(1.5)(2.0) 47.1 30.1 Overseas taxation Corporate taxes0.10.2 47.2 30.3 After deducting tax relief of £4.8m 1985 - £nil) on interest capitalised, the net amount of £45.3m less advance corporation tax is the corporation tax payable in January,1987. The group tax charge for the year has been reduced by £2.1m 1985 - £4.1m) in respect of accelerated capital allowances on which no provision for deferred tax is required. Net surplus on sale of properties is net of taxation amounting to £0.2m 1985 - £0.9m). Where possible taxation on capital gains has been or will be deferred by rollover relief under the provisions of the Taxes Acts (Note14). 5. Extraordinary items after taxation 1986 £m £m Net surplus on disposal of the Victor Value business8.6- Provision for deficit on disposal of Tesco Stores Ireland Limited(16.2)- Less: taxation effect0.2- 34
Read by machine, contrast corrected
    NOTES TO THE ACCOUNTS


    3. Interest

                                                              1986                                         1985
                                                                                                       £m  £m

Interest receivable and similar income on Money Market investments and
    deposits                                                  26.7                                         7.4
Deduct interest payable on: Short term bank loans and overdrafts repayable
                                      within 5 years         (15.2)                                       (2.7)
                                      Finance charges payable on finance leases                   (0.1)   (0.1)
                                      9% Convertible unsecured loan stock 2002/2007               (5.0)   (5.0)
                                      Interest capitalised    12.4                                             —

                                                                                                          (7.8)
                                                              18.8                                        (0.4)

 Interest payable on funds used to finance the initial acquisition and development of land and buildings
has been capitalised. No adjustment has been made to the results for the previous year as the amount
involved would have been immaterial.

    4, Taxation

                                                                                                     1986  1985
                                                               £m                                            £m

    United Kingdom taxation
    Corporation tax at 40.5%     1985 — 45.5%                                                    50.1      30.8
    Deferred taxation                                         (1.5)                                         1.3
    Prior year  adjustments                                   (1.5)                                        (2.0)
                                                                                                 47.1      30.1

    Overseas taxation
    Corporate taxes                                                                               0.1       0.2
                                                                                                 47.2      30.3

After deducting tax relief of £4.8m 1985 — £nil) on interest capitalised, the net amount of £45.38m
less advance corporation tax is the corporation tax payable in January, 1987.
    The group   tax charge for the year has been reduced by £2.1m 1985     —   £4.1m) in respect of accelerated
    capital allowances   on  which no provision for deferred tax is required. Net surplus on sale of properties
is net of taxation amounting to £0.2m 1985 — £0.9m). Where possible taxation on capital gains has
been or will be deferred by rollover relief under the provisions of the Taxes Acts (Note 14).

    5. Extraordinary items after taxation
                                                                                                 1986
                                                                                                   £m        £m
    Net surplus on disposal    of the Victor Value business    8.6                                            —
    Provision for deficit    on disposal of Tesco Stores Ireland Limited        (16.2)                        —

    Less: taxation effect                                      0.2                                            —


    34
NOTES TO THE ACCOUNTS 3. Interest 1986 1985 £m £m Interest receivable and similar income on Money Market investments and deposits26.77.4 Deduct interest payable on: Short term bank loans and overdrafts repayable within 5years(15.2) (2.7) Finance charges payable on finance leases(0.1)(0.1) 9% Convertible unsecured loan stock2002/2007(5.0) (5.0) Interest capitalised12.4- (7.8) 18.8 (0.4) Interest payable on funds used to finance the initial acquisition and development of land and buildings has been capitalised. No adjustment has been made to the results for the previous year as the amount involved would have been immaterial. 4, Taxation 1986 1985 £m £m United Kingdom taxation Corporation tax at 40.5% 1985 - 45.5% 50.1 30.8 Deferred taxation(1.5)1.3 Prior year adjustments(1.5)(2.0) 47.1 30.1 Overseas taxation Corporate taxes0.10.2 47.2 30.3 After deducting tax relief of £4.8m 1985 - £nil) on interest capitalised, the net amount of £45.38m less advance corporation tax is the corporation tax payable in January,1987. The group tax charge for the year has been reduced by £2.1m 1985 - £4.1m) in respect of accelerated capital allowances on which no provision for deferred tax is required. Net surplus on sale of properties is net of taxation amounting to £0.2m 1985 - £0.9m). Where possible taxation on capital gains has been or will be deferred by rollover relief under the provisions of the Taxes Acts (Note14). 5. Extraordinary items after taxation 1986 £m £m Net surplus on disposal of the Victor Value business8.6- Provision for deficit on disposal of Tesco Stores Ireland Limited(16.2)- Less: taxation effect0.2- 34