For Information Only-Offer by County Limited on behalf of Tesco plc for Hillards plc page 2 of 38 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
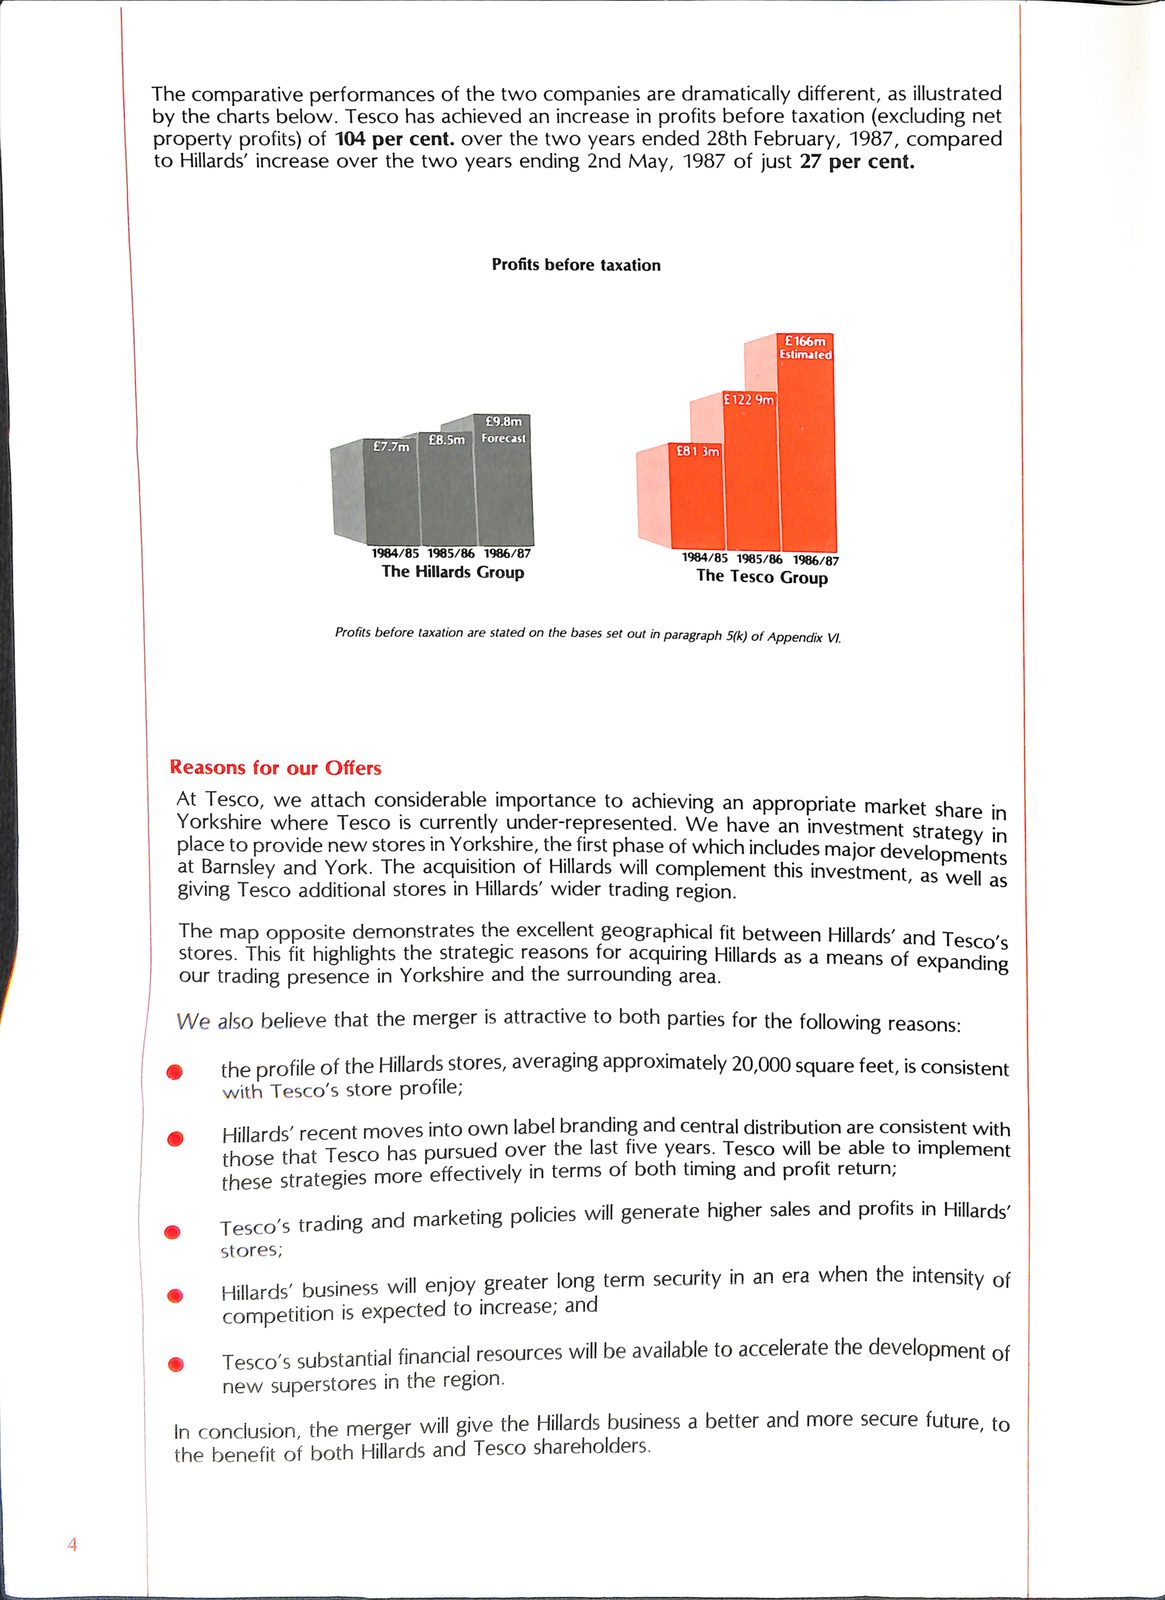
The comparative performances of the two companies are dramatically different, as illustrated
by the charts below. Tesco has achieved an increase in profits before taxation (excluding net
property profits) of 104 per cent, over the two years ended 28th February, 1987, compared
to Hillards' increase over the two years ending 2nd May, 1987 of just 27 per cent.


    Profits before taxation

                           £1 6 6 m
                           Estiii Mled


 1964/85 1965/86  1986/87    1984/85 1985/86                                     1986/87
   The Hillards   Group      The Tesco Group

Profits before taxation are stated on the bases set out in paragraph5(k) of Appendix VI.


 R e a s o n s f o r o u r O ff e r s
 At Tesco, we attach considerable importance to achieving an appropriate market share in
 Yorkshire where Tesco is currently under-represented. We have an investment strateev
 place to provide new stores in Yorkshire, the first phase of which includes major develonmenK
 at Barnsley and York. The acquisition of Hillards will complement this investment, as well
 giving Tesco additional stores in Hillards' wider trading region. '
  The map opposite demonstrates the excellent geographical fit between Hillards' and Tesco's
  stores. This fit highlights the strategic reasons for acquiring Hillards as a means of expanding
    our trading     presence in     Yorkshire   and     the surrounding     area.          ^
    We also believe that the merger is attractive to both parties for the following reasons:
    • the profile of the Hillards stores, averaging approximately 20,000 square feet, is consistent
        with Tesco's store profile;
    m Hillards' recent moves into own label branding and central distribution are consistent with
        those that Tesco has pursued over the last five years. Tesco will be able to implement
        these strategies more effectively in terms of both timing and profit return;
    ^Tesco's trading and marketing policies wil generate higher sales and profits in Hilards'
        s t o r e s;
    • Hilards'business wil enjoy greater long term security in an era when the intensity of
        competition is expected to increase, and
    • Tesco's substantial financial resources wil be available to accelerate the development of
        new superstores in the region.
    In conclusion the merger will give the Hillards business a better and more secure future, to
    the benefit of both Hillards and Tesco shareholders.
The comparative performances of the two companies are dramatically different, as illustrated by the charts below. Tesco has achieved an increase in profits before taxation (excluding net property profits) of 104percent, over the two years ended 28th February,1987, compared to Hillards' increase over the two years ending 2nd May, 1987 of just 27 per cent. Profits before taxation £1 66m Estiii Mled 1964/85 1965/86 1986/87 1984/85 1985/86 1986/87 The Hillards Group The Tesco Group Profits before taxation are stated on the bases set out in paragraph5(k) of Appendix VI. ReasonsforourO ff ers At Tesco, we attach considerable importance to achieving an appropriate market share in Yorkshire where Tesco is currently under-represented. We have an investment strateev place to provide new stores in Yorkshire, the first phase of which includes major develonmenK at Barnsley and York. The acquisition of Hillards will complement this investment, as well giving Tesco additional stores in Hillards' wider trading region. ' The map opposite demonstrates the excellent geographical fit between Hillards' and Tesco's stores. This fit highlights the strategic reasons for acquiring Hillards as a means of expanding our trading presence in Yorkshire and the surrounding area. ^ We also believe that the merger is attractive to both parties for the following reasons: • the profile of the Hillards stores, averaging approximately20,000 square feet, is consistent with Tesco's store profile; m Hillards' recent moves into own label branding and central distribution are consistent with those that Tesco has pursued over the last five years. Tesco will be able to implement these strategies more effectively in terms of both timing and profit return; ^Tesco's trading and marketing policies wil generate higher sales and profits in Hilards' store s; • Hilards'business wil enjoy greater long term security in an era when the intensity of competition is expected to increase, and • Tesco's substantial financial resources wil be available to accelerate the development of new superstores in the region. In conclusion the merger will give the Hillards business a better and more secure future, to the benefit of both Hillards and Tesco shareholders.
Read by machine
The comparative performances of the two companies are dramatically different, as illustrated
by the charts below. Tesco has achieved an increase in profits before taxation (excluding net
property profits) of 104 per cent. over the two years ended 28th February, 1987, compared
to Hillards’ increase over the two years ending 2nd May, 1987 of just 27 per cent.


    Profits before taxation


  £166m
Estimated


                              d      Forecast
    £7.7m           |  £8.5m  |
                    |
                    |
                                |
                                |
                                |
    1984/85             1985/86  |   1986/87    1984/85 1985/86 1986/87
    The Hillards Group                   The Tesco     Group

    Profits before  taxation  are    stated  on the bases set out in paragraph 5(k) of Appendix V1.


   Reasons for our Offers
    At Tesco, we attach considerable importance to achieving an appropriate market share j
    Yorkshire where Tesco is currently under-represented. We have an investment strate in
    place to provide new stores in Yorkshire, the first phase of which includes
                                                         of                                     major develo
         at Barnsley and York. The acquisition     Hillards        will complement this investment,         as     as
         giving Tesco additional        stores in Hillards’    wider trading region.
         The    map  opposite demonstrates     the excellent geographical    fit    between Hillar ds’   and   Tesco’s
        stores. This     fit highlights the strategic reasons   for     acquiring Hillards as a mea ns  of
        our     trading  presence    in Yorkshire and the surrounding     area.                              expanding
    }|   We also believe       that  the merger   is attractive to     both parties for the  following  reasons:
    |   @  _                 of the  Hillards stores, averaging approximately     20,000    square feet, is consistent
                with Tesco’s store      profile;
        ®       Hillards’ recent moves   into     own label branding and     central distribution are consistent  with
    |           those   that Tesco   has pursued     over      the last five years. Tesco will be able to   implement
    |           these   strategies  more effectively  in       terms of both timing and    profit return;
        Tesco’s trading and marketing policies will generate higher sales and profits in Hillards’
        @       es
        stores;
   @ = Hillards’ business will enjoy greater long term security in an era when the intensity of
        competition is expected to increase; and
        @                substantial    financial resources    will  be available   to accelerate the development  of
        new superstores in the region.
    in conclusion, the merger will give the Hillards business a better and more secure future, to
    the benefit of both Hillards and Tesco shareholders.
The comparative performances of the two companies are dramatically different, as illustrated by the charts below. Tesco has achieved an increase in profits before taxation (excluding net property profits) of 104percent. over the two years ended 28th February,1987, compared to Hillards' increase over the two years ending 2nd May, 1987 of just 27 per cent. Profits before taxation £166m Estimated d Forecast £7.7m | £8.5m | | | | | | 1984/85 1985/86 | 1986/87 1984/85 1985/86 1986/87 The Hillards Group The Tesco Group Profits before taxation are stated on the bases set out in paragraph 5(k) of Appendix V1. Reasons for our Offers At Tesco, we attach considerable importance to achieving an appropriate market share j Yorkshire where Tesco is currently under-represented. We have an investment strate in place to provide new stores in Yorkshire, the first phase of which includes of major develo at Barnsley and York. The acquisition Hillards will complement this investment, as as giving Tesco additional stores in Hillards' wider trading region. The map opposite demonstrates the excellent geographical fit between Hillards' and Tesco's stores. This fit highlights the strategic reasons for acquiring Hillards as a means of our trading presence in Yorkshire and the surrounding area. expanding }| We also believe that the merger is attractive to both parties for the following reasons: | @ _ of the Hillards stores, averaging approximately20,000 square feet, is consistent with Tesco's store profile; ® Hillards' recent moves into own label branding and central distribution are consistent with | those that Tesco has pursued over the last five years. Tesco will be able to implement | these strategies more effectively in terms of both timing and profit return; Tesco's trading and marketing policies will generate higher sales and profits in Hillards' @ es stores; @ = Hillards' business will enjoy greater long term security in an era when the intensity of competition is expected to increase; and @ substantial financial resources will be available to accelerate the development of new superstores in the region. in conclusion, the merger will give the Hillards business a better and more secure future, to the benefit of both Hillards and Tesco shareholders.
Read by machine, contrast corrected highest quality of the three
The comparative performances of the two companies are dramatically different, as illustrated
by the charts below. Tesco has achieved an increase in profits before taxation (excluding net
property profits) of 104 per cent. over the two years ended 28th February, 1987, compared
to Hillards’ increase over the two years ending 2nd May, 1987 of just 27 per cent.


    Profits before taxation


  £166m
Estimated


    £7:7m 1 £8.5m | Forecast
        |


    1984/85 1985/86 1986/87    1984/85 1985/86 1986/87
    The Hillards Group        The Tesco Group

    Profits before taxation are stated on the bases set out in paragraph 5(k) of Appendix VI.


           Reasons for      our  Offers
            At Tesco,    we     attach  considerable  importance       to   achieving an appropriate    market   share  j
            Yorkshire   where Tesco is currently under-represented.     We have     an   invest                         nh
            place  to provide    new    stores in Yorkshire, the first phase     of which includes       ment strategy  in
                                                             of                                     maj or developments
            at Barnsley and York. The acquisition     Hillards will     complement this  inves          tment, as well
            giving Tesco additional         stores in Hillards’    wider trading region.                as
            The    map  opposite demonstrates     the excellent geographical     fit     between Hillar ds’ and     Tesco’s
           stores. This     fit highlights  the strategic reasons   for     acquiring Hillards as a  mea ns of
           our     trading  presence     in Yorkshire and the surrounding     area.                               expanding
        |   We also believe        that  the merger   is attractive to     both  parties for the  following reasons:
    |      @  _                  of the  Hillards  stores, averaging approximately     20,000    square feet, is consistent
                   with Tesco’s store       profile;
    |      @   =   Hillards’ recent      moves into   own  label branding and central     distribution are consistent  with
    |                       that Tesco   has   pursued   over      the last five      Tesco will be able to     implement
                                                                       both     timing and profit   return;
    |              those                     effectively   in      terms of     years.
                   these    strategies    more
        ®@         Tesco’s   trading    and  marketing     policies will    generate  higher sales  and profits in Hillards’
                   esc
                   stores;
           ®       Hillards’ business    will  enjoy greater       long  term security in   an era  when the intensity  of
                   competition is   expected     to   increase;    and
           @       __Tesco’s substantial    financial resources    will  be available to    accelerate the development  of
        new superstores in the region.
    in conclusion, the merger will give the Hillards business a better and more secure future, to
    the benefit of both Hillards and Tesco shareholders.
The comparative performances of the two companies are dramatically different, as illustrated by the charts below. Tesco has achieved an increase in profits before taxation (excluding net property profits) of 104percent. over the two years ended 28th February,1987, compared to Hillards' increase over the two years ending 2nd May, 1987 of just 27 per cent. Profits before taxation £166m Estimated £7:7m 1 £8.5m | Forecast | 1984/85 1985/86 1986/87 1984/85 1985/86 1986/87 The Hillards Group The Tesco Group Profits before taxation are stated on the bases set out in paragraph 5(k) of Appendix VI. Reasons for our Offers At Tesco, we attach considerable importance to achieving an appropriate market share j Yorkshire where Tesco is currently under-represented. We have an invest nh place to provide new stores in Yorkshire, the first phase of which includes ment strategy in of maj or developments at Barnsley and York. The acquisition Hillards will complement this investment, as well giving Tesco additional stores in Hillards' wider trading region. as The map opposite demonstrates the excellent geographical fit between Hillards' and Tesco's stores. This fit highlights the strategic reasons for acquiring Hillards as a means of our trading presence in Yorkshire and the surrounding area. expanding | We also believe that the merger is attractive to both parties for the following reasons: | @ _ of the Hillards stores, averaging approximately20,000 square feet, is consistent with Tesco's store profile; | @ = Hillards' recent moves into own label branding and central distribution are consistent with | that Tesco has pursued over the last five Tesco will be able to implement both timing and profit return; | those effectively in terms of years. these strategies more ®@ Tesco's trading and marketing policies will generate higher sales and profits in Hillards' esc stores; ® Hillards' business will enjoy greater long term security in an era when the intensity of competition is expected to increase; and @ __Tesco's substantial financial resources will be available to accelerate the development of new superstores in the region. in conclusion, the merger will give the Hillards business a better and more secure future, to the benefit of both Hillards and Tesco shareholders.