Tesco Offer for Hillards plc page 9 of 15 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
T E S C O  P L C


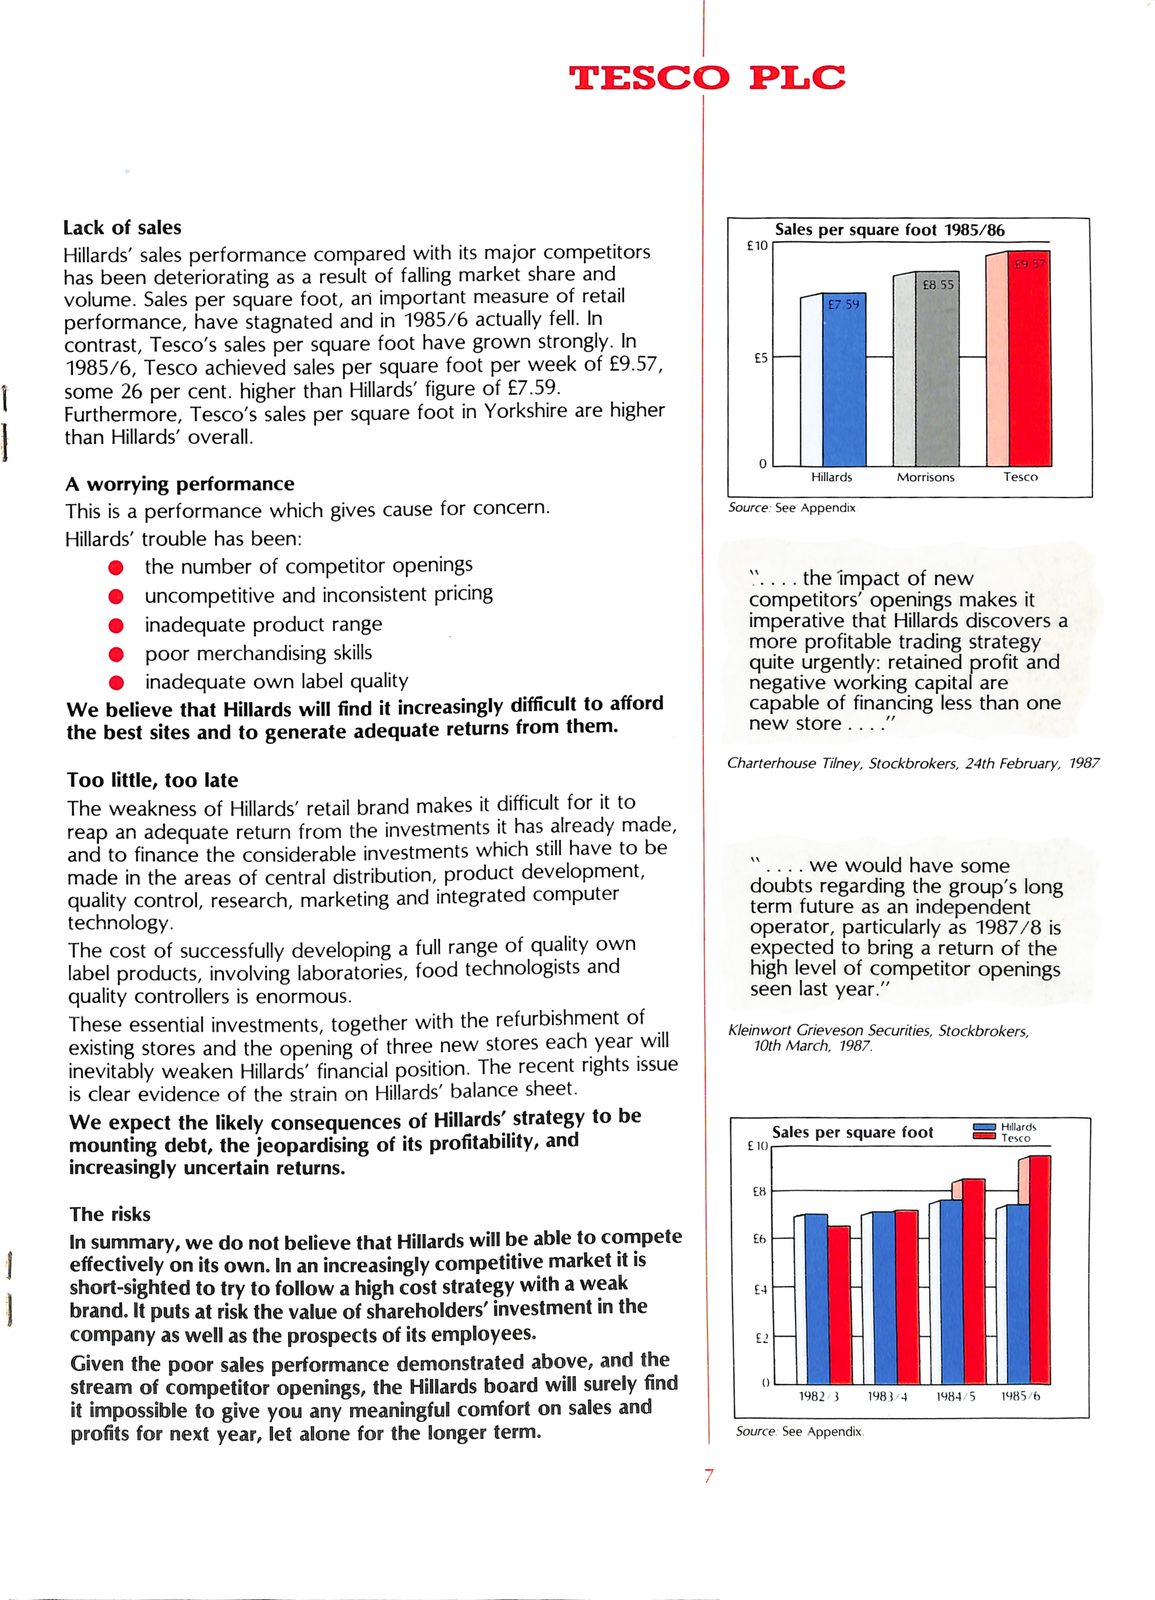
Lack  of  sales                                                                    Sales per     square          foot  1985/86
Hillards' sales performance compared with its major competitors          £1 0
has been deteriorating as a result of failing market share and                                                    £8 55
volume. Sales per square foot, an important measure of retail                          £7     5S
performance, have stagnated and in 1985/6 actually fell. In
contrast, Tesco's sales per square foot have grown strongly. In          £5
1985/6, Tesco achieved sales per square foot per week of £9.57,
some 26 per cent, higher than Hillards' figure of £7.59.
Furthermore, Tesco's sales per square foot in Yorkshire are higher
than  Hillards'    overall.

A worrying     performance                                                             Hillards       M o r r i s o n s            T e s c o
This is a performance which gives cause for concern.                      Source:  See Appendix
Hillards' trouble  has     been;
      • the number of competitor openings                                "....     the     Impact              of    new
      • uncompetitive and inconsistent pricing                           competitors'     openings                 makes               It
      •  inadequate      product  range                                  Imperative     that                   Hillards     discovers     a
                                                                         more          profitable                   trading strategy
      •  poor      merchandising  skills                                 quite         urgently:                   retained profit        and
      •  inadequate own label      quality                               negative      working                   capita       are
We believe that Hillards will find it increasingly difficult to afford   capable       of     financing            less        than       one
the best sites and to generate adequate returns from them.               n e w     s t o r e   .  .   . . "
                                                                        Charterhouse        Tilney,       Stockbrokers,     24th   February, 1987
Too   little, too  late
The weakness of Hillards' retail brand makes it difficult for it to
reap an adequate return from the investments it has already made,
and to finance the considerable investments which still have to be       "     . . . .   w e     w o u l d     h a v e     s o m e
made in the areas of central distribution, product development,          doubts regarding the group's long
quality control, research, marketing and integrated computer             term future as an Independent
technology.                                                              operator,     particularly                as       1987/8         Is
The cost of successfully developing a full range of quality own          expected      to     bring              a return          of     the
label products, involving laboratories, food technologists and           high level of competitor openings
quality   controllers is   enormous.                                     seen last     year."
These essential investments, together with the refurbishment of         Kleinwort         Crieveson   Securities,     Stockbrokers,
existing stores and the opening of three new stores each year will       10th         March,     1987.
inevitably weaken Hillards' financial position. The recent rights issue
is clear evidence of the strain on Hillards' balance sheet.
We expect the likely consequences of Hillards' strategy to be                     Sales  per     square        foot            I   Hrllards
mounting debt, the jeopardising of its profitability, and                £1 0                                                  '   Tcsco
increasingly     uncertain returns.
                                                                         £H
The   risks
In summary, we do not believe that Hillards will be able to compete      £8
effectively on its own. In an increasingly competitive market it is
short-sighted to try to follow a high cost strategy with a weak          £■1
brand. It puts at risk the value of shareholders' investment in the
company as well as the prospects of its employees.                             £7
Given the poor sales performance demonstrated above, and the
stream of competitor openings, the Hillards board will surely find                     1 9 8 2   3   1 9 8 3   A  1 9 8 4   S    1 9 8 5 6
it impossible to give you any meaningful comfort on sales and
profits   for next year, let alone for the    longer term.              Source     See Appendix

                                      7
TESCOPLC Lack of sales Sales per square foot1985/86 Hillards' sales performance compared with its major competitors £1 0 has been deteriorating as a result of failing market share and £8 55 volume. Sales per square foot, an important measure of retail £7 5S performance, have stagnated and in 1985/6actually fell. In contrast, Tesco's sales per square foot have grown strongly. In £5 1985/6,Tesco achieved sales per square foot per week of £9.57, some 26 per cent, higher than Hillards' figure of £7.59. Furthermore, Tesco's sales per square foot in Yorkshire are higher than Hillards' overall. A worrying performance Hillards MorrisonsTesco This is a performance which gives cause for concern. Source: See Appendix Hillards' trouble has been; • the number of competitor openings".... the Impact of new • uncompetitive and inconsistent pricing competitors' openings makes It • inadequate product range Imperative that Hillards discovers a more profitable trading strategy • poor merchandising skills quite urgently: retained profit and • inadequate own label quality negative working capita are We believe that Hillards will find it increasingly difficult to afford capable of financing less than one the best sites and to generate adequate returns from them. newstore . . . . " Charterhouse Tilney, Stockbrokers, 24th February,1987 Too little, too late The weakness of Hillards' retail brand makes it difficult for it to reap an adequate return from the investments it has already made, and to finance the considerable investments which still have to be " . . . . wewouldhavesome made in the areas of central distribution, product development, doubts regarding the group's long quality control, research, marketing and integrated computer term future as an Independent technology. operator, particularly as 1987/8 Is The cost of successfully developing a full range of quality own expected to bring a return of the label products, involving laboratories, food technologists and high level of competitor openings quality controllers is enormous. seen last year." These essential investments, together with the refurbishment of Kleinwort Crieveson Securities, Stockbrokers, existing stores and the opening of three new stores each year will 10th March,1987. inevitably weaken Hillards' financial position. The recent rights issue is clear evidence of the strain on Hillards' balance sheet. We expect the likely consequences of Hillards' strategy to be Sales per square foot I Hrllards mounting debt, the jeopardising of its profitability, and £1 0 ' Tcsco increasingly uncertain returns. £H The risks In summary, we do not believe that Hillards will be able to compete £8 effectively on its own. In an increasingly competitive market it is short-sighted to try to follow a high cost strategy with a weak£■1 brand. It puts at risk the value of shareholders' investment in the company as well as the prospects of its employees. £7 Given the poor sales performance demonstrated above, and the stream of competitor openings, the Hillards board will surely find 198231983A1984S19856 it impossible to give you any meaningful comfort on sales and profits for next year, let alone for the longer term. Source See Appendix 7
Read by machine highest quality of the three
   TESCO PLC


   Lack of sales                                                                                                     Sales per square foot  1985/86
   Hillards’   sales    performance compared            with its major competitors                              £10
   has been deteriorating         as a result     of falling market share and
   volume. Sales     per square      foot, an important        measure     of retail
   performance, have stagnated and in     1985/6               actually    fell. In
   contrast,    Tesco’s sales     per square  foot have        grown    strongly.      In
   1985/6, Tesco achieved sales      per square           foot   per    week of £9.57,                           £5
   some    26    per    cent. higher than Hillards’       figure of £7.59.
   Furthermore, Tesco’s sales           per square       foot in Yorkshire     are     higher.
   than Hillards’     overall.

   A  worrying performance                                                                                           Hillards        Morrisons       Tesco
   This is   a  performance which gives     cause         for  concern.                                     Source: See Appendix
   Hillards’   trouble has been:
                the  number of competitor     openings                                                      ‘        impact of     new
                uncompetitive and inconsistent          pricing                                             competitors’ openings makes it
                inadequate product     range                                                                imperative that Hillards     discovers       a
                    merchandising skills                                                                    more     profitable trading     strategy
                poor                                                                                        quite urgently:               retained profit and
                inadequate    own    label quality                                                          negative working capital                are
   We believe that Hillards          will find it increasingly          difficult to   afford               capable of financing less than                one
   the best sites and         to generate  adequate returns             from them.                          new
                                                                                                            Charterhouse Tilney, Stockbrokers, 24th February, 1987
   Too little, too late
   The weakness of Hillards’ retail     brand makes              it  difficult for  it to
   reap  an     adequate      return from the   investments          it has already                  made,
   and   to  finance the considerable     investments            which still   have    to           be               some
   made    in   the  areas    of central  distribution,     product                   development,                 ....    we would have
                                                                                                            doubts     regarding the group’s long
   quality   control,   research,    marketing    and   integrated computer                                 term     future     as an   independent
   technology.                                        full           of quality     own                     operator,   particularly     as         1987/8 is
   The   cost   of successfully developing       a        range                                             expected     to bring     a     return   of the
   label         products, involving laboratories,    food    technologists     and                         high level of competitor                 openings
   quality   controllers is   enormous.                                                                     seen     last    year.”
   These essential investments,           together    with the       refurbishment of                       Kleinwort Grieveson Securities, Stockbrokers,
   existing    stores   and the opening    of three       new    stores each     year             will           10th March,  1987.
   inevitably   weaken Hillards’ financial     position.         The recent             rights    issue
   is clear    evidence of the strain     on  Hillards’     balance     sheet.
   We    expect the     likely    consequences     of   Hillards’ strategy     to be                                                            ss   Hillards
   mounting debt, the jeopardising of its              profitability,   and                                     £10  Sales per square foot      SS   Tesco
   increasingly     uncertain     returns.
                                                                                                                 £8
   The risks
   In summary, we          do not believe that    Hillards    will be able to     compete                        £6
   effectively  on     its own.   In an increasingly                     competitive market it  Is
   short-sighted     to    try to follow  a high cost strategy          with   a          weak                   £4
   brand. It    puts at risk the value of shareholders’                  investment in the
   company as       well   as the prospects     of its employees.                                                £2
   Given the    poor       sales  performance                   demonstrated above, and the
   stream of competitor openings, the     Hillards board                will     surely               find        0   1982/3     1983/4     1984/5   1985/6
it impossible to give you any meaningful comfort on sales and
   profits for  next    year,    let alone for the longer term.                                             Source:  See Appendix.
TESCO PLC Lack of sales Sales per square foot1985/86 Hillards' sales performance compared with its major competitors£10 has been deteriorating as a result of falling market share and volume. Sales per square foot, an important measure of retail performance, have stagnated and in 1985/6actually fell. In contrast, Tesco's sales per square foot have grown strongly. In 1985/6,Tesco achieved sales per square foot per week of £9.57, £5 some 26 per cent. higher than Hillards' figure of £7.59. Furthermore, Tesco's sales per square foot in Yorkshire are higher. than Hillards' overall. A worrying performance Hillards Morrisons Tesco This is a performance which gives cause for concern. Source: See Appendix Hillards' trouble has been: the number of competitor openings ' impact of new uncompetitive and inconsistent pricing competitors' openings makes it inadequate product range imperative that Hillards discovers a merchandising skills more profitable trading strategy poor quite urgently: retained profit and inadequate own label quality negative working capital are We believe that Hillards will find it increasingly difficult to afford capable of financing less than one the best sites and to generate adequate returns from them. new Charterhouse Tilney, Stockbrokers, 24th February,1987 Too little, too late The weakness of Hillards' retail brand makes it difficult for it to reap an adequate return from the investments it has already made, and to finance the considerable investments which still have to be some made in the areas of central distribution, product development,.... we would have doubts regarding the group's long quality control, research, marketing and integrated computer term future as an independent technology. full of quality own operator, particularly as 1987/8 is The cost of successfully developing a range expected to bring a return of the label products, involving laboratories, food technologists and high level of competitor openings quality controllers is enormous. seen last year." These essential investments, together with the refurbishment of Kleinwort Grieveson Securities, Stockbrokers, existing stores and the opening of three new stores each year will 10th March,1987. inevitably weaken Hillards' financial position. The recent rights issue is clear evidence of the strain on Hillards' balance sheet. We expect the likely consequences of Hillards' strategy to be ss Hillards mounting debt, the jeopardising of its profitability, and £10Sales per square foot SS Tesco increasingly uncertain returns. £8 The risks In summary, we do not believe that Hillards will be able to compete £6 effectively on its own. In an increasingly competitive market it Is short-sighted to try to follow a high cost strategy with a weak £4 brand. It puts at risk the value of shareholders' investment in the company as well as the prospects of its employees. £2 Given the poor sales performance demonstrated above, and the stream of competitor openings, the Hillards board will surely find01982/3 1983/4 1984/5 1985/6 it impossible to give you any meaningful comfort on sales and profits for next year, let alone for the longer term. Source: See Appendix.
Read by machine, contrast corrected
   TESCO PLC


   Lack of sales                                                                                                     Sales per square foot   1985/86
   Hillards’   sales    performance compared            with its major competitors                              £10
   has been deteriorating         as a result     of falling market share and
   volume. Sales     per square      foot, an important        measure     of retail
   performance, have stagnated and in     1985/6               actually    fell. In
   contrast,    Tesco’s sales     per square  foot have        grown    strongly.      In
   1985/6, Tesco achieved sales      per square           foot   per    week of £9.57,                           £5
   some    26    per    cent. higher than Hillards’       figure of £7.59.
   Furthermore, Tesco’s sales           per square       foot in Yorkshire     are     higher.
   than Hillards’     overall.

   A  worrying performance                                                                                           Hillards        Morrisons       Tesco
   This is   a  performance which gives     cause         for  concern.                                     Source: See Appendix
   Hillards’   trouble has been:
                the  number of competitor     openings                                                      \        impact of     new
                uncompetitive and inconsistent          pricing                                             competitors’ openings makes it
                inadequate product     range                                                                imperative that Hillards     discovers       a
                    merchandising skills                                                                    more     profitable trading     strategy
                poor                                                                                        quite urgently:               retained profit and
                inadequate    own    label quality                                                          negative working capital     are
   We believe that Hillards          will find it increasingly          difficult to   afford               capable of financing less than                one
   the best sites and         to generate  adequate returns             from them.                          new
                                                                                                            Charterhouse Tilney, Stockbrokers, 24th February, 1987
   Too little, too late
   The weakness of Hillards’ retail     brand makes              it  difficult for  it to
   reap  an     adequate      return from the   investments          it has already                made,
   and   to  finance the considerable     investments            which still   have    to           be      ww        some
   made    in   the  areas    of central  distribution,     product                   development,                 ....    we would have
                                                                                                            doubts     regarding the group’s long
   quality   control,   research,    marketing    and   integrated computer                                 term     future     as  an  independent
   technology.                                        full           of quality     own                     operator,   particularly     as         1987/8 is
   The   cost   of successfully developing       a        range                                             expected     to bring     a     return   of the
   label         products, involving laboratories,    food    technologists     and                         high level of competitor                 openings
   quality   controllers is   enormous.                                                                     seen     last    year.”
   These essential investments,           together    with the       refurbishment of                       Kleinwort  Grieveson Securities, Stockbrokers,
   existing    stores   and the opening    of three       new    stores each     year             will           10th March,  1987.
   inevitably   weaken Hillards’ financial     position.         The recent             rights    issue
   is clear    evidence of the strain     on  Hillards’     balance     sheet.
   We    expect the     likely    consequences     of   Hillards’ strategy     to be                                 Sales per square foot     ss    Hillards
   mounting debt, the jeopardising of its              profitability,   and                                     £10                                  Tesco
   increasingly     uncertain     returns.
                                                                                                                 £8
   The risks
   In summary, we          do not believe that    Hillards    will be able to     compete                        £6
   effectively  on     its own.   In an increasingly                     competitive market it  Is
   short-sighted     to    try to follow  a high cost strategy          with   a          weak                   f4
   brand. It    puts at risk the value of shareholders’                  investment in the
   company as       well   as the prospects     of its employees.                                                £2
   Given the    poor       sales  performance                   demonstrated above, and the
   stream of competitor openings, the     Hillards board                will     surely               find        0    19823     1983/4     1984/5   1985/6
it impossible to give you any meaningful comfort on sales and
   profits for  next    year,    let alone for the longer term.                                             Source:    See Appendix.
TESCO PLC Lack of sales Sales per square foot1985/86 Hillards' sales performance compared with its major competitors£10 has been deteriorating as a result of falling market share and volume. Sales per square foot, an important measure of retail performance, have stagnated and in 1985/6actually fell. In contrast, Tesco's sales per square foot have grown strongly. In 1985/6,Tesco achieved sales per square foot per week of £9.57, £5 some 26 per cent. higher than Hillards' figure of £7.59. Furthermore, Tesco's sales per square foot in Yorkshire are higher. than Hillards' overall. A worrying performance Hillards Morrisons Tesco This is a performance which gives cause for concern. Source: See Appendix Hillards' trouble has been: the number of competitor openings \ impact of new uncompetitive and inconsistent pricing competitors' openings makes it inadequate product range imperative that Hillards discovers a merchandising skills more profitable trading strategy poor quite urgently: retained profit and inadequate own label quality negative working capital are We believe that Hillards will find it increasingly difficult to afford capable of financing less than one the best sites and to generate adequate returns from them. new Charterhouse Tilney, Stockbrokers, 24th February,1987 Too little, too late The weakness of Hillards' retail brand makes it difficult for it to reap an adequate return from the investments it has already made, and to finance the considerable investments which still have to be ww some made in the areas of central distribution, product development,.... we would have doubts regarding the group's long quality control, research, marketing and integrated computer term future as an independent technology. full of quality own operator, particularly as 1987/8 is The cost of successfully developing a range expected to bring a return of the label products, involving laboratories, food technologists and high level of competitor openings quality controllers is enormous. seen last year." These essential investments, together with the refurbishment of Kleinwort Grieveson Securities, Stockbrokers, existing stores and the opening of three new stores each year will 10th March,1987. inevitably weaken Hillards' financial position. The recent rights issue is clear evidence of the strain on Hillards' balance sheet. We expect the likely consequences of Hillards' strategy to be Sales per square foot ss Hillards mounting debt, the jeopardising of its profitability, and £10Tesco increasingly uncertain returns. £8 The risks In summary, we do not believe that Hillards will be able to compete £6 effectively on its own. In an increasingly competitive market it Is short-sighted to try to follow a high cost strategy with a weak f4 brand. It puts at risk the value of shareholders' investment in the company as well as the prospects of its employees. £2 Given the poor sales performance demonstrated above, and the stream of competitor openings, the Hillards board will surely find019823 1983/4 1984/5 1985/6 it impossible to give you any meaningful comfort on sales and profits for next year, let alone for the longer term. Source: See Appendix.