Revised trading and profit and loss accounts and balance sheets for the years to April 1990 page 2 of 7 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
                                                                                             -        2       -

         3 . 2             ( c o n t ' d )

                           of     the                        improvements               expected      to      arise              from   the               corporate  planning
       a reas (Sc hed u le 5) of ce nt ra l d ist r ib ut io n, ma r ket i ng a nd data
       b a s e d e v e l o p m e n t.
                           The     margins               in          1990        show   a       further                      increase   to      17.80%           as  the
                           c o r p o r a t e         p l a n n i n g        g a i n s   t h e i r           f u l l    ' c o r p o r a t e        p l a n n i n g '  p o t e n t i a l .
         3 . 3           B r a n c h      W a g e s

                           P r o d u c t i v i t y,        i n    a l l   s t o r e s   e x c e p t              A t h e r t o n,       G l o s s o p       a n d    s t o r e s
                           opening              in   1988         to     1990,           has          been forecast                  to        increase          by  2%       in
                           1989          and         1%         in 1990.        The          full           impact        of         networking       savings             is
                           assumed         in                1989.   Wage              costs              are    expected            to  increase              by    5.6%
                           in     April      1988,            5.7%         in   April        1989                and    5.6%            in April      1990.

         3 . 4      B r a n c h            S t a n d i n g      C h a r g e s

                           T h e s e      c o s t s      a r e        e x p e c t e d   t o           i n c u r    i n fl a t i o n      o f   6 %  i n     1 9 8 9   a n d
                           5)^%          in 1990.             The     use       of     vouchers                    is                assumed   to        continue    and      in
                           r e a l     t e r m s     t o      i n c r e a s e   i n    1 9 9 0 .

         3.     5        Ove r r ide rs     a nd              Se m i-Va r ia b le            Ove r heads

                           These          items          are                 expected   to               be   incurred at slightly                    reducing
                           percentage                       levels     of         sales   thus                implying                  that    the  present              levels
                           of                     expenditure,              including   advertising,                      after                        adjustment    for    infl
                           at io n       w i l l           red uce      ove r   t he    next                  two      yea rs .         It      s ho u ld      be    noted
                           however               that         the    large             level          of      advertising               expenditure                    continues
                           t  o b e      a s s u m e d .

         3 . 6           F i x e d  O v e r h e a d s

                           I t     i s   a s s u m e d          t h a t        i n c r e a s e s        i n   r e a l   t e r m s       w i l l    o c c u r i n     fi x e d
                           costs;            as     a     pe rce ntage               of              sa les  t h is     ite m          w i l l       t he refo re    i nc rease
                           f r o m 2 . 0 4 %          i n     1 9 8 8   t o 2 . 1 1 %        i n         1 9 9 0 .

         3 . 7           B a l a n c e       S h e e t

                           Capital           Expenditure                 has    been              assumed                  at    a      rate       which     will     continue
                           t he     patte r n           of        t h ree   new        sto res                ope n i ng         eac h            yea r .    T he    c red ito r/
                           stock         ratio        is      forecast          to     reduce                    from 184            at        April        1988 to   174
                           a t     A p r i l     1 9 9 0 .
                           A     consequence                  of  these         cash            movements                   is          that    borrowings       as   a
                           percentage                of       shareholders funds                                     increase    from           18% at          April       1987
                           t o  26%            a t   A p r i l ,  1990;         t h e        t o t a l           a t A p r i l   1990             b e i n g   a p p r o x
                           i m a t e l y     £ 2 0 m .

                                                                                                                                                          A P P E N D I X      A

                                                 SAL ES         VOL UM E        FO Pt ECASTS                     TO    A P R IL      1990

   All Figures in January 1987 £s.
RTidinH                      Atherton/Clossop
                               O t h e r                 N e w                   S . S . L . B . *    B a s i c                    S t o r e s     T o t a l         V o l u m e
         n Q « 7               3             6 5 6 , 6 4 8                     1 6 , 2 8 1 , 2 0 0       8 7 , 0 9 0 , 7 9 2                               1 0 7 , 0 2 8 , 6 4 0
   A p r i l           i   u o '         ^
   A  n          1 4    7 9 1 , 3 0 0                         1 6 , 4 7 5 , 8 0 0                       8 5      , 9 3 1 , 4 0 0                           1 1 7 , 1 9 8 , 5 0 0
p r i l  l          u o o                >
   %            m o v e m e n t                o n    ^         3 0 4 . 5 %             +               _ l i 2 %           -        l  i     3 %    +              9 . 5 %
   previous          year
      11             1989      27,456,600 16,640,558                                                                                83,098,800                       127,195,158
   % m o v e m e n t                     o n         8 5 . 6 % _ _                  +        _ i i O %                  -     3 _ ^ 3 %              +              8 . 5 %
   p r e v i o u s  y e a r
   April 1990 40,958,400 16,723,761 81,964,800 139,646,961
   %            m o v e m e n t              o n                + 4 9 . 2 % +                         0  .   5   %        -             1 . 4 %                   + 9 . 8 %
   previous          yea F
         S borough Scunthorpe (incl. Petrol and Cafe), Lincoln and Brownhills
         (incl .          petrol) .
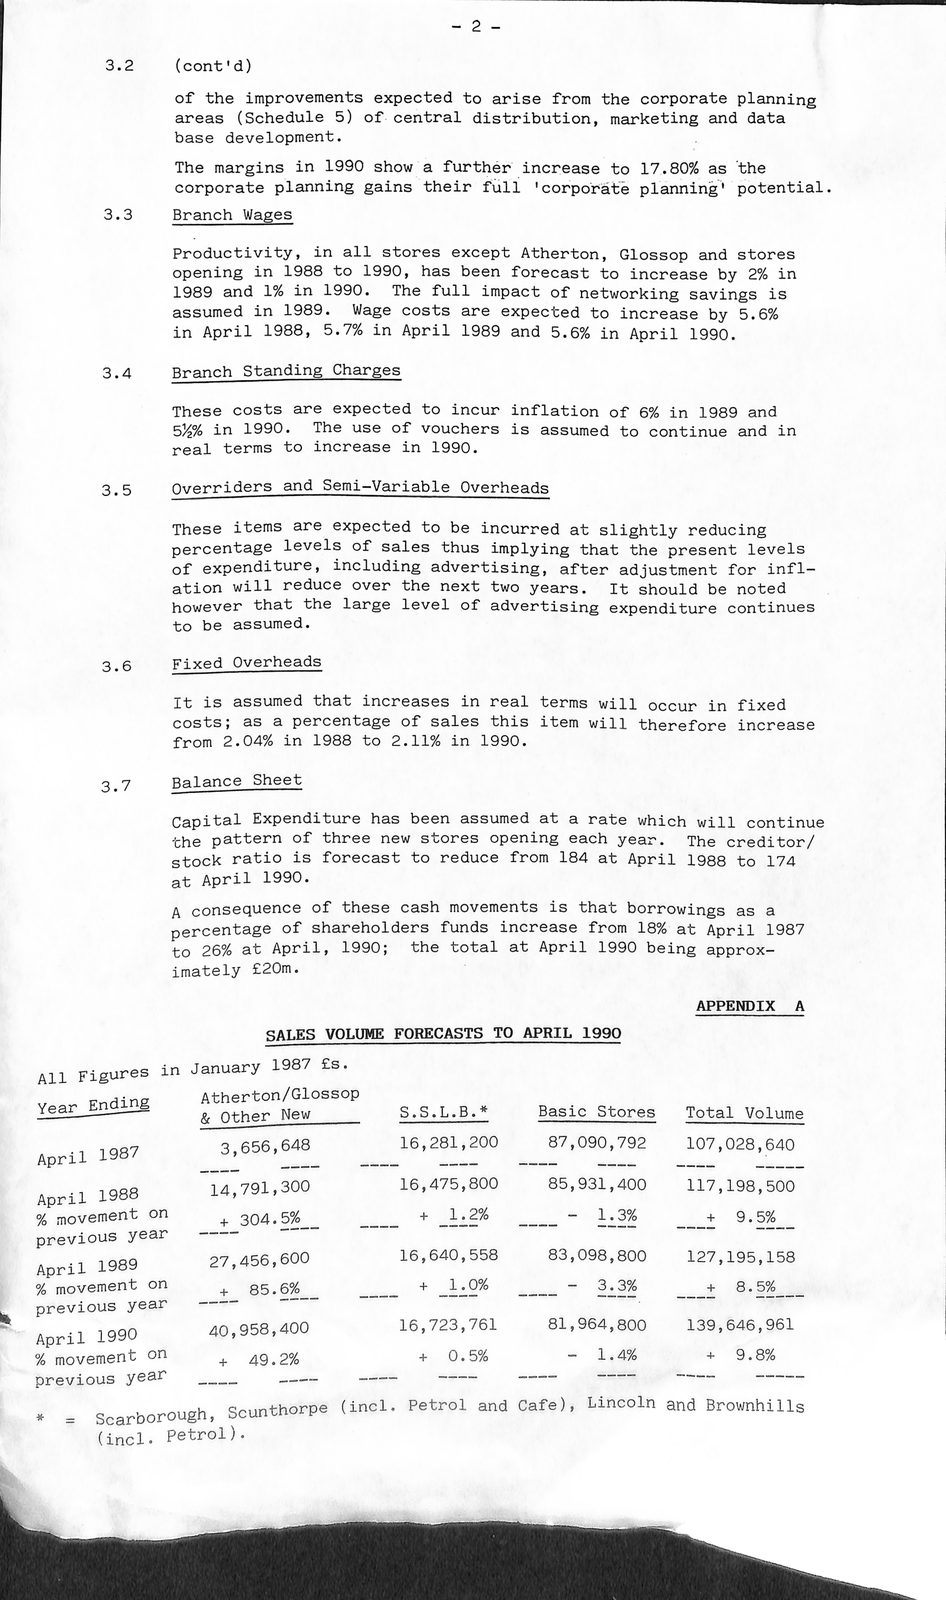
- 2 - 3 . 2 ( cont ' d ) of the improvements expected to arise from the corporate planning areas (Sc hed u le 5) of ce nt ra l d ist r ib ut io n, market i ng a nd data basedevelopmen t. The margins in 1990show a further increase to 17.80% as the corporateplanninggainstheirfull ' corporateplanning ' potential . 3 . 3BranchWages Productivity, inallstoresexceptAtherto n, Glossopandstores opening in1988to 1990, has been forecast to increase by 2% in 1989 and 1% in 1990. The full impact of networking savings is assumed in 1989.Wage costs are expected to increase by 5.6% in April1988,5.7% in April1989 and 5.6% in April1990. 3 . 4BranchStandingCharges Thesecostsareexpectedtoincurin fl ationof6 % in1989and 5)^% in 1990. The use of vouchers is assumed to continue and in realtermstoincreasein1990 . 3. 5Over r ide rs a nd Se m i-Va r ia b le Overheads These items are expected to be incurred at slightly reducing percentage levels of sales thus implying that the present levels of expenditure, including advertising, after adjustment for infl at io nwill reduce overt he next two yea rs . It s ho u ld be noted however that the large level of advertising expenditure continues tobeassumed . 3 . 6FixedOverheads Itisassumedthatincreasesinrealtermswilloccurin fixed costs; as a percentage of sa les t h is ite mwillt he refo re increase from2 . 0 4 % in1988to2 . 1 1 % in1990 . 3 . 7BalanceSheet Capital Expenditure has been assumed at a rate which will continue t he pattern of three new stores open i ng each yea r . T he c red ito r/ stock ratio is forecast to reduce from184 at April1988 to 174 atApril1990 . A consequence of these cash movements is that borrowings as a percentage of shareholders funds increase from18% at April1987 t o 26% atApril , 1990; thetotalatApril 1990 beingapprox imately£20m . APPENDIXA SAL ES VOL UM E FO Pt ECASTS TO APRIL1990 All Figures in January1987 £s. RTidinH Atherton/Clossop OtherNewS . S . L . B . * BasicStoresTotalVolume n Q « 73656 , 64816 , 281 , 20087 , 090 , 792107 , 028 , 640 Apriliuo ' ^ An14791 , 30016 , 475 , 80085 , 931 , 400117 , 198 , 500 prilluoo > % movementon ^ 304 . 5 % + _ li2 % - li3 % + 9 . 5 % previous year 11 1989 27,456,600 16,640,558 83,098,800 127,195,158 % movementon85 . 6 % _ _ + _ iiO % - 3 _ ^ 3 % + 8 . 5 % previousyear April199040,958,400 16,723,761 81,964,800 139,646,961 % movementon + 4 9 . 2 % + 0 . 5 % - 1 . 4 % + 9 . 8 % previous yea F S borough Scunthorpe (incl. Petrol and Cafe), Lincoln and Brownhills (incl . petrol) .
Read by machine
      3.2       (cont'd)

                of                                    expected      to  arise          from  the     corporate               planning
                areas        chedule                 of. central               distribution      marketing
                                                                                          »             ti         and          data

    The margins in 1990 show a further increase to 17.80% as the
                corporate        planning              gains  their     full                         planning'               potential.
      3.3        Branch      Wages

                 Productivity,            in    all     stores except           Atherton,        Glossop                and  stor
                 opening       in    1988       to   1990,     has  been    forecast                                     by     2%  in
                 1989    and    1%    in        1990.    The      full  impact    of      networking ee                         oe
                 assumed       in    1989.         Wage      costs  are  expected         to     increase          b     ale
                 in   April     1988,           5.7%  in     April  1989 and      5.6%     in       April               hes

      3.4        Branch      Standing           Charges

                                                expected      to   incur    inflation            of  6%     in    1989          and
                 5%%     in  1990.        The      use    of  vouchers        is  assumed        to              continu        d   i
                 real       terms    to     increase      in      1990.

                 Overriders          and             Semi-Variable  Overheads

    These items are expected to be incurred at slightly reducin
                            ee       ae            of   sales      thus implying          that      the     present
                 of   expenditure,              including         advertising,       after                    adjustment     f     infl
                 ation      will     reduce        over   the      next two      years.          It  es
                 however    that        the     large        level  of  advertising                              ure     continues     |
                 to   be    assumed.

                 Fixed      Overheads

                 It   is    assumed       that           increases  in      real  terms     will            occur  in        fixed
                 costs;      aS    a  percentage          of      sales     this  item     wi                                  i
                 from       2.04%    in     1988     to  2.11%     in      1990.

      ot,        Balance    Sheet

                 Capital    Expenditure               has     been  assumed       at  a rate         whichi        wi                j
                 the         pattern  of        three   new   stores    opening       each              year.                      7a
                 stock      ratio     is        forecast     to   reduce from        184 at      April           1988        t
                 at   April     1990.
                 A  consequence           of    these     cash     movements     is       that                  borrowings   as    a
                 percentage          of     shareholders          funds  increase       from         18%       at  April           1987
                 to   26%    at   April,        1990;        the   total      at  April     1990            being  approx
                 imately    £20m.

                                                                                                                  APPENDIX            A

                                SALES           VOLUME   FORECASTS      TO      APRIL     1990

All  Figures  1  n  January      1987           £s.
Year  Ending          Atherton/Glossop                    SS.
                      &  Other       New                                          Basic     Stores               Total          Volume
                         3,656,648                        16,281,200             87,090,792                      107,028,640
                      14,791,300                          16,475,800             85,931,400
                                          __                                              ee
                         +            304.5%       a                                                               +         9.5%
                      27,    456 ,   600                  16,640,558             83,098,800                      127,195,158
                                                             *                        >                            +         8.5%
                                                   ce
previous year
April 1990            40,958,        400                  16,723,761             81,964,800                      139,646,961
% movement  on           +   49.2%                           +    0.5%                -     1.4%                   4         9.8%
previous year
*     Searpor   ough,      Scunthorpe           (incl.     Petrol       and Cafe),        Lincoln        and       Brownhills
    (incl.     Petrol).
3.2(cont'd) of expected to arise from the corporate planning areas chedule of. central distribution marketing » ti and data The margins in 1990show a further increase to 17.80% as the corporate planning gains their full planning' potential. 3.3Branch Wages Productivity, in all stores except Atherton, Glossop and stor opening in1988to 1990, has been forecast by 2% in 1989 and 1% in 1990. The full impact of networking ee oe assumed in 1989.Wage costs are expected to increase b ale in April1988,5.7% in April1989 and 5.6% in April hes 3.4Branch Standing Charges expected to incur inflation of 6% in 1989 and 5%% in 1990. The use of vouchers is assumed to continu d i real terms to increase in 1990. Overriders and Semi-Variable Overheads These items are expected to be incurred at slightly reducin ee ae of sales thus implying that the present of expenditure, including advertising, after adjustment f infl ation will reduce over the next two years. It es however that the large level of advertising ure continues | to be assumed. Fixed Overheads It is assumed that increases in real terms will occur in fixed costs; aS a percentage of sales this item wi i from2.04% in1988to 2.11% in 1990. ot, Balance Sheet Capital Expenditure has been assumed at a rate whichi wi j the pattern of three new stores opening each year. 7a stock ratio is forecast to reduce from184 at April1988 t at April1990. A consequence of these cash movements is that borrowings as a percentage of shareholders funds increase from18% at April1987 to 26% at April,1990; the total at April1990 being approx imately £20m. APPENDIX A SALES VOLUME FORECASTS TO APRIL1990 All Figures 1 n January1987 £s. Year Ending Atherton/Glossop SS. & Other New Basic Stores Total Volume 3,656,648 16,281,200 87,090,792 107,028,640 14,791,300 16,475,800 85,931,400 __ ee + 304.5% a + 9.5% 27, 456 , 600 16,640,558 83,098,800 127,195,158 * > + 8.5% ce previous year April199040,958, 400 16,723,761 81,964,800 139,646,961 % movement on + 49.2% + 0.5% - 1.4% 4 9.8% previous year * Searpor ough, Scunthorpe (incl. Petrol and Cafe), Lincoln and Brownhills (incl. Petrol).
Read by machine, contrast corrected highest quality of the three
      3.2         (cont'd)

                 dan                                expected       to  arise        from  the        corporate             planning
                       as      chedule              of. central             distribution »      marketingi     and          data

                 The    margins         in      1990  show    a  further       increase         to   17.80%           as   the
                 corporate       planning              gains  their    full                          planning'             potential
      3.3         Branch     Wages

                  Productivity,             in  all   stores except            Atherton,            Glossop           and   st
                  opening      in      1988     to   1990,    has  been    forecast      to                             b        in
                 1989      and  1%      in      1990.   The     full   impact    of    networkin savin                         ‘is
                  assumed   in         1989.       Wage     costs  are  expected        to           incres
                 in   April     1988,           5.7%  in    April  1989  and     5.6%     in

      3.4         Branch     Standing           Charges

                                                expected      to  incur    inflation            of   6%  in   1989          and
                  5%%    in  1990.          The    use    of  vouchers       is  assumed          to   conti                   d i
                  real     terms       to   increase     in     1990.

      3.5         Overriders           and          Semi-Variable  Overheads

    These items are expected to be incurred at slightly reducin
                  percentage           levers      of  sales      thus implying        that         the                     ame
    of expenditure, including advertising, after adjustment f
                  ation     will       reduce      over  the      next two      years.          It   hes     eis       e   no      =
                                                large                                                                           e
                  however   that          the               level  of  advertising              ex  penditure              continues     |
                  to  be    assumed.

                  Fixed     Overheads

                 It   is    assumed         that        increases  in      real  terms     will         occur  in          fixed
                  costs;     aS      a  percentage       of      sales     this  item     wi                               i
                                                                                                                                 eae
                  from     2.04%       in   1988     to  2.11%    in   1990.

                  Balance   Sheet

                  Capital   Expenditure             has      been  assumed       at  a       rat  e  which   Thewi
                  tne          pattern  of      three   new   stores   opening       each         year.                    reditor/
                  stock     ratio       is      forecast     to  reduce  from       184       at    April    1988          to   174
                  at  April     1990.
                  A  consequence            of  these    cash     movements     is          that              borrowings   as   a
                  percentage     of         shareholders         funds  increase        from         18%   at  April            1987
                  to  26%    at   April,        1990;        the  total      at  April     1990         being  approx                    |
                  imately   £20m.

                                                                                                              APPENDIX             A

                                 SALES          VOLUME   FORECASTS     TO      APRIL   1990

All  Figures   1  n  January     1987           £s.
Year Ending           Atherton/Glossop                                           Basic
                      &  Other     New                                                   Stores              Total          Volume
                         3,656,648                       16,281,200             87,090,792                   107,028,640

                                                                                85,931,400                                     9
                      14,791,300                         16,475,800                                          117,198,500
                                          __                                ae
                         +   304.5%                a!                                                          +           9.5%
                             456       600               16,640,558             83,098,           800        127.195.158
                      27,        ,                                                                                 ?           9
                                                                                                               +           8.5%
previous year
April 1990            40,958,400                         16,723,761             81,964,800                   139,646,961
% movement  on           +   49.2%                           +   0.5%               -     1.4%                 4           9.8%
previous year
*     Searoor   ough,      Scunthorpe           (incl.     Petrol      and  Cafe),      Lincoln          and   Brownhills
    (incl.     Petrol).
3.2(cont'd) dan expected to arise from the corporate planning as chedule of. central distribution » marketingi and data The margins in 1990show a further increase to 17.80% as the corporate planning gains their full planning' potential 3.3Branch Wages Productivity, in all stores except Atherton, Glossop and st opening in1988to 1990, has been forecast to b in 1989 and 1% in 1990. The full impact of networkin savin 'is assumed in 1989.Wage costs are expected to incres in April1988,5.7% in April1989 and 5.6% in 3.4Branch Standing Charges expected to incur inflation of 6% in 1989 and 5%% in 1990. The use of vouchers is assumed to conti d i real terms to increase in 1990. 3.5 Overriders and Semi-Variable Overheads These items are expected to be incurred at slightly reducin percentage levers of sales thus implying that the ame of expenditure, including advertising, after adjustment f ation will reduce over the next two years. It hes eis e no = large e however that the level of advertising expenditure continues | to be assumed. Fixed Overheads It is assumed that increases in real terms will occur in fixed costs; aS a percentage of sales this item wi i eae from2.04% in1988to 2.11% in 1990. Balance Sheet Capital Expenditure has been assumed at a rat e which Thewi tne pattern of three new stores opening each year. reditor/ stock ratio is forecast to reduce from184 at April1988 to 174 at April1990. A consequence of these cash movements is that borrowings as a percentage of shareholders funds increase from18% at April1987 to 26% at April,1990; the total at April1990 being approx | imately £20m. APPENDIX A SALES VOLUME FORECASTS TO APRIL1990 All Figures 1 n January1987 £s. Year Ending Atherton/Glossop Basic & Other New Stores Total Volume 3,656,648 16,281,200 87,090,792 107,028,640 85,931,400 9 14,791,300 16,475,800 117,198,500 __ ae + 304.5% a! + 9.5% 456 600 16,640,558 83,098, 800 127.195.158 27, , ? 9 + 8.5% previous year April199040,958,400 16,723,761 81,964,800 139,646,961 % movement on + 49.2% + 0.5% - 1.4% 4 9.8% previous year * Searoor ough, Scunthorpe (incl. Petrol and Cafe), Lincoln and Brownhills (incl. Petrol).