Checklist of possible comments for use at press/analysts meeting 27/01/1986 page 3 of 4 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
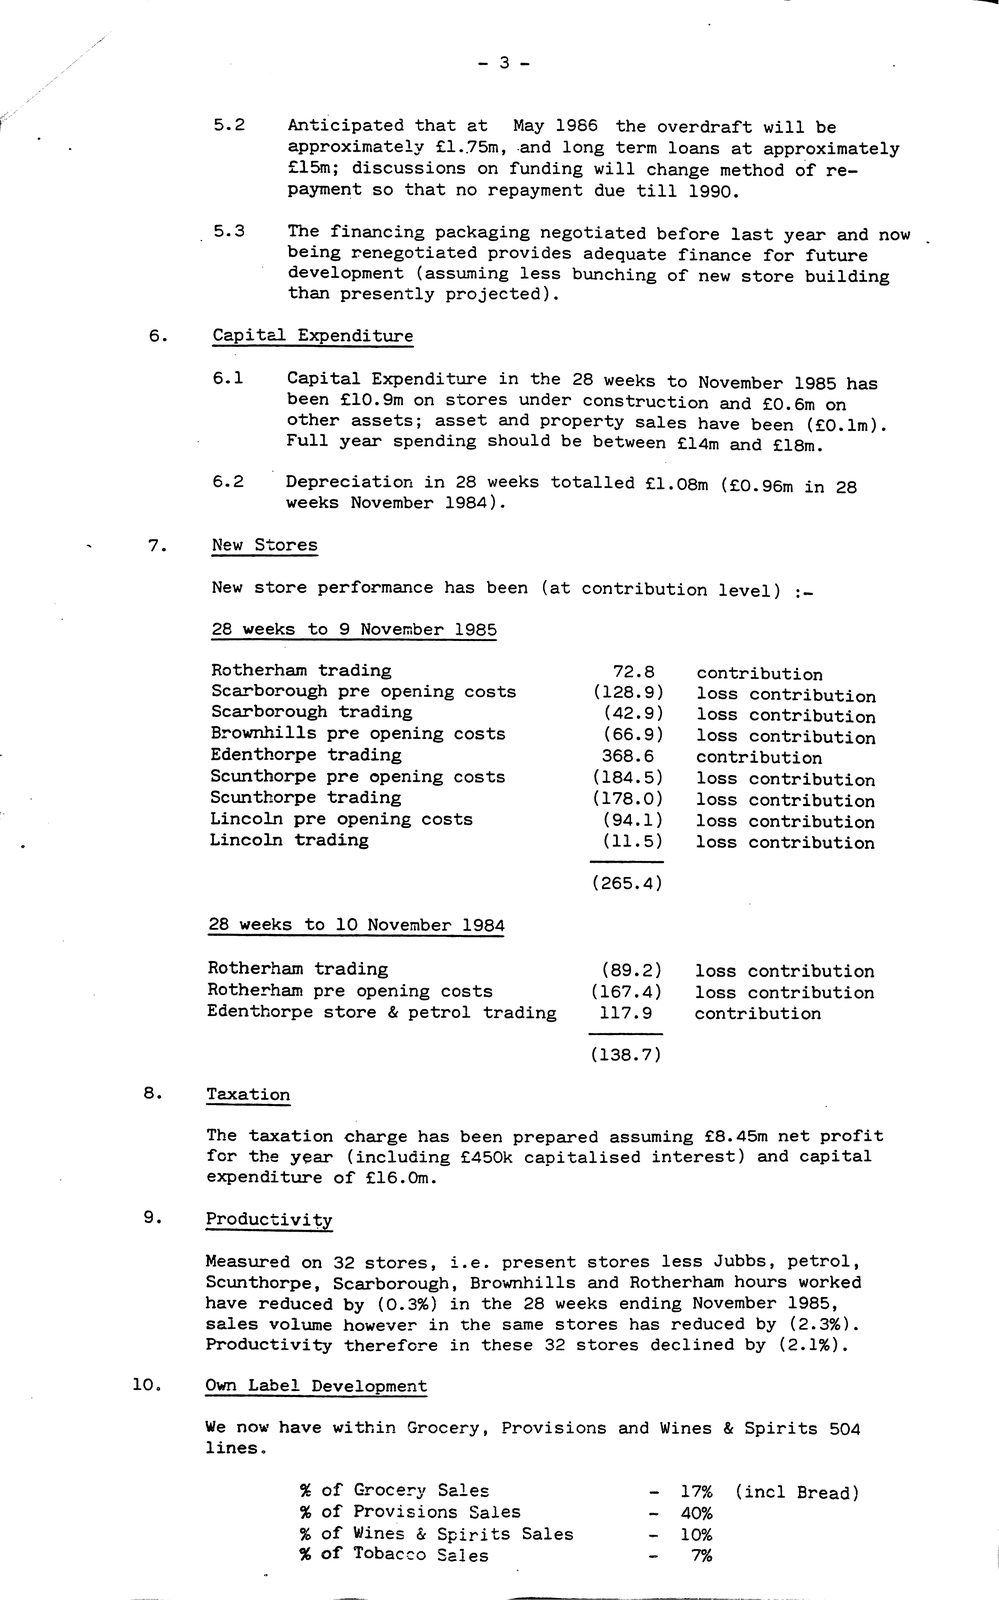
Text already in the scan highest quality of the three
                                         -    3   -

     5.2        Anticipated     that     at      May  1986   the      overdraft      will   be
                approximately          £1..75m,   and  long  term          loans at  approximately
                £15m;  discussions       on        funding  will  change        method     of re
                payment     so that  no          repayment  due  till         1990.

     5.3        The  financing     packaging negotiated before                   last    year   and now
                being  renegotiated            provides    adequate        finance   for   future
                development           (assuming   less  bunching           of new store building
                than  presently     projected) .

     Capital     Expenditure

     6 .1       Capital         Expenditure    in  the  28                 to  November weeks 1985 has
                been  £10.9m   on        stores   under    construction         and  £0.6m    on
                other  assets;        asset    and property      sales         have  been  (£0.1m).
                Full  year     spending          should be  between        £14m     and £18m.

     6.2        Depreciation     in  28     weeks     totalled    £1.08m        (£0.96m    in 28
                weeks    November        1984).

     New    Stores

     New        store performance                   (at                         level) has been contribution

     28    weeks to 9      November  1985

     Rotherham      trading                                 72.8               contribution
     Scarborough pre       opening costs                    (128.9)            loss  contribution
     Scarborough      trading                                    (42.9)        loss  contribution
     Brownhills pre         opening       costs                  (66.9)        loss  contribution
     Edenthorpe trading                            368.6                      contribution
     Scunthorpe pre opening               costs             (184.5)            loss  contribution
     Scunthorpe trading                                     (178.0)            loss  contribution
     Lincoln     pre opening     costs                           (94.1)        loss  contribution
     Lincoln     trading                                        (1 1.5)       loss   contribution

                                                            (265 .4)

      28   weeks to 10 November            1984

      Rotherham  trading                                    (89.2)            loss   contribution
      Rotherham  pre  opening     costs                     (167.4)           loss   contribution
      Edenthorpe store     & petrol      trading  1 17.9                      contribution

                                                            (138 .7)

8 .   Taxation

      The    taxation  charge    has been prepared          assuming           £8.45m   net profit
      for   the  year  (including £450k     capitalised           interest)            and capital
      expenditure    of £16.Om.

 9.   Productivity

      Measured   on  32    stores,    i .e.      present   stores     less      Jubbs,     petrol,
      Scunthorpe,    Scarborough,             Brownhills   and  Rotherham            hours  worked
      have    reduced  by   (0.3%)   in    the   28   weeks  ending           November     1985,
      sales    volume  however   in     the    same   stores    has        reduced   by    (2.3%).
      Productivity therefore in these 32 stores declined by (2.1%).

10.   Own Label  Development

      We now have    within        Grocery,    Provisions    and      Wines      & Spirits     504
      lines.

                 % of (Srocery        Sales                       -        17%      (incl  Bread)
                 % of Provisions        Sales                     -        40%
                 % of Wines & Spirits              Sales          -        10%
                 % of Tobacco         Sales                                   7%
- 3 - 5.2Anticipated that at May 1986 the overdraft will be approximately £1..75m, and long term loans at approximately £15m; discussions on funding will change method of re payment so that no repayment due till1990. 5.3 The financing packaging negotiated before last year and now being renegotiated provides adequate finance for future development (assuming less bunching of new store building than presently projected) . Capital Expenditure 6 .1 Capital Expenditure in the 28 to November weeks1985 has been £10.9m on stores under construction and £0.6m on other assets; asset and property sales have been (£0.1m). Full year spending should be between £14m and £18m. 6.2Depreciation in 28 weeks totalled £1.08m (£0.96m in 28 weeks November1984). New Stores New store performance (at level) has been contribution 28 weeks to 9November1985 Rotherham trading72.8 contribution Scarborough pre opening costs(128.9) loss contribution Scarborough trading(42.9) loss contribution Brownhills pre opening costs(66.9) loss contribution Edenthorpe trading368.6 contribution Scunthorpe pre opening costs(184.5) loss contribution Scunthorpe trading(178.0) loss contribution Lincoln pre opening costs(94.1) loss contribution Lincoln trading(11.5) loss contribution (265 .4) 28 weeks to 10November1984 Rotherham trading(89.2) loss contribution Rotherham pre opening costs(167.4) loss contribution Edenthorpe store & petrol trading117.9 contribution (138 .7) 8 . Taxation The taxation charge has been prepared assuming £8.45m net profit for the year (including £450k capitalised interest) and capital expenditure of £16.Om. 9. Productivity Measured on 32 stores, i .e. present stores less Jubbs, petrol, Scunthorpe, Scarborough, Brownhills and Rotherham hours worked have reduced by (0.3%) in the 28 weeks ending November1985, sales volume however in the same stores has reduced by (2.3%). Productivity therefore in these 32 stores declined by (2.1%). 10. Own Label Development We now have within Grocery, Provisions and Wines &Spirits504 lines. % of (Srocery Sales-17% (incl Bread) % of Provisions Sales-40% % of Wines & Spirits Sales-10% % of Tobacco Sales 7%
Read by machine
-3-


     5.2         ticipated     that   at       May  1986  the     overdraft      will  be
    approximately £1.75m, and long term loans at approximately
              £15m;     discussions       on  funding            change will method of re-
              payment      so  that     no  repayment due till 1990.

              The    financing     packaging     negotiated       before    last   year  and now
              being           renegotiated  provides    adequate     finance     for  future
    development (assuming less bunching of new store building
    than presently projected).

     Capitel    Expenditure

     6.1      Capital      Expenditure       in  the  28 weeks      to  November     1985 has
              been    £10.9m    on  stores      under      construction     and  £0.6m   on
    other assets; asset and property sales have been (£0.1m).
              Full    year        spending  should   be between     £14m    and  £18m.

     6.2      Depreciation       in     28  weeks  totalled      £1.08m     (£0.96m   in  28
              weeks       November  1984).

     New    Stores

     New   store       performance  has     been  (at      contribution     level)   :-

     28 weeks     to  9    November  1985

     Rotherham    trading                                 72.8          contribution
     Scarborough      pre  opening    costs                 (128.9)     loss  contribution
     Scarborough      trading                                (42.9)     loss  contribution
     Brownhills     pre     opening  costs                   (66.9)     loss  contribution
     Edenthorpe     trading                              368.6          contribution
     Scunthorpe     pre     opening  costs                  (184.5)     loss  contribution
     Scunthorpe     trading                                 (178.0)     loss  contribution
     Lincoln    pre   opening    costs                       (94.1)     loss  contribution
     Lincoln    trading                                      (11.5)     loss  contribution

                                                            (265.4)

     28   weeks  to   10   November   1984

     Rotherham    trading                                    (89.2)     loss  contribution
     Rotherham    pre    opening   costs                    (167.4)     loss  contribution
      Edenthorpe    store    & petrol     trading 117.9                 contribution

                                                        (138.7)

      Taxation

      The    taxation  charge    has  been     prepared   assuming      £8.45m     net profit
      for the    year  (including     £450k     capitalised     interest)       and  capital
      expenditure     of £16.0m.

      Productivity

   Measured on 32 stores, i.e. present stores less Jubbs, petrol,
      Scunthorpe,     Scarborough,      Brownhills      and Rotherham       hours     worked
      have    reduced  by  (0.3%)    in    the  28  weeks   ending     November    1985,
      sales    volume  however    in  the     same  stores  has     reduced     by  (2.3%).
      Productivity     therefore     in    these   32  stores       declined by    (2.1%).

10.   Own  Label      Development

      We  now have    within   Grocery,      Provisions     and    Wines   & Spirits     504
      lines.

                % of    Grocery    Sales                        -      17%   (incl   Bread)
                % of    Provisions      Sales                   -     40%
                %   of  Wines   &  Spirits      Sales           -     10%
                % of    Tobacco    Seies                        -      7%
-3- 5.2 ticipated that at May 1986 the overdraft will be approximately £1.75m, and long term loans at approximately £15m; discussions on funding change will method of re- payment so that no repayment due till1990. The financing packaging negotiated before last year and now being renegotiated provides adequate finance for future development (assuming less bunching of new store building than presently projected). Capitel Expenditure 6.1Capital Expenditure in the 28 weeks to November1985 has been £10.9m on stores under construction and £0.6m on other assets; asset and property sales have been (£0.1m). Full year spending should be between £14m and £18m. 6.2Depreciation in 28 weeks totalled £1.08m (£0.96m in 28 weeks November1984). New Stores New store performance has been (at contribution level) :- 28 weeks to 9November1985 Rotherham trading72.8 contribution Scarborough pre opening costs(128.9) loss contribution Scarborough trading(42.9) loss contribution Brownhills pre opening costs(66.9) loss contribution Edenthorpe trading368.6 contribution Scunthorpe pre opening costs(184.5) loss contribution Scunthorpe trading(178.0) loss contribution Lincoln pre opening costs(94.1) loss contribution Lincoln trading(11.5) loss contribution (265.4) 28 weeks to 10November1984 Rotherham trading(89.2) loss contribution Rotherham pre opening costs(167.4) loss contribution Edenthorpe store & petrol trading117.9 contribution (138.7) Taxation The taxation charge has been prepared assuming £8.45m net profit for the year (including £450k capitalised interest) and capital expenditure of £16.0m. Productivity Measured on 32 stores, i.e. present stores less Jubbs, petrol, Scunthorpe, Scarborough, Brownhills and Rotherham hours worked have reduced by (0.3%) in the 28 weeks ending November1985, sales volume however in the same stores has reduced by (2.3%). Productivity therefore in these 32 stores declined by (2.1%). 10. Own Label Development We now have within Grocery, Provisions and Wines &Spirits504 lines. % of Grocery Sales-17% (incl Bread) % of Provisions Sales-40% % of Wines & Spirits Sales-10% % of Tobacco Seies - 7%
Read by machine, contrast corrected
-3-


     5.2         ticipated     that   at       May  1986  the     overdraft      will  be
    approximately £1.75m, and long term loans at approximately
              £15m;     discussions       on  funding            change will method of re-
              payment      so  that     no  repayment due till 1990.

              The    financing     packaging     negotiated       before    last   year  and now
              being           renegotiated  provides    adequate     finance     for  future
    development (assuming less bunching of new store building
    than presently projected).

     Capitel    Expenditure

     6.1      Capital      Expenditure       in  the  28 weeks      to  November     1985 has
              been    £10.9m    on  stores      under      construction     and  £0.6m   on
    other assets; asset and property sales have been (£0.1m).
              Full    year        spending  should   be between     £14m    and  £18m.

     6.2      Depreciation       in     28  weeks  totalled      £1.08m     (£0.96m   in  28
              weeks       November  1984).

     New    Stores

     New   store       performance  has     been  (at      contribution     level)   :-

     28 weeks     to  9    November  1985

     Rotherham    trading                                 72.8          contribution
     Scarborough      pre  opening    costs                 (128.9)     loss  contribution
     Scarborough      trading                                (42.9)     loss  contribution
     Brownhills     pre     opening  costs                   (66.9)     loss  contribution
     Edenthorpe     trading                              368.6          contribution
     Scunthorpe     pre     opening  costs                  (184.5)     loss  contribution
     Scunthorpe     trading                                 (178.0)     loss  contribution
     Lincoln    pre   opening    costs                       (94.1)     loss  contribution
     Lincoln    trading                                      (11.5)     loss  contribution

                                                            (265.4)

     28   weeks  to   10   November   1984

     Rotherham    trading                                    (89.2)     loss  contribution
     Rotherham    pre    opening   costs                    (167.4)     loss  contribution
      Edenthorpe    store    & petrol     trading 117.9                 contribution

                                                        (138.7)

      Taxation

      The    taxation  charge    has  been     prepared   assuming      £8.45m     net profit
      for the    year  (including     £450k     capitalised     interest)       and  capital
      expenditure     of £16.0m.

      Productivity

   Measured on 32 stores, i.e. present stores less Jubbs, petrol,
      Scunthorpe,     Scarborough,      Brownhills      and Rotherham       hours     worked
      have    reduced  by  (0.3%)    in    the  28  weeks   ending     November    1985,
      sales    volume  however    in  the     same  stores  has     reduced     by  (2.3%).
      Productivity     therefore     in    these   32  stores       declined by    (2.1%).

10.   Own  Label      Development

      We  now have    within   Grocery,      Provisions     and    Wines   & Spirits     504
      lines.

                % of    Grocery    Sales                        -      17%   (incl   Bread)
                % of    Provisions      Sales                   -     40%
                %   of  Wines   &  Spirits      Sales           -     10%
                % of    Tobacco    Seies                        -      7%
-3- 5.2 ticipated that at May 1986 the overdraft will be approximately £1.75m, and long term loans at approximately £15m; discussions on funding change will method of re- payment so that no repayment due till1990. The financing packaging negotiated before last year and now being renegotiated provides adequate finance for future development (assuming less bunching of new store building than presently projected). Capitel Expenditure 6.1Capital Expenditure in the 28 weeks to November1985 has been £10.9m on stores under construction and £0.6m on other assets; asset and property sales have been (£0.1m). Full year spending should be between £14m and £18m. 6.2Depreciation in 28 weeks totalled £1.08m (£0.96m in 28 weeks November1984). New Stores New store performance has been (at contribution level) :- 28 weeks to 9November1985 Rotherham trading72.8 contribution Scarborough pre opening costs(128.9) loss contribution Scarborough trading(42.9) loss contribution Brownhills pre opening costs(66.9) loss contribution Edenthorpe trading368.6 contribution Scunthorpe pre opening costs(184.5) loss contribution Scunthorpe trading(178.0) loss contribution Lincoln pre opening costs(94.1) loss contribution Lincoln trading(11.5) loss contribution (265.4) 28 weeks to 10November1984 Rotherham trading(89.2) loss contribution Rotherham pre opening costs(167.4) loss contribution Edenthorpe store & petrol trading117.9 contribution (138.7) Taxation The taxation charge has been prepared assuming £8.45m net profit for the year (including £450k capitalised interest) and capital expenditure of £16.0m. Productivity Measured on 32 stores, i.e. present stores less Jubbs, petrol, Scunthorpe, Scarborough, Brownhills and Rotherham hours worked have reduced by (0.3%) in the 28 weeks ending November1985, sales volume however in the same stores has reduced by (2.3%). Productivity therefore in these 32 stores declined by (2.1%). 10. Own Label Development We now have within Grocery, Provisions and Wines &Spirits504 lines. % of Grocery Sales-17% (incl Bread) % of Provisions Sales-40% % of Wines & Spirits Sales-10% % of Tobacco Seies - 7%