Hillards Centenary Annual report and accounts 1985 page 23 of 34 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
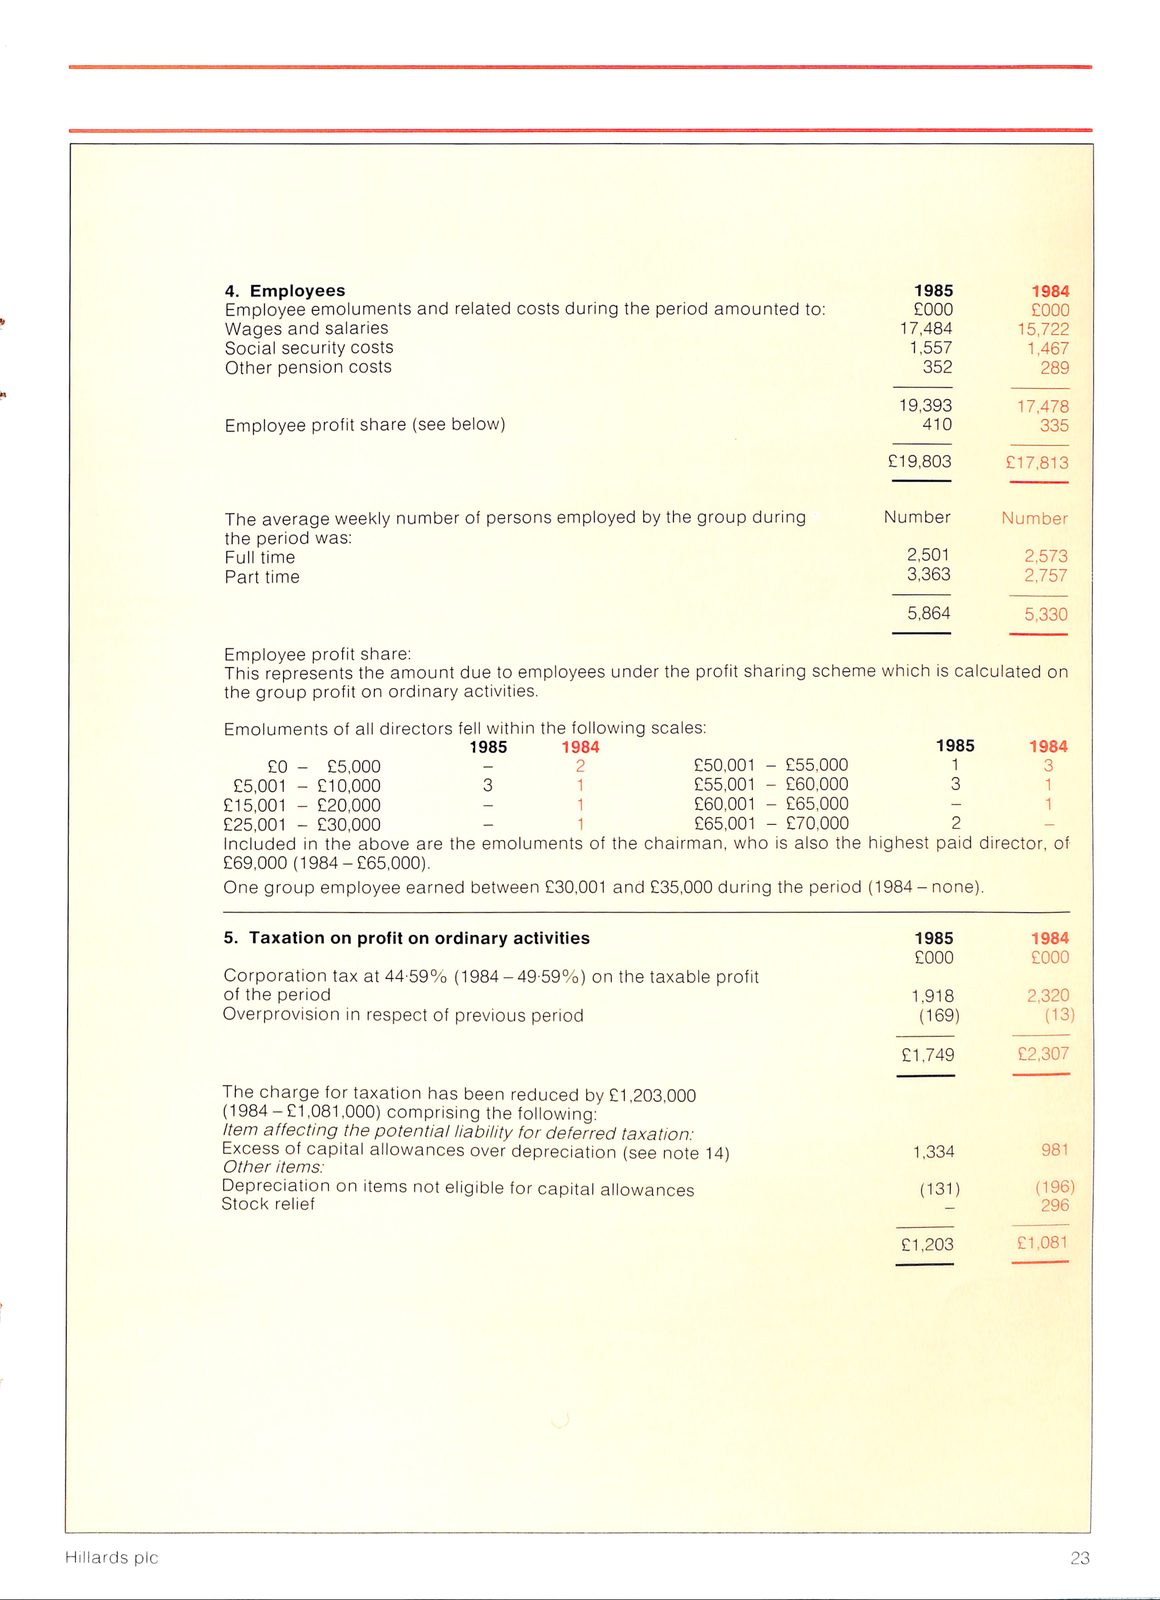
    4. Employees                                                                          1985           1984
    Employee emoluments and related costs during the period amounted to:                  £000           £000
    Wages and salaries                                                                  17,484         15,722
    Social security costs                                                                1,557          1,467
    Other pension costs                                                                    352            289

                                                                                        19,393         17,478
    Employee profit share (see below)                                                     4 10            335
                                                                                       £19,803        £17,813

    The average weekly number of persons employed by the group during                   Number         Number
    the period was:
Full time                                                                                2,501          2,573
    Part time                                                                            3,363          2,757

                                                                                         5,864          5,330

    Employee profit share:
    This represents the     amount due to employees under the    profit sharing scheme which Is calculated on
    the group profit on ordinary activities.

    Emoluments of ail directors fell within the following scales:
                             1985  1984                                              1985                1984
          £0  -        £5,000  -                  2              £50,001  -   £55,000            1  3
      £5,001  -     £10,000    3                  1              £55,001  -   £60,000            3  1
    £15,001   -     £20,000    -                  1              £60,001  -   £65,000            -  1
    £25,001   -     £30,000    -                  1              £65,001  -   £70,000            2
included in the above are the emoluments of the chairman, who is also the highest paid director, of
£69,000 (1984-£65,000).
    One group employee earned between £30,001 and £35,000 during the period (1984 - none).

    5. Taxation on profit on ordinary activities                                          1985           1984
    Corporation tax at 44'59% (1984-49-59%) on the taxable profit                         £000           £000
    of the period                                                                        1,918          2,320
    Overprovision in respect of previous period                                              (169)  (13)
                                                                                        £1,749         £2,307
    The charge for taxation has been reduced by £1,203,000
    (1984-£1,081,000) comprising the following:
    Item affecting the potential liability for deferred taxation:
    Excess of capital allowances over depreciation (see note 14)                         1,334            981
    Other Items:
    Depreciation on items not eligible for capital allowances                                (131)  (196)
    Stock relief                                                                                          296

                                                                                        £1,203         £1,081


    HIilards pic                                                                                    23
4.Employees1985 1984 Employee emoluments and related costs during the period amounted to: £000 £000 Wages and salaries17,48415,722 Social security costs1,5571,467 Other pension costs352289 19,393 17,478 Employee profit share (see below) 4 10 335 £19,803 £17,813 The average weekly number of persons employed by the group during Number Number the period was: Full time2,5012,573 Part time3,3632,757 5,864 5,330 Employee profit share: This represents the amount due to employees under the profit sharing scheme which Is calculated on the group profit on ordinary activities. Emoluments of ail directors fell within the following scales: 1985 1984 1985 1984 £0 - £5,000 - 2 £50,001 - £55,000 1 3 £5,001 - £10,000 3 1 £55,001 - £60,000 3 1 £15,001 - £20,000 - 1 £60,001 - £65,000 - 1 £25,001 - £30,000 - 1 £65,001 - £70,000 2 included in the above are the emoluments of the chairman, who is also the highest paid director, of £69,000 (1984-£65,000). One group employee earned between£30,001 and £35,000during the period(1984- none). 5. Taxation on profit on ordinary activities19851984 Corporation tax at 44'59% (1984-49-59%) on the taxable profit£000£000 of the period1,9182,320 Overprovision in respect of previous period(169)(13) £1,749 £2,307 The charge for taxation has been reduced by £1,203,000 (1984-£1,081,000)comprising the following: Item affecting the potential liability for deferred taxation: Excess of capital allowances over depreciation (see note14)1,334 981 Other Items: Depreciation on items not eligible for capital allowances(131)(196) Stock relief296 £1,203 £1,081 HIilards pic 23
Read by machine
    4. Employees                                                          1985       1984
    Employee emoluments and related costs during the period amounted to:    £000     £000
    Wages and salaries                                                    17,484
    Social security costs                                                           1,467
    Other pension costs                                                      352      289

                                                                          19,393   17,478
    Employee profit share (see below)                                        410      335

                                                                         £19,803  £17,813


    The  average     weekly number of persons       employed by the     group    during       Number       Number
    the period     was:
    Full time                                                                                                2073
    Part time                                                                                 3,363

                                                                                              5,864

Employee profit share:
This represents the amount due to employees under the profit sharing scheme which is calculated on
    the     group   profit on    ordinary activities.

    Emoluments of all directors fell within the     following scales:
                             1985  1984                                                                1985          1984
        £0      =      25,000        2                                    £50,001  — £55,000          1               3
      £5,001    —     £10,000  3     1                                    £55,001  — £60,000          3               1
    £15,001     —     £20,000  =     1                                    £60,001  — £65,000          =               1
    £25,001     —     £30,000  =     1                                    £65,001  — £70,000          2               -
    Included     in the    above  are the emoluments of the chairman, who is also the         highest  paid  director, of
    £69,000 1984     —     £65,000).
                                                                                              1984 none).
    One  group      employee earned between £30,001      and £35,000 during the period        —

    5.  Taxation     on    profit on ordinary activities                                          1985               1984
                                                                                                  £000               £000
    Corporation      tax at 44-59%    1984     — 49-59%     on  the taxable profit
    of the period                                                                                1,918              2,320
    Overprovision in       respect of previous period                                                (169)       (13)

                                                                                                £1,749             £2,307

    The charge for      taxation has been reduced        by £1,203,000
    1984 -£1 ,081,000          comprising the following:
    item affecting the         potential liability for deferred  taxation:
    Excess of capital allowances     over       depreciation     (see note 14                    1,334       981
    Other items:
    Depreciation     on    items  not eligible  for capital allowances                               (131)   (196)
    Stock relief                                                                                                      296

                                                                                                £1,203       £1,081


    Hillards plc                                                                                             23
4.Employees1985 1984 Employee emoluments and related costs during the period amounted to: £000 £000 Wages and salaries17,484 Social security costs1,467 Other pension costs352289 19,393 17,478 Employee profit share (see below)410335 £19,803 £17,813 The average weekly number of persons employed by the group during Number Number the period was: Full time2073 Part time3,363 5,864 Employee profit share: This represents the amount due to employees under the profit sharing scheme which is calculated on the group profit on ordinary activities. Emoluments of all directors fell within the following scales: 1985 1984 1985 1984 £0 = 25,000 2 £50,001 - £55,000 1 3 £5,001 - £10,000 3 1 £55,001 - £60,000 3 1 £15,001 - £20,000 = 1 £60,001 - £65,000 = 1 £25,001 - £30,000 = 1 £65,001 - £70,000 2 - Included in the above are the emoluments of the chairman, who is also the highest paid director, of £69,000 1984 - £65,000). 1984none). One group employee earned between£30,001 and £35,000during the period - 5. Taxation on profit on ordinary activities19851984 £000 £000 Corporation tax at 44-59% 1984 - 49-59% on the taxable profit of the period1,9182,320 Overprovision in respect of previous period(169)(13) £1,749 £2,307 The charge for taxation has been reduced by £1,203,000 1984 -£1,081,000comprising the following: item affecting the potential liability for deferred taxation: Excess of capital allowances over depreciation (see note141,334 981 Other items: Depreciation on items not eligible for capital allowances(131)(196) Stock relief296 £1,203 £1,081 Hillards plc 23
Read by machine, contrast corrected highest quality of the three
4.  Employees                                                                                      1985            1984
Employee emoluments and related costs during the period amounted to:                               £000            £000
Wages and salaries                                                                           17,484              15,722
Social security costs                                                                         1,557               1,467
Other pension costs                                                                             352                 289

                                                                                             19,393              17,478
Employee profit share (see     below)                                                           410                 335

                                                                                            £19,803             £17,813

The  average     weekly number of persons      employed by the     group     during          Number              Number
the period     was:
Full time                                                                                     2,501               2,573
Part time                                                                                     3,363

                                                                                              5,864               5,330

Employee profit share:
This represents the amount due to            employees under the profit sharing scheme which is calculated           on
the     group   profit on  ordinary activities.

Emoluments of all directors fell within the    following scales:
                         1985  1984                                                                 1985           1984
    £0      —      £5,000  =     2                                    £50,001  —  £55,000              1            3
  £5,001    —     £10,000  3     1                                    £55,001  —  £60,000              3            1
£15,001     —     £20,000  =     1                                    £60,001  —  £65,000              =            1
£25,001     —     £30,000  =     1                                    £65,001  —  £70,000              2
Included     in the    above  are the emoluments of the chairman, who is also the          highest  paid   director, of
£69,000 1984     —     £65,000).
                                                                                           1984 none).
One  group      employee earned between £30,001     and £35,000 during the period          —

5.  Taxation     on    profit on ordinary activities                                               1985            1984
                                                                                                   £000            £000
Corporation      tax at 44-59%    1984     — 49-59%     on  the taxable profit
of the period                                                                                     1,918           2,320
Overprovision in       respect of previous period                                          (169)               (13)

                                                                                                 £1,749          £2,307

The charge for      taxation has been reduced      by £1,203,000
1984 -£1 081 ,000          comprising the following:
Item affecting the         potential liability for deferred  taxation:
    of     capital allowances
Excess                     over             depreciation     (see note 14                         1,334             981
Other items:
Depreciation     on    items  not eligible  for capital allowances                         (131)           (196)
Stock relief                                                                                          =             296

                                                                                                 £1,203          £1,081


Hillards pic                                                                                               23
4.Employees1985 1984 Employee emoluments and related costs during the period amounted to: £000 £000 Wages and salaries17,48415,722 Social security costs1,5571,467 Other pension costs352289 19,393 17,478 Employee profit share (see below)410335 £19,803 £17,813 The average weekly number of persons employed by the group during Number Number the period was: Full time2,5012,573 Part time3,363 5,864 5,330 Employee profit share: This represents the amount due to employees under the profit sharing scheme which is calculated on the group profit on ordinary activities. Emoluments of all directors fell within the following scales: 1985 1984 1985 1984 £0 - £5,000 = 2 £50,001 - £55,000 1 3 £5,001 - £10,000 3 1 £55,001 - £60,000 3 1 £15,001 - £20,000 = 1 £60,001 - £65,000 = 1 £25,001 - £30,000 = 1 £65,001 - £70,000 2 Included in the above are the emoluments of the chairman, who is also the highest paid director, of £69,000 1984 - £65,000). 1984none). One group employee earned between£30,001 and £35,000during the period - 5. Taxation on profit on ordinary activities19851984 £000 £000 Corporation tax at 44-59% 1984 - 49-59% on the taxable profit of the period1,9182,320 Overprovision in respect of previous period(169)(13) £1,749 £2,307 The charge for taxation has been reduced by £1,203,000 1984 -£1 081,000comprising the following: Item affecting the potential liability for deferred taxation: of capital allowances Excess over depreciation (see note141,334 981 Other items: Depreciation on items not eligible for capital allowances(131)(196) Stock relief=296 £1,203 £1,081 Hillards pic 23