Hillards Annual report and accounts 1984 page 24 of 28 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
    HILLARDS pic


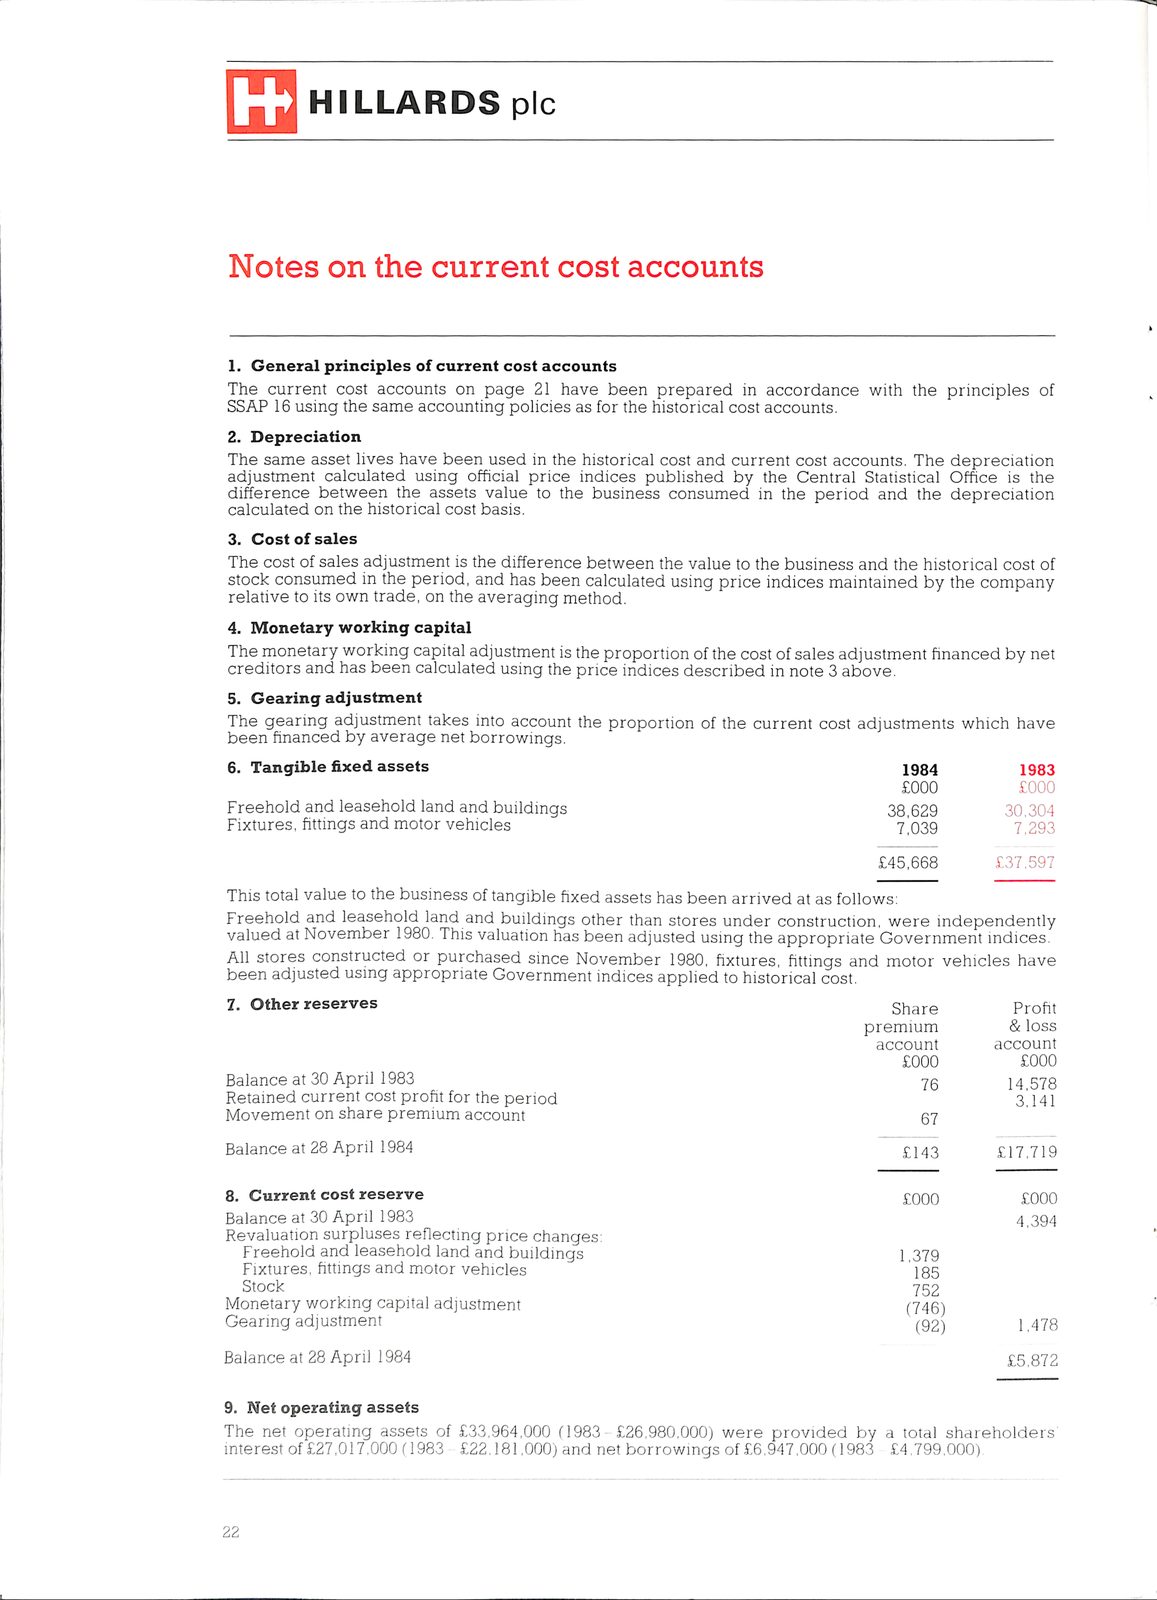
    Notes on the current cost accounts


    1.  General principles of current cost accounts
    The current  cost     accounts on      page    21 have  been prepared  in accordance with     the principles     of
    SSAP 16 using the same accounting policies as for the historical cost accounts.
    2.  Depreciation
    The same asset lives have been used in the          historical cost and current cost accounts.     The depreciation
    adjustment   calculated     using official   price  indices published  by the Central Statistical     Office is the
    difference   between  the     assets  value    to the business consumed in the period and     the      depreciation
    calculated on the historical cost basis.
    3.  Cost of sales
    The cost of sales adjustment is         the difference between the value to the business and the historical cost of
    stock consumed in the period, and has been calculated using price indices maintained by the company
    relative to its own trade, on the averaging method.
    4.  Monetary working capital
    The monetary working capital adjustment is the proportion of the cost ofsales adjustment financed by net
    creditors and has been calculated using the price indices described in note 3 above.
    5.  Gearing adjustment
    The gearing adjustment takes into account           the proportion of the current cost       adjustments which have
    been financed by average net borrowings.
    6.  Tangible fixed assets                                                                    1984              1983
                                                                                                 £000              £000
    Freehold and leasehold land and buildings                                                  38,629            30,304
    Fixtures, fittings and motor vehicles                                                       7^039             7!293

                                                                                              £45,668           £37.597
This total value to the business of tangible fixed assets has been arrived at as follows:
    Freehold and leasehold land and buildings other than stores under                  construction, were independently
    valued at November 1980. This valuation has been adjusted using the appropriate Government indices.
    All stores constructed or purchased since November 1980,     hxtures,     fittings          and motor vehicles have
    been adjusted using appropriate Government indices applied to historical cost.
    7.  Other reserves                                                                          Share            Profit
                                                                                              premium            & loss
                                                                                              account           account
                                                                                                 £000              £000
    Balance at 30 April 1983                                                                       76            14,578
    Retained current cost profit for the period                                                                   3,141
    Movement on share premium account                                                              67
    Balance at 28 April 1984                                                                     £143          £17,7 19

    8.  Current cost reserve                                                                     £000              £000
    Balance at 30 April 1983                                                                                      4.394
    Revaluation surpluses reflecting price changes:
        Freehold and leasehold land and buildings    1 379
          Fixtures, fittings and motor vehicles                                                      '185
        Stock                                                                                     752
    Monetary working capital adjustment                                                       (746)
    Gearingadjustment                                                                                (92)          1473
    Balance at 28 April   1984                                                                                   £5.872

    9.  Net operating assets
    The net   operating   assets  of  £33,964,000     (1983 - £26,980,000) were provided by a   total     shareholders'
interest of £27,017,000 (1983 £22.181,000) and net borrowings of £6,947,000 (1983 £4.799,000).


    22
HILLARDS pic Notes on the current cost accounts 1. General principles of current cost accounts The current cost accounts on page 21 have been prepared in accordance with the principles of SSAP 16 using the same accounting policies as for the historical cost accounts. 2. Depreciation The same asset lives have been used in the historical cost and current cost accounts. The depreciation adjustment calculated using official price indices published by the Central Statistical Office is the difference between the assets value to the business consumed in the period and the depreciation calculated on the historical cost basis. 3. Cost of sales The cost of sales adjustment is the difference between the value to the business and the historical cost of stock consumed in the period, and has been calculated using price indices maintained by the company relative to its own trade, on the averaging method. 4. Monetary working capital The monetary working capital adjustment is the proportion of the cost ofsales adjustment financed by net creditors and has been calculated using the price indices described in note 3 above. 5. Gearing adjustment The gearing adjustment takes into account the proportion of the current cost adjustments which have been financed by average net borrowings. 6. Tangible fixed assets19841983 £000 £000 Freehold and leasehold land and buildings38,62930,304 Fixtures, fittings and motor vehicles7^0397!293 £45,668 £37.597 This total value to the business of tangible fixed assets has been arrived at as follows: Freehold and leasehold land and buildings other than stores under construction, were independently valued at November1980. This valuation has been adjusted using the appropriate Government indices. All stores constructed or purchased since November1980, hxtures, fittings and motor vehicles have been adjusted using appropriate Government indices applied to historical cost. 7. Other reserves Share Profit premium & loss account account £000 £000 Balance at 30April1983 76 14,578 Retained current cost profit for the period3,141 Movement on share premium account 67 Balance at 28April1984 £143 £17,7 19 8. Current cost reserve£000£000 Balance at 30April1983 4.394 Revaluation surpluses reflecting price changes: Freehold and leasehold land and buildings1379 Fixtures, fittings and motor vehicles'185 Stock752 Monetary working capital adjustment(746) Gearingadjustment (92) 1473 Balance at 28April1984 £5.872 9. Net operating assets The net operating assets of £33,964,000 (1983 -£26,980,000)were provided by a total shareholders' interest of £27,017,000 (1983 £22.181,000) and net borrowings of £6,947,000 (1983 £4.799,000). 22
Read by machine
    + HILLARDS plc


    Notes on the current cost accounts


    1.  General principles of current cost accounts
    The current     cost    accounts on page    21 have  been prepared    in accordance with     the     principles     of
SSAP 16 using the same accounting policies as for the historical cost accounts.
2. Depreciation
    The same    asset  lives have been used in the historical   cost and  current cost accounts.          The depreciation
    adjustment  calculated  using    official   price indices published   by the Central Statistical         Office is the
    difference  between     the  assets value   to the business consumed in     the period and   the          depreciation
    calculated  on  the historical   cost basis.

    3.  Cost of sales
    The cost of sales adjustment is the difference between the  value to the business and the historical         cost   of
    stock consumed in the period, and has been calculated     using price indices maintained by the                company
    relative to its own  trade, on   the averaging method.

    4.  Monetary working capital
    The monetary working capital adjustment is the     proportion of the  cost of sales adjustment financed by         net
creditors and has been calculated using the price indices described in note 3 above.
5. Gearing adjustment
    The gearing adjustment takes into        account the proportion of the   current cost adjustments which           have
    been financed by     average net     borrowings.
    6.  Tangible fixed assets                                                                    1924
                                                                                                 £000                 £000
    Freehold and leasehold land and buildings                                                  96.629                   oo
    Fixtures, fittings and  motor vehicles                                                      8,629                0.204

                                                                                              £45,668              £37,597

    This total value to  the business of  tangible fixed assets has been arrived at  as follows:
    Freehold and leasehold land and buildings       other than  stores under construction, were              independently
    valued at   November 1980. This    valuation has been adjusted using the appropriate Government indices.
    All stores  constructed or   purchased since     November   1980,  fixtures, fittings and motor     vehicles      have
been adjusted using appropriate Government indices applied to historical cost.
    7.  Other   reserves                                                                        Share               Profit
                                                                                              premium               & loss
                                                                                              account              account
                                                                                                 £000                 £000
    Balance at 30   April   1983                                                                   16               14.578
    Retained current cost profit for the  period                                                                     3,141
    Movement on     share premium    account                                                       67
    Balance at  28 April    1984                                              9143

    8.  Current cost   reserve    £000                                                                                £000
    Balance at  30 April    1983                                                                                     4.394
    Revaluation surpluses reflecting price changes:
       Freehold and leasehold land and buildings                                                1,379
       Fixtures, fittings and motor vehicles                                                     185
       Stock                                                                                     752
    Monetary working capital adjustment                                                             (746)
    Gearing adjustment                                                                               (92)            1.478
    Balance at 28 April     1984                                                                                    £8.872


9. Net operating assets
The net operating assets of £33,964,000 £26,980,000) were provided by a total shareholders
interest of £27,017,000 1983 £22,181,000) and net borrowings of £6,947,000 1983 £4,799,000)
+ HILLARDS plc Notes on the current cost accounts 1. General principles of current cost accounts The current cost accounts on page 21 have been prepared in accordance with the principles of SSAP 16 using the same accounting policies as for the historical cost accounts. 2. Depreciation The same asset lives have been used in the historical cost and current cost accounts. The depreciation adjustment calculated using official price indices published by the Central Statistical Office is the difference between the assets value to the business consumed in the period and the depreciation calculated on the historical cost basis. 3. Cost of sales The cost of sales adjustment is the difference between the value to the business and the historical cost of stock consumed in the period, and has been calculated using price indices maintained by the company relative to its own trade, on the averaging method. 4. Monetary working capital The monetary working capital adjustment is the proportion of the cost of sales adjustment financed by net creditors and has been calculated using the price indices described in note 3 above. 5. Gearing adjustment The gearing adjustment takes into account the proportion of the current cost adjustments which have been financed by average net borrowings. 6. Tangible fixed assets1924 £000 £000 Freehold and leasehold land and buildings96.629 oo Fixtures, fittings and motor vehicles8,6290.204 £45,668 £37,597 This total value to the business of tangible fixed assets has been arrived at as follows: Freehold and leasehold land and buildings other than stores under construction, were independently valued at November1980. This valuation has been adjusted using the appropriate Government indices. All stores constructed or purchased since November1980, fixtures, fittings and motor vehicles have been adjusted using appropriate Government indices applied to historical cost. 7. Other reserves Share Profit premium & loss account account £000 £000 Balance at 30April1983 16 14.578 Retained current cost profit for the period3,141 Movement on share premium account 67 Balance at 28April1984 9143 8. Current cost reserve£000£000 Balance at 30April1983 4.394 Revaluation surpluses reflecting price changes: Freehold and leasehold land and buildings1,379 Fixtures, fittings and motor vehicles185 Stock752 Monetary working capital adjustment(746) Gearing adjustment(92)1.478 Balance at 28April1984 £8.872 9. Net operating assets The net operating assets of £33,964,000£26,980,000)were provided by a total shareholders interest of £27,017,000 1983 £22,181,000) and net borrowings of £6,947,000 1983 £4,799,000)
Read by machine, contrast corrected highest quality of the three
    + HILLARDS plc


    Notes on the current cost accounts


    1,  General principles of current cost accounts
    The current     cost    accounts on page    2 have  been  prepared    in accordance with     the     principles          of
SSAP 16 using the same accounting policies as for the historical cost accounts.
2. Depreciation
    The same    asset  lives have been used in the historical   cost and  current cost accounts.               The depreciation
    adjustment  calculated  using    official   price indices published   by the Central Statistical             Office is  the
    difference  between     the  assets value   to the business consumed in     the period and   the               depreciation
    calculated  on  the historical   cost basis.

    3.  Cost of sales
    The cost of sales adjustment is the difference between the  value to the business and the historical             cost    of
    stock consumed in the period, and has been calculated     using price indices maintained by the                     company
    relative to its own  trade, on   the averaging method.

    4.  Monetary working capital
    The monetary working capital adjustment is the     proportion of the  cost of sales adjustment financed by              net
creditors and has been calculated using the price indices described in note 3 above.
5. Gearing adjustment
    The gearing adjustment takes into       account the proportion of the    current cost                adjustments which have
    been financed by average net borrowings.

    6.  Tangible fixed assets                                                                    1984                      1983
                                                                                                 £000                      £000
    Freehold and leasehold land and buildings                                                  38,629                    30.304
    Fixtures, fittings and  motor vehicles                                                      7,039                     7.293
                                                                                              £45,668                   £37,597
    This total value to  the business of tangible fixed assets has been arrived at   as follows:
    Freehold and leasehold land and buildings      other  than  stores under construction, were                   independently
    valued at   November 1980. This   valuation has been  adjusted using the appropriate Government indices.
    All stores  constructed or   purchased since     November   1980,  fixtures, fittings and motor     vehicles           have
been adjusted using appropriate Government indices applied to historical cost.
    7.  Other   reserves                                                                        Share                     Profit
                                                                                              premium                    & loss
                                                                                              account                   account
                                                                                                     £000                   £000
    Balance at 30   April   1983                                                                   16                     14,578
    Retained current cost profit for the  period                                                                          3,141
    Movement on     share premium    account                                                       67
    Balance at  28 April    1984                                                                     9143

    8.  Current cost   reserve                                                                       £000                   £000
    Balance at  30 April    1983                                                                                           4.394
    Revaluation surpluses reflecting price changes:
       Freehold and leasehold land and buildings                                                1,379
       Fixtures, fittings and motor vehicles                                                          185
       Stock                                                                                          752
    Monetary working capital adjustment                                                                 (746)
    Gearing adjustment                                                                                   (92)              1.478
    Balance at 28 April     1984                                                                                          £5,872


9. Net operating assets
The net operating assets of £33,964,000 1983 - £26,980,000) were provided by a total shareholders
interest of £27,017,000 1983 £22,181,000) and net borrowings of £6,947,000 1983 £4,799,000)
+ HILLARDS plc Notes on the current cost accounts 1, General principles of current cost accounts The current cost accounts on page 2 have been prepared in accordance with the principles of SSAP 16 using the same accounting policies as for the historical cost accounts. 2. Depreciation The same asset lives have been used in the historical cost and current cost accounts. The depreciation adjustment calculated using official price indices published by the Central Statistical Office is the difference between the assets value to the business consumed in the period and the depreciation calculated on the historical cost basis. 3. Cost of sales The cost of sales adjustment is the difference between the value to the business and the historical cost of stock consumed in the period, and has been calculated using price indices maintained by the company relative to its own trade, on the averaging method. 4. Monetary working capital The monetary working capital adjustment is the proportion of the cost of sales adjustment financed by net creditors and has been calculated using the price indices described in note 3 above. 5. Gearing adjustment The gearing adjustment takes into account the proportion of the current cost adjustments which have been financed by average net borrowings. 6. Tangible fixed assets19841983 £000 £000 Freehold and leasehold land and buildings38,62930.304 Fixtures, fittings and motor vehicles7,0397.293 £45,668 £37,597 This total value to the business of tangible fixed assets has been arrived at as follows: Freehold and leasehold land and buildings other than stores under construction, were independently valued at November1980. This valuation has been adjusted using the appropriate Government indices. All stores constructed or purchased since November1980, fixtures, fittings and motor vehicles have been adjusted using appropriate Government indices applied to historical cost. 7. Other reserves Share Profit premium & loss account account £000 £000 Balance at 30April1983 16 14,578 Retained current cost profit for the period3,141 Movement on share premium account 67 Balance at 28April1984 9143 8. Current cost reserve£000£000 Balance at 30April1983 4.394 Revaluation surpluses reflecting price changes: Freehold and leasehold land and buildings1,379 Fixtures, fittings and motor vehicles185 Stock752 Monetary working capital adjustment(746) Gearing adjustment(92)1.478 Balance at 28April1984 £5,872 9. Net operating assets The net operating assets of £33,964,000 1983 -£26,980,000)were provided by a total shareholders interest of £27,017,000 1983 £22,181,000) and net borrowings of £6,947,000 1983 £4,799,000)