Preliminary Results for year to 27/04/1985 page 1 of 4 next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
                Preliminary Results        23rd    July 1985

Company Results Hilfards
    Service

                Results for Year to 27th April 1985


    Recommendation                     Fully Valued                             Price         346p

                                                  Profits,     Earnings and Dividends
    Price : 346p                              Full year ending April           1984A  1985A  1986F
    12 Month Range : 202-413p                 Pre-interest    profit    (£m)     7.2    8.3    9.7
    Price Index     Ratio : 740               Pre-tax    profit (£m)             6.8    7.7    8.7
    Three Year Range : 523-827                Earnings (actual)     p           18.2   24.4   25.6
                                              Earnings (fully taxed)     p      13.8   17.3  2 1.4
    Market Capitalisation : £85m              Dividend (net)   p                 4.8    5.8    6.0
    Price relative to market                  PER (actual)                      19.0   14.2   13.5
    Imonth      ^months            12months   PER (fully  taxed)                  .0   20.0   16.2    25
    -1 %        +4%                + 32%      Yield %                           2.0%   2.4%   2.5%


                                                         Summary
    Pre-tax    profits        were in line with expectations at     to do so until the cash      flow generated by the new
    £7.73m,  an increase       of     14% over   the   previous     stores  outweighs the   level of capital   expenditure
    period. A fail in the tax        rate from 34%to 22% due to     (in  three   to four years time).   However,   current
    capital  spending          gave   strong  growth at     the     trading  is  benefiting from the end of the    miners'
    earnings   level.      EPS were   up  34% to     24.4p. The     strike  and     improvements in   productivity     and
    results show that the business held up well during              product mix can be expected.
    the miners' strike and actually managed to increase
    margins  despite        a  slight fall in volume    through        Our forecast for  the   53 weeks to 3rd    May 1986
    existing stores.                                                shows a 13% improvement in profits to £8.7m but
                                                                    with a tax charge    rising to at least 28% EPS growth
        The future      is     dominated      by the   physical     will      be limited to around 4%. The prospective PER
    expansion   programme.         In the     recent past there     of 13.5 is fairly demanding given      the competitive
    have              been one or two openings per annum. Plans     market in the Yorkshire area, but the share price
    are to step this up to two to three stores a year in the        tends to   move as much on   bid  speculation    as on
    future  but in  the     current   period four    large, new     fundamentals.   A resurgence     of such       rumours
    stores will be          opened. Thus profits growth will be     could provide a good selling opportunity since at a
    restrained  this    year   by increased      opening  costs     price around the recent high       Hillards would seem
    although   these    will reduce   in      subsequent years.     to  be an   expensive acquisition for      any company
    Interest charges will also rise sharply and continue            after  building in any premium.


    Analyst             Liz    Crozier                              HOARE        GOVETT
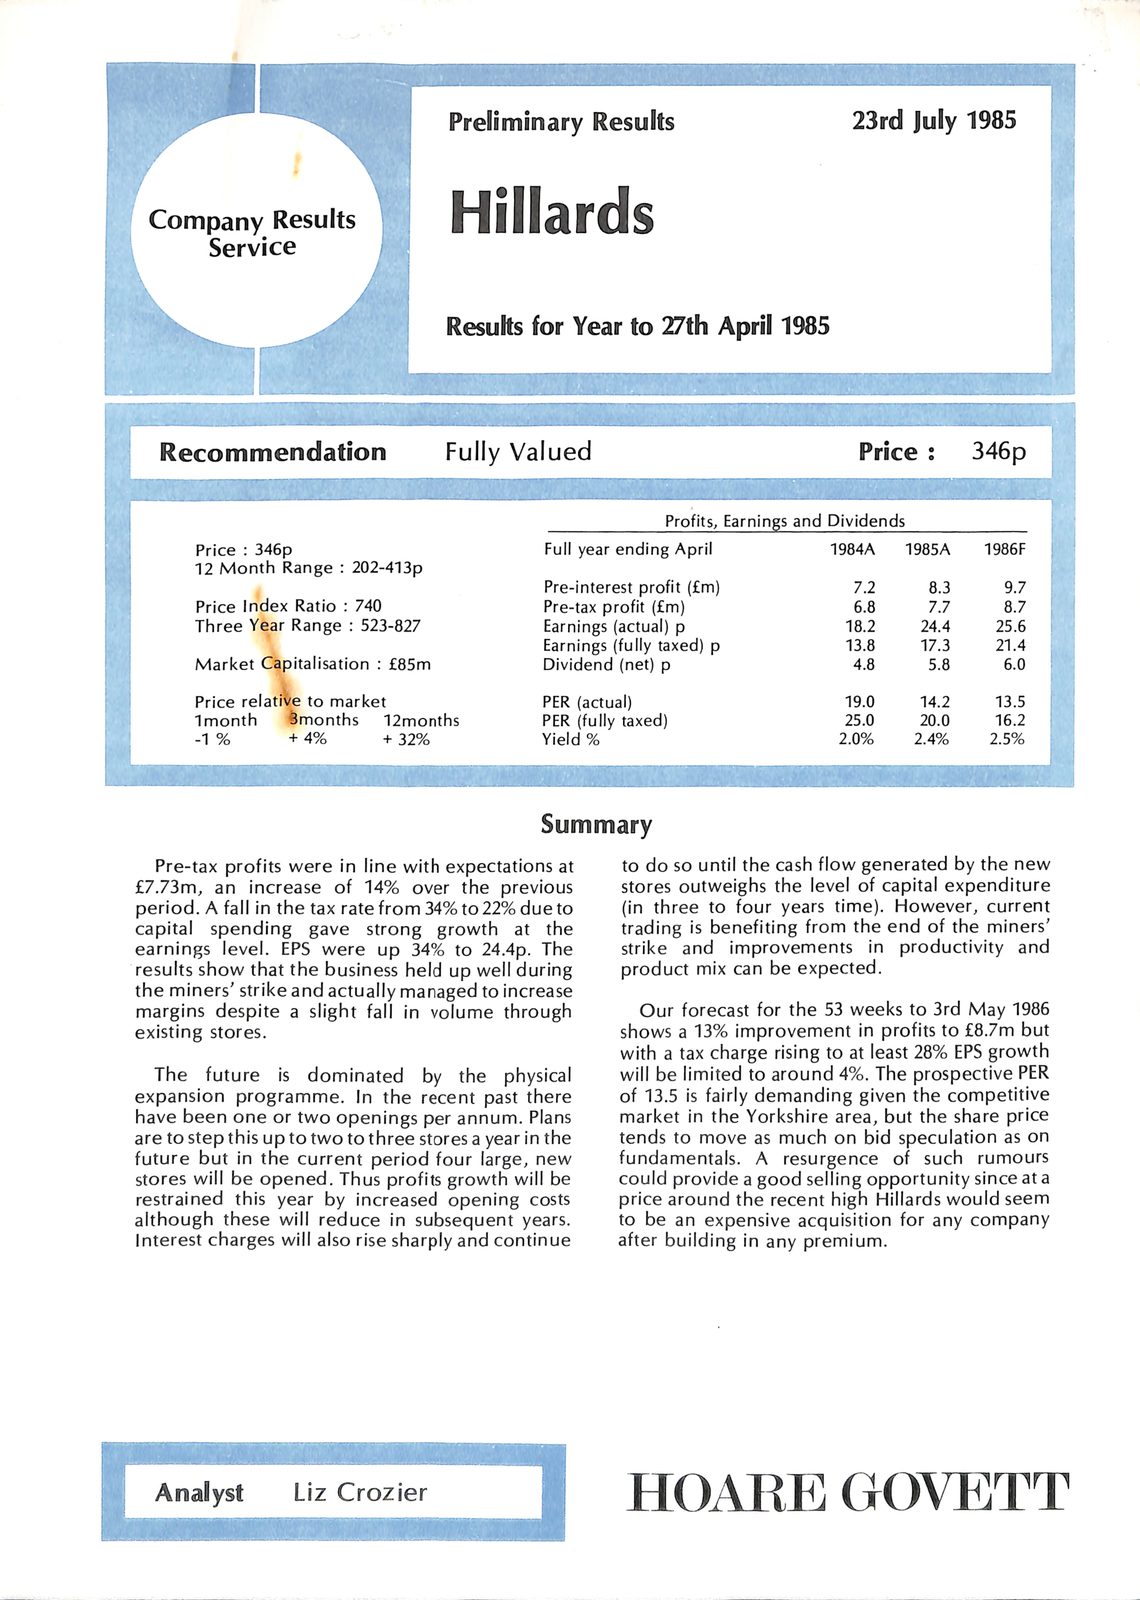
Preliminary Results 23rd July1985 Company Results Hilfards Service Results for Year to 27th April1985 Recommendation Fully Valued Price 346p Profits, Earnings and Dividends Price : 346p Full year ending April 1984A 1985A 1986F 12 Month Range : 202-413p Pre-interest profit (£m) 7.2 8.3 9.7 Price Index Ratio:740 Pre-tax profit (£m) 6.8 7.7 8.7 Three Year Range:523-827 Earnings (actual) p 18.2 24.4 25.6 Earnings (fully taxed) p 13.8 17.3 2 1.4 Market Capitalisation : £85m Dividend (net) p 4.8 5.8 6.0 Price relative to market PER (actual)19.014.2 13.5 Imonth ^months 12months PER (fully taxed).020.0 16.2 25 -1 % +4% +32%Yield % 2.0% 2.4% 2.5% Summary Pre-tax profits were in line with expectations at to do so until the cash flow generated by the new £7.73m, an increase of 14%over the previous stores outweighs the level of capital expenditure period. A fail in the tax rate from 34%to 22% due to (in three to four years time). However, current capital spending gave strong growth at the trading is benefiting from the end of the miners' earnings level. EPS were up 34% to 24.4p. The strike and improvements in productivity and results show that the business held up well during product mix can be expected. the miners' strike and actually managed to increase margins despite a slight fall in volume through Our forecast for the 53 weeks to 3rd May 1986 existing stores. shows a 13%improvement in profits to £8.7m but with a tax charge rising to at least28% EPS growth The future is dominated by the physical will be limited to around4%. The prospective PER expansion programme. In the recent past thereof13.5 is fairly demanding given the competitive have been one or two openings per annum. Plans market in the Yorkshire area, but the share price are to step this up to two to three stores a year in the tends to move as much on bid speculation as on future but in the current period four large, new fundamentals. A resurgence of such rumours stores will be opened. Thus profits growth will be could provide a good selling opportunity since at a restrained this year by increased opening costs price around the recent high Hillards would seem although these will reduce in subsequent years. to be an expensive acquisition for any company Interest charges will also rise sharply and continue after building in any premium. Analyst Liz Crozier HOARE GOVETT
Read by machine highest quality of the three
                      |   Preliminary Results

Company Results  y\\|     Hillards
    Service      |

                          for Year to 27th April 1985


    Recommendation Fully Valued    Price: 346p


                                                                    Profits,     Earnings and Dividends
        Price : 346p                            Full year   ending April                                    1986F
    |   12 Month Range    :     202-413p
                                                Pre-interest     profit (£m)                            8.3   9.7
        Price Index Ratio    : 740               Pre-tax    profit (£m)          6.8                    7.7   8.7
        Three Year Range     :   523-827         Earnings (actual)  p            18.2                  24.4  25.6
                                                 Earnings (fully taxed)     p    13.8                  17.3  21.4
        Market Capitalisation  :      £85m       Dividend   (net)  p              4.8                   5.8   6.0
        Price relative  to market                PER (actual)                    19.0                  14.2  13.5
        Imonth   8months              12months   PER (fully taxed)               25.0                  20.0  16.2
        -1%      +     4%             + 32%      Yield %                         2.0%                  2.4%  2.5%


                                                          Summary
    Pre-tax     profits     were in line with expectations  at       to  do so     until the cash flow generated   by the    new
    £7.73m,  an     increase     of 14% over    the       previous   stores   outweighs    the level    of capital   expenditure
    period.  A fall in    the tax rate from 34% to  22% due     to   (in  three     to   four years  time).   However,   current
    capital    spending     gave    strong     growth at       the   trading    is  benefiting from the end of the       miners’
    earnings   level.   EPS   were     up 34%  to   24.4p.     The   strike   and      improvements       in  productivity   and
    results show that the business        held up      well during   product mix       can      be expected.
    the miners’ strike and actually managed     to        increase
    margins    despite   a    slight fall in volume    through          Our forecast     for  the   53 weeks  to 3rd    May 1986
    existing   stores.                                               shows    a 13% improvement in       profits   to £8.7m  but
                                                                     with  a  tax   charge rising   to at least 28% EPS   growth
    The     future      is    dominated     by  the   physical       will be limited     to       around 4%. The prospective PER
    expansion    programme.     In     the   recent past     there   of  13.5   is fairly        demanding given the competitive
    have been    one    or  two     openings per annum.  Plans       market     in  the Yorkshire    area,   but the share price
        step     this     to     to               three stores
    are to      up     two                a year in            the   tends   to    move as    much   on   bid speculation  as on
    future  but  in    the  current   period four   large, new       fundamentals.      A     resurgence     of such     rumours
    stores  will be opened. Thus profits growth will        be       could provide      a good selling opportunity since at    a
    restrained   this  year   by     increased opening   costs       price around the     recent    high  Hillards would    seem
    although     these will   reduce   in  subsequent   years.       to  be  an    expensive acquisition     for     any company
    Interest charges will also       rise sharply and continue       after  building     in any premium.


    Analyst —    Liz Crozier                                         HOARE GOVETT
| Preliminary Results Company Results y\\| Hillards Service | for Year to 27th April1985 Recommendation Fully Valued Price: 346p Profits, Earnings and Dividends Price : 346p Full year ending April 1986F | 12 Month Range : 202-413p Pre-interest profit (£m) 8.3 9.7 Price Index Ratio:740 Pre-tax profit (£m) 6.8 7.7 8.7 Three Year Range:523-827 Earnings (actual) p 18.2 24.4 25.6 Earnings (fully taxed) p 13.8 17.3 21.4 Market Capitalisation : £85m Dividend (net) p 4.8 5.8 6.0 Price relative to market PER (actual)19.014.2 13.5 Imonth 8months 12months PER (fully taxed)25.020.0 16.2 -1% + 4% +32%Yield % 2.0% 2.4% 2.5% Summary Pre-tax profits were in line with expectations at to do so until the cash flow generated by the new £7.73m, an increase of 14%over the previous stores outweighs the level of capital expenditure period. A fall in the tax rate from34% to 22% due to (in three to four years time). However, current capital spending gave strong growth at the trading is benefiting from the end of the miners' earnings level. EPS were up 34% to 24.4p. The strike and improvements in productivity and results show that the business held up well during product mix can be expected. the miners' strike and actually managed to increase margins despite a slight fall in volume through Our forecast for the 53 weeks to 3rd May 1986 existing stores. shows a 13%improvement in profits to £8.7m but with a tax charge rising to at least28% EPS growth The future is dominated by the physical will be limited to around4%. The prospective PER expansion programme. In the recent past thereof13.5 is fairly demanding given the competitive have been one or two openings per annum. Plans market in the Yorkshire area, but the share price step this to to three stores are to up two a year in the tends to move as much on bid speculation as on future but in the current period four large, new fundamentals. A resurgence of such rumours stores will be opened. Thus profits growth will be could provide a good selling opportunity since at a restrained this year by increased opening costs price around the recent high Hillards would seem although these will reduce in subsequent years. to be an expensive acquisition for any company Interest charges will also rise sharply and continue after building in any premium. Analyst - Liz Crozier HOARE GOVETT
Read by machine, contrast corrected
|


                           Preliminary Results    23rd July 1985

Company Results   |        Hillards
Service            i's|        |

    4                |     for Year to 27th     April 1985


Recommendation       Fully Valued    Price: 346p


                                                            Profits,     Earnings and Dividends
Price : 346p                            Full year   ending April          1984A               1985A  1986F
12 Month Range    :  202-413p
                                        Pre-interest     profit (£m)      7.2                   8.3    9.7
Price Index Ratio    : 740               Pre-tax    profit (£m)          6.8                    7.7    8.7
Three Year Range     : 523-827           Earnings (actual)  p            18.2                  24.4   25.6
                                         Earnings (fully taxed)     p    13.8                  17.3   21.4
Market Capitalisation  :      £85m       Dividend   (net)  p              4.8                   5.8    6.0
Price relative  to market                PER (actual)                    19.0                  14.2   13.5
Imonth   8months              12months   PER (fully taxed)               25.0                  20.0   16.2
-1%      +     4%             + 32%      Yield %                         2.0%                  2.4%   2.5%


                                                     Summary
Pre-tax     profits    were in line with expectations   at      to  do so     until the cash flow generated by the      new
£7.73m,  an     increase    of 14% over     the      previous   stores   outweighs the level       of capital   expenditure
period.  A fall in    the tax rate from 34% to  22% due    to   (in  three     to   four years  time).   However,   current
capital    spending     gave   strong     growth  at      the   trading    is  benefiting from the end of the       miners’
earnings   level.   EPS   were     up 34% to    24.4p.    The   strike   and      improvements       in  productivity   and
results show that the business     held   up      well during   product mix       can      be expected.
the miners’ strike and actually managed     to       increase
margins    despite   a    slight fall in volume   through          Our forecast     for  the   53 weeks  to 3rd    May 1986
existing   stores.                                              shows    a 13% improvement in       profits   to £8.7m  but
                                                                with  a  tax   charge rising   to at least 28% EPS   growth
The     future      is    dominated     by  the  physical       will be limited     to       around 4%. The prospective PER
expansion    programme.     In     the   recent past    there   of  13.5   is fairly demanding     given the    competitive
have been    one    or two      openings per annum. Plans       market     in  the Yorkshire    area,   but the share price
    step     this      to                    three stores
are to      up       to two        a year            in   the   tends   to    move as    much   on   bid speculation  as on
future  but  in    the  current  period four    large,    new   fundamentals.      A     resurgence     of such     rumours
stores  will be opened. Thus profits growth will       be       could provide      a good selling opportunity since at    a
restrained   this  year   by     increased opening  costs       price around the     recent    high  Hillards would    seem
although     these will   reduce   in  subsequent  years.       to  be  an    expensive acquisition     for any     company
Interest charges will also      rise sharply and continue       after  building     in any premium.


         =                    !
|    Analyst  Liz Crozier     | HOARE GOVETT
| Preliminary Results 23rd July1985 Company Results | Hillards Service i's| | 4 | for Year to 27th April1985 Recommendation Fully Valued Price: 346p Profits, Earnings and Dividends Price : 346p Full year ending April 1984A 1985A 1986F 12 Month Range : 202-413p Pre-interest profit (£m) 7.2 8.3 9.7 Price Index Ratio:740 Pre-tax profit (£m) 6.8 7.7 8.7 Three Year Range:523-827 Earnings (actual) p 18.2 24.4 25.6 Earnings (fully taxed) p 13.8 17.3 21.4 Market Capitalisation : £85m Dividend (net) p 4.8 5.8 6.0 Price relative to market PER (actual)19.014.2 13.5 Imonth 8months 12months PER (fully taxed)25.020.0 16.2 -1% + 4% +32%Yield % 2.0% 2.4% 2.5% Summary Pre-tax profits were in line with expectations at to do so until the cash flow generated by the new £7.73m, an increase of 14%over the previous stores outweighs the level of capital expenditure period. A fall in the tax rate from34% to 22% due to (in three to four years time). However, current capital spending gave strong growth at the trading is benefiting from the end of the miners' earnings level. EPS were up 34% to 24.4p. The strike and improvements in productivity and results show that the business held up well during product mix can be expected. the miners' strike and actually managed to increase margins despite a slight fall in volume through Our forecast for the 53 weeks to 3rd May 1986 existing stores. shows a 13%improvement in profits to £8.7m but with a tax charge rising to at least28% EPS growth The future is dominated by the physical will be limited to around4%. The prospective PER expansion programme. In the recent past thereof13.5 is fairly demanding given the competitive have been one or two openings per annum. Plans market in the Yorkshire area, but the share price step this to three stores are to up to two a year in the tends to move as much on bid speculation as on future but in the current period four large, new fundamentals. A resurgence of such rumours stores will be opened. Thus profits growth will be could provide a good selling opportunity since at a restrained this year by increased opening costs price around the recent high Hillards would seem although these will reduce in subsequent years. to be an expensive acquisition for any company Interest charges will also rise sharply and continue after building in any premium. = ! | Analyst Liz Crozier | HOARE GOVETT