Interim Accounts 28 Weeks Ended 10/11/1984 page 2 of 3 previous next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
r


                            -            2   -

    Capital    Expenditure in            the     28  weeks   to  November     198^1 has
    been  £1.7ni     on        Rotherham     amd  £1.9m on    Scunthorpe,     Scarborough,
    Brownhills       and     Thornton        Cleveleys    and   £0.95m    on  other fixed
    assets;     property           sales     (£0.3ni).

    'New     Store'     as       defined     at  1.2   above,   performance    has   been
      (figures  taken        from        monthly  accounts):-

    28   weeks  to     10    November        198^

    Rotherham        trading                                     (89.2)   loss   contribution
    Rotherham        pre-opening         costs                    (167.^) loss   contribution
    Ilkley           trading                                     1 13.8
    Edenthorpe       store      and  petrol       trading        1 17.9

                                                                 (2i| .9)

    28   weeks  to     12    November        1983

    Ilkley        trading                                         8.i|
    Ilkley    pre-opening           costs                        (87.9)   loss   contribution
    Edenthorpe       pre-opening         costs                    (128.8) loss   contribution

                                                                  (208.3)

    The   taxation  charge          has      been    prepared   assuming  £7.8m     net profit
    for   the  year,          allowable      capital     allowances   of £2.07m on     fixture
    replacement      and         building    costs    tax      allowances                  and on Rotherham
    Scunthorpe       of £3.06m.

    The   interim  dividend          has     been     brought   in at  1 .65p,   an   increase
    of   13.8%  which        percentage,         when applied    to   the dividend     for
    the   full  year,        would   give      a  total   of 5.52p    (4.85p    last  year).
     (At  £7.8m post         profit    share, the     increase      in    profits   will  be
    15.-4%).

    Gazenove    feel that                  basically dividend   growth    should  be  in  line
    with  profits       pre    tax   growth       but feel    that  a   higher   rate of
    dividend    could        be        justified  if  the  development    of new    stores
    was   seen  to be        likely    to    produce    a  higher     compound   growth
    rate  over   the next        four/five          years.

    They  also    point      out     that    reducing     the   dividend   now   and
    increasing       it     within   a   short      time  on  the    occasion   of a
    subsequent       take     over   bid,       would appear    rather    odd  and   would
    weaken     that  line       of defence.


                                                                 cont'd   over
r - 2 - Capital Expenditure in the 28 weeks to November198^1 has been £1.7ni on Rotherham amd £1.9m on Scunthorpe, Scarborough, Brownhills and Thornton Cleveleys and £0.95m on other fixed assets; property sales (£0.3ni). 'New Store' as defined at 1.2above, performance has been (figures taken from monthly accounts):- 28 weeks to 10November198^ Rotherham trading(89.2) loss contribution Rotherham pre-opening costs(167.^) loss contribution Ilkley trading113.8 Edenthorpe store and petrol trading117.9 (2i| .9) 28 weeks to 12November1983 Ilkley trading 8.i| Ilkley pre-opening costs(87.9) loss contribution Edenthorpe pre-opening costs(128.8) loss contribution (208.3) The taxation charge has been prepared assuming £7.8m net profit for the year, allowable capital allowances of £2.07m on fixture replacement and building costs tax allowances and on Rotherham Scunthorpe of £3.06m. The interim dividend has been brought in at 1 .65p, an increase of 13.8%which percentage, when applied to the dividend for the full year, would give a total of 5.52p (4.85p last year). (At £7.8m post profit share, the increase in profits will be 15.-4%). Gazenove feel that basically dividend growth should be in line with profits pre tax growth but feel that a higher rate of dividend could be justified if the development of new stores was seen to be likely to produce a higher compound growth rate over the next four/five years. They also point out that reducing the dividend now and increasing it within a short time on the occasion of a subsequent take over bid, would appear rather odd and would weaken that line of defence. cont'd over
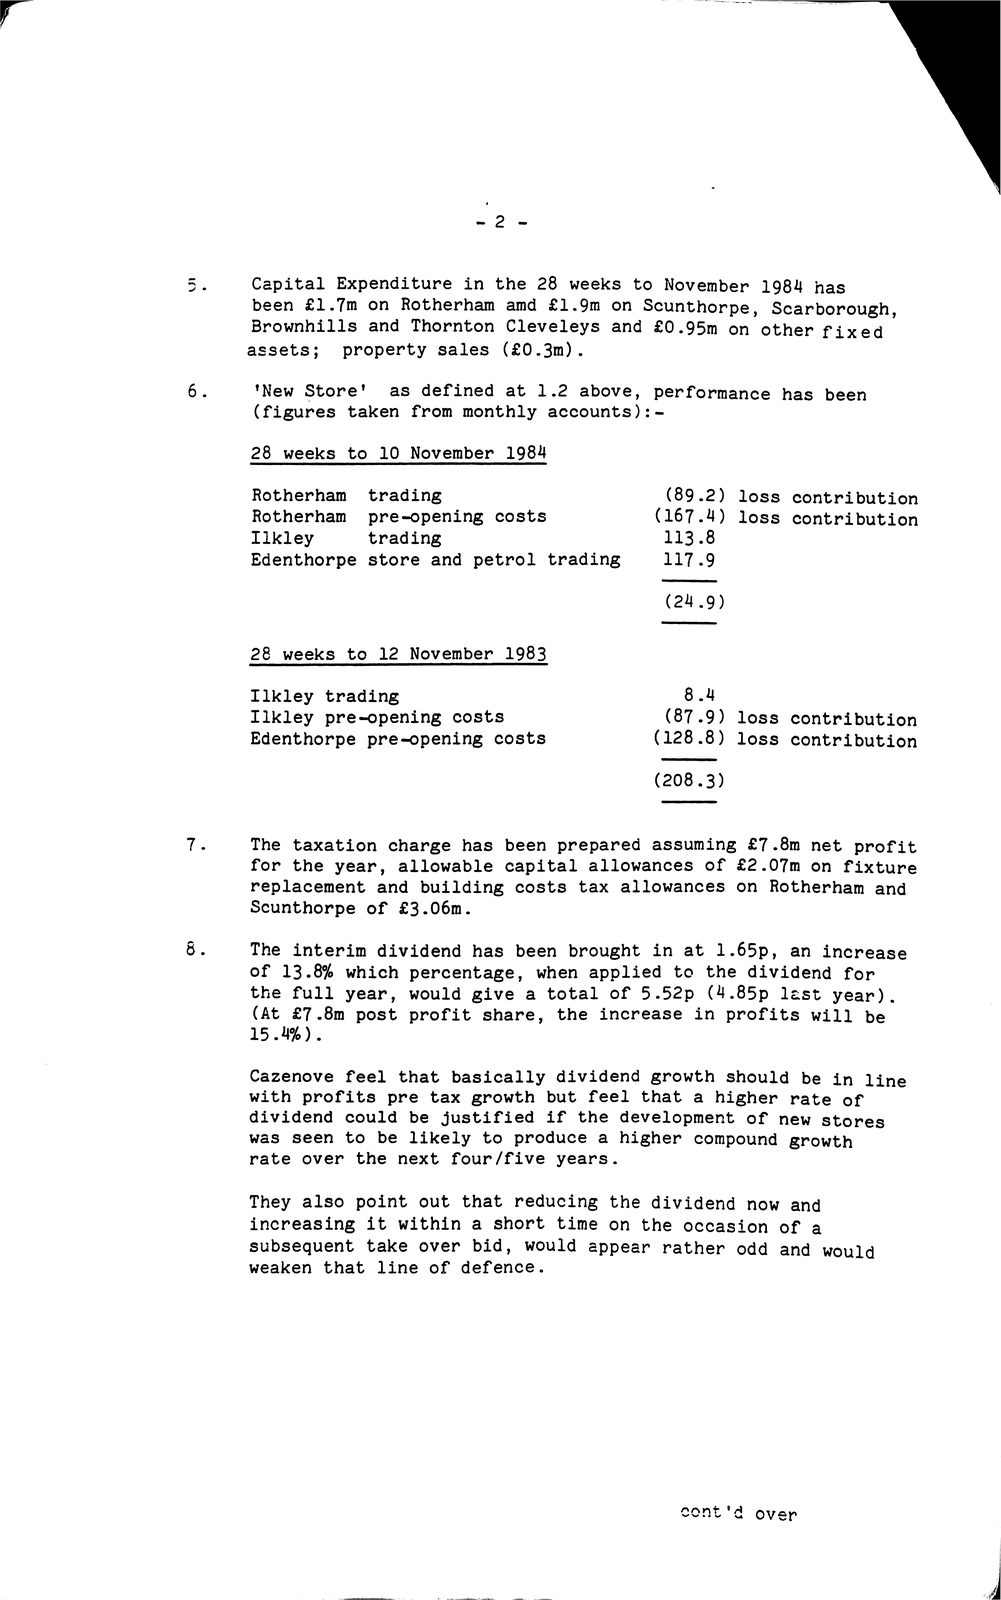
Read by machine highest quality of the three
    -2-


    wi   Capital     Expenditure     in   the    28  weeks    to  November   1984  has
         been  £1.7m        on  Rotherham   amd      £1.9m on Scunthorpe,    Scarborough,
         Brownhills         and  Thornton   Cleveleys     and    £0.95m   on other fixed
        assets;     property     sales      (£0.3m).

        "New   Store'          as defined   at   1.2 above,      performance   has been
        (figures           taken    from monthly     accounts):-

         28           to                     1984
                        weeks 10 November

         Rotherham          trading                                (89.2)  loss  contribution
         Rotherham          pre-opening     costs                (167.4)   loss  contribution
         Ilkley             trading                               113.8
         Edenthorpe         store   and  petrol      trading      117.9

                                                                  (24.9)

         28    weeks  to      12    November 1983

         Ilkley          trading                                    8.4
         Ilkley    pre-opening     costs                          (87.9)   loss  contribution
         Edenthorpe         pre-opening     costs                (128.8)   loss  contribution

                                                                 208   .3


The taxation charge has been prepared assuming £7.8m net profit
    for       the  year,       allowable    capital       allowances  of  £2.07m   on fixture
    replacement             and  building     costs    tax  allowances    on  Rotherham  and
    Scunthorpe         of      £3.06m.

    The       interim       dividend    has   been   brought    in at   1.65p,  an  increase
    of       13.8%  which       percentage,     when  applied     to  the  dividend   for
    the       full  year,       would   give  a  total     of  5.52p  (4.85p   lest   year).
         (At  £7.8m  post       profit    share,     the  increase   in  profits   will  be
    15.4%).

Cazenove feel that basically dividend growth should be in line
    with     profits        pre    tax  growth   but     feel that   a  higher  rate  of
    dividend        could       be    justified  if    the  development    of  new  stores
    was       seen  to      be  likely    to  produce    a  higher    compound  growth
    rate     over the          next four/five        years.

They also point out that reducing the dividend now and
    increasing         it      within   a short      time  on the  occasion    of  a
    subsequent         take     over    bid,  would      appear  rather   odd  and  would
    weaken        that      line of    defence.
-2- wi Capital Expenditure in the 28 weeks to November1984 has been £1.7m on Rotherham amd £1.9m on Scunthorpe, Scarborough, Brownhills and Thornton Cleveleys and £0.95m on other fixed assets; property sales (£0.3m). "New Store' as defined at 1.2above, performance has been (figures taken from monthly accounts):- 28 to 1984 weeks 10 November Rotherham trading(89.2) loss contribution Rotherham pre-opening costs(167.4) loss contribution Ilkley trading113.8 Edenthorpe store and petrol trading117.9 (24.9) 28 weeks to 12November1983 Ilkley trading8.4 Ilkley pre-opening costs(87.9) loss contribution Edenthorpe pre-opening costs(128.8) loss contribution 208 .3 The taxation charge has been prepared assuming £7.8m net profit for the year, allowable capital allowances of £2.07m on fixture replacement and building costs tax allowances on Rotherham and Scunthorpe of £3.06m. The interim dividend has been brought in at 1.65p, an increase of 13.8%which percentage, when applied to the dividend for the full year, would give a total of 5.52p (4.85p lest year). (At £7.8m post profit share, the increase in profits will be 15.4%). Cazenove feel that basically dividend growth should be in line with profits pre tax growth but feel that a higher rate of dividend could be justified if the development of new stores was seen to be likely to produce a higher compound growth rate over the next four/five years. They also point out that reducing the dividend now and increasing it within a short time on the occasion of a subsequent take over bid, would appear rather odd and would weaken that line of defence.
Read by machine, contrast corrected
    -2-


    wi   Capital     Expenditure     in   the    28  weeks    to  November   1984  has
         been  £1.7m        on  Rotherham   amd      £1.9m on Scunthorpe,    Scarborough,
         Brownhills         and  Thornton   Cleveleys     and    £0.95m   on other fixed
        assets;     property     sales      (£0.3m).

        "New   Store'          as defined   at   1.2 above,      performance   has been
        (figures           taken    from monthly     accounts):-

         28           to                     1984
                        weeks 10 November

         Rotherham          trading                                (89.2)  loss  contribution
         Rotherham          pre-opening     costs                (167.4)   loss  contribution
         Ilkley             trading                               113.8
         Edenthorpe         store   and  petrol      trading      117.9

                                                                  (24.9)

         28    weeks  to      12    November 1983

         Ilkley          trading                                    8.4
         Ilkley    pre-opening     costs                          (87.9)   loss  contribution
         Edenthorpe         pre-opening     costs                (128.8)   loss  contribution

                                                                 208   .3


The taxation charge has been prepared assuming £7.8m net profit
    for       the  year,       allowable    capital       allowances  of  £2.07m   on fixture
    replacement             and  building     costs    tax  allowances    on  Rotherham  and
    Scunthorpe         of      £3.06m.

    The       interim       dividend    has   been   brought    in at   1.65p,  an  increase
    of       13.8%  which       percentage,     when  applied     to  the  dividend   for
    the       full  year,       would   give  a  total     of  5.52p  (4.85p   lest   year).
         (At  £7.8m  post       profit    share,     the  increase   in  profits   will  be
    15.4%).

Cazenove feel that basically dividend growth should be in line
    with     profits        pre    tax  growth   but     feel that   a  higher  rate  of
    dividend        could       be    justified  if    the  development    of  new  stores
    was       seen  to      be  likely    to  produce    a  higher    compound  growth
    rate     over the          next four/five        years.

They also point out that reducing the dividend now and
    increasing         it      within   a short      time  on the  occasion    of  a
    subsequent         take     over    bid,  would      appear  rather   odd  and  would
    weaken        that      line of    defence.
-2- wi Capital Expenditure in the 28 weeks to November1984 has been £1.7m on Rotherham amd £1.9m on Scunthorpe, Scarborough, Brownhills and Thornton Cleveleys and £0.95m on other fixed assets; property sales (£0.3m). "New Store' as defined at 1.2above, performance has been (figures taken from monthly accounts):- 28 to 1984 weeks 10 November Rotherham trading(89.2) loss contribution Rotherham pre-opening costs(167.4) loss contribution Ilkley trading113.8 Edenthorpe store and petrol trading117.9 (24.9) 28 weeks to 12November1983 Ilkley trading8.4 Ilkley pre-opening costs(87.9) loss contribution Edenthorpe pre-opening costs(128.8) loss contribution 208 .3 The taxation charge has been prepared assuming £7.8m net profit for the year, allowable capital allowances of £2.07m on fixture replacement and building costs tax allowances on Rotherham and Scunthorpe of £3.06m. The interim dividend has been brought in at 1.65p, an increase of 13.8%which percentage, when applied to the dividend for the full year, would give a total of 5.52p (4.85p lest year). (At £7.8m post profit share, the increase in profits will be 15.4%). Cazenove feel that basically dividend growth should be in line with profits pre tax growth but feel that a higher rate of dividend could be justified if the development of new stores was seen to be likely to produce a higher compound growth rate over the next four/five years. They also point out that reducing the dividend now and increasing it within a short time on the occasion of a subsequent take over bid, would appear rather odd and would weaken that line of defence.