Company News Final Results 1985 page 1 of 2 next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
    '   .-ii

        V'i ••
•tl'-v'.


       Year  Pre-tax                                    Tax        E.P.S.              Gross         Dividend           P/E     Gross
       -end                     profit                 rale   actual                   div.           cover     ratio                 yield
       Dec.                       (£m)              (%)         (P)                       (P)             HCA                         (%)
       1983                        6.8                   34    18.2                       6.9             3.8
       1984                        7.7                   23    24.4                       8.3             4.2           14.2          2.4
       1985 E                      8.3                   30    24.0                       9.1             3.8           14.4          2.6
       1986 E                      9.3                   35    24.7                    10.1               3.5           14.0          2.9
       Market capitalisation: £85m                   Net borrowing/equity: 24%                               5-year div. growth rate: 22%
       Results dates: January & July                PER relative to 500 Index:              127       Yield relative to All-Share: 5 1

    Price (12       month range): 346p (413p-202p)                             New Stores Development
    Recommendation: HOLD
    1985/86 will be a year of consolidation as the                             After only one opening last year Hillards plan to                      IP  m
    opening costs of 4 new stores and a rising tax                             open 4 stores in       1985/86, adding          115,000 sq. ft.
    charge        will    remove       ail  earnings          growth.          or                 18% to net selling area. Scunthorpe has just
    1986/87 will be      more exciting as                   these new          opened and the other three will              follow      around
    stores     begin     to           make profits   but       rising          the end of this half year. One of these, Lincoln,
    interest        costs and          tax  charge   will       again          is                a resite. The refurbishment programme is also
    reduce the impact at the earnings level.                       On          continuing.     Five     stores     have         now been done,
    this rating        there    is little   to  go   for       except          with encouraging results. Three more are being
    fuilher bid speculation.                                                   considered and two large stores have also been
                                                                               identified     as  candidates.     This  will    be the   first
    Share price relative to All-Share Index                                    time a larger store has been refurbished and will
    1 month              3 months                           12 months          allow them to up-grade it to the standard of new
   -3%                            +5%                    +33%                  openings.                                                              icL!
    RESULTS
    A 1 for     1 capitalisation issue is             proposed.                After the four openings this year, one store will
                                                                               definitely     open    in   1986/7       and     they    appear
    Hillards have reported a                      14% increase in pre-tax      optimistic     for     at   least   one      more.       Having
    profits on a                       10% sales gain. However the figure      achieved       a  rate   of only    two   new    stores     per        m§
    includes      a  profit     after     redundancy     costs        and      annum over         the   last     five years     they hope   to
    other expenses ol           £235,000 relating to             the sale      increase the       rate to three             per annum over the
    of      the Peterborough           store.         Excluding      such      next    5    years. Surprisingly,         perhaps,        there
    profits the increase is only 9% to              £7.5m.                     appears to be no problem in obtaining sufficient
    The  sales          increase  of 10%      came         4.4%      from      sites   at   the        moment    even   when       having   to
    inflation,                                                                 compete with the superior financial                        power of
                         7% from  new stores     and     a         volume      the majors.
    decline       of       about   1%.      This    decline           was
    concentrated       in   mining     areas in     the     first   half,
    and by the second half it                      had levelled out. Only      This    expansion         plan    is,  however,        imposing
    one  store      opened     last     year, at    Rotherham          in      strains        on  Hillards     cash      flow.             Capital
    September, and          that is     the principal          reason for      expenditure was £11.6m. last year and led to a
    the slowdown in sales in the second half.                                  cash outflow of £2.6m. This year's expenditure
    Margins       rose    again last       year  in  spite of         the      will    be                   between £13m and £16m. Again there
    volume decline. Lack of opening expenses was                               will    be a     cash  outflow     but   they    will  still be
    one reason, the other main- positive factor was                            comfortably within          the     facilities   negotiated      at
    further       gains   in      productivity       which           they                        the beginning of this expansion programme and
    estimate      improved by over                          1%. Gross margins  which      should     be adequate     for    the next         three    lA-'
    fell in     the first               half but rose again in the second      years .    A rights    issue     is not expected and       it    is        •',V
    since when they have held their higher level in                            worth pointing out that it is possible to                  identify    '
    spite of    Asda's promotional activity.                                    family    holdings of 17% in the accounts alone.
    Analyst: Richard Perks                               All-Share Index: 603.26                                                   22nd July, 1985     •  P-v


                                   rrdephb.ne; Oi -906,p622' .''ropfc Equity                      l-'aqcs: .iG05()-26ob9
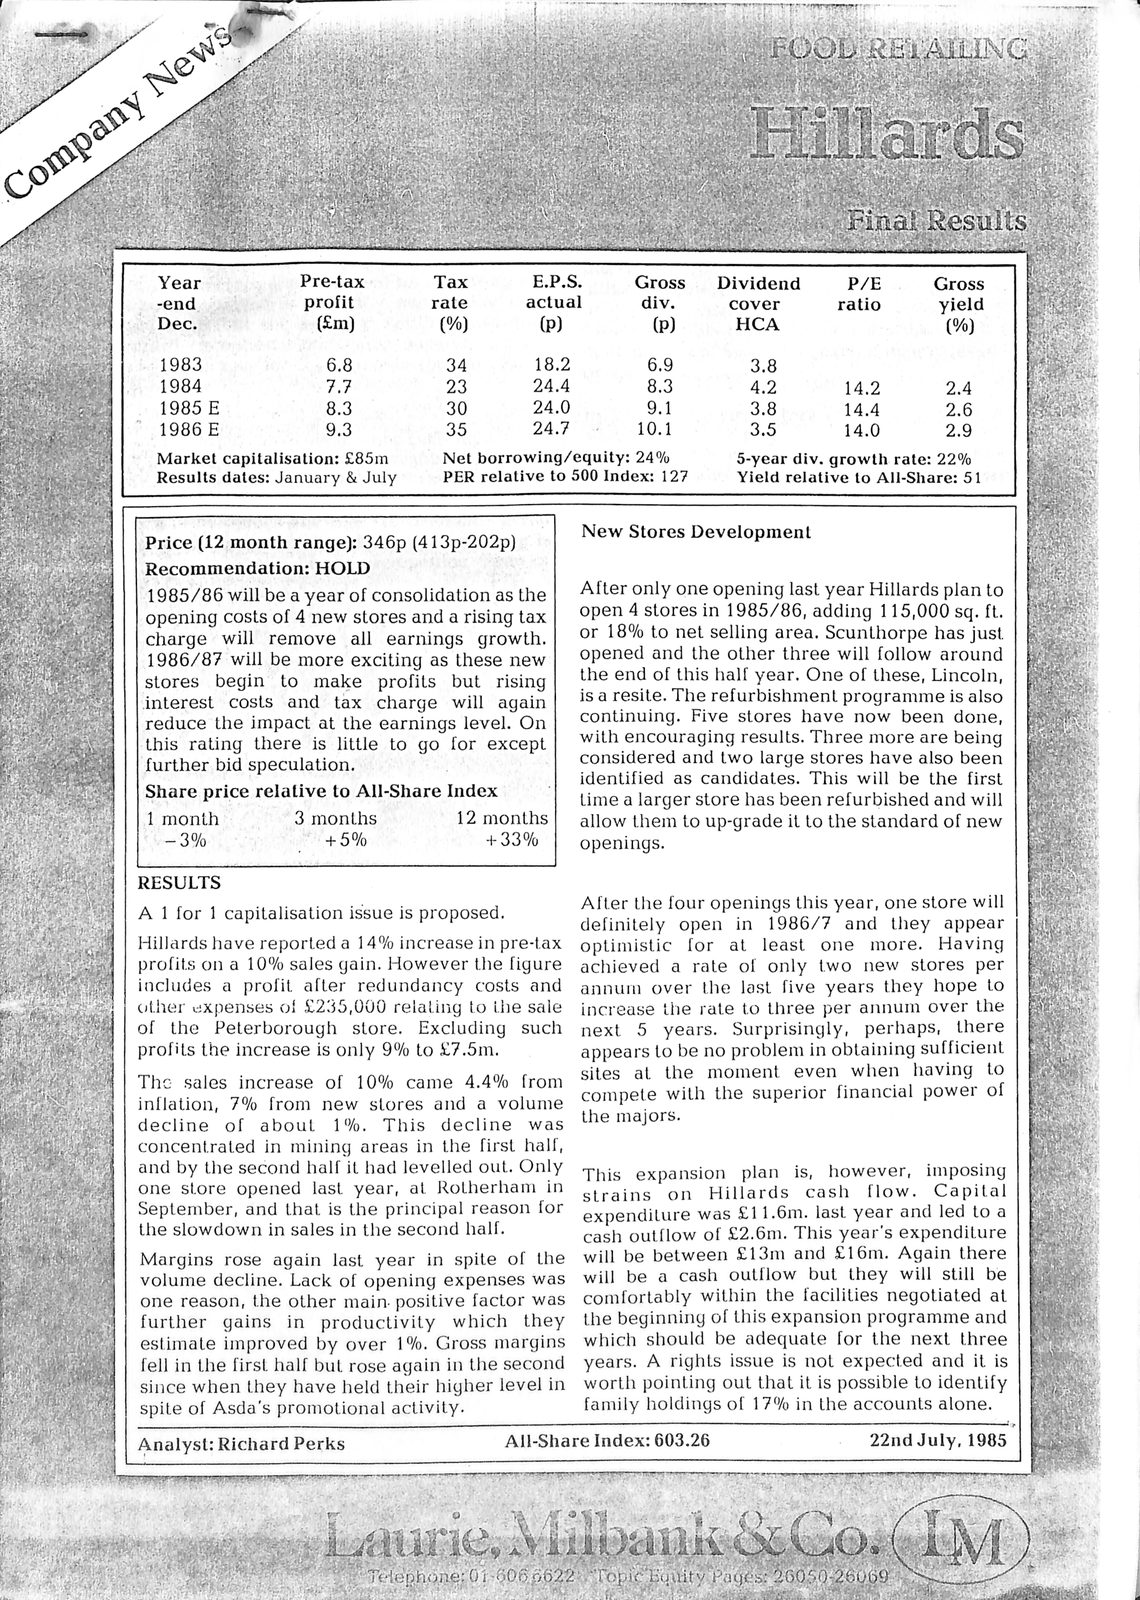
' .-ii V'i •• •tl'-v'. Year Pre-tax Tax E.P.S. Gross Dividend P/E Gross -end profit rale actual div. cover ratio yield Dec. (£m) (%) (P) (P) HCA (%) 1983 6.8 34 18.2 6.9 3.8 1984 7.7 23 24.4 8.3 4.2 14.2 2.4 1985 E 8.3 30 24.0 9.1 3.8 14.4 2.6 1986 E 9.3 35 24.7 10.1 3.5 14.0 2.9 Market capitalisation: £85m Net borrowing/equity: 24%5-year div. growth rate:22% Results dates: January & July PER relative to 500Index:127 Yield relative to All-Share: 5 1 Price(12 month range): 346p (413p-202p) New Stores Development Recommendation: HOLD 1985/86will be a year of consolidation as the After only one opening last year Hillards plan to IP m opening costs of 4 new stores and a rising tax open 4 stores in 1985/86,adding115,000 sq. ft. charge will remove ail earnings growth. or 18% to net selling area. Scunthorpe has just 1986/87will be more exciting as these new opened and the other three will follow around stores begin to make profits but rising the end of this half year. One of these, Lincoln, interest costs and tax charge will again is a resite. The refurbishment programme is also reduce the impact at the earnings level. On continuing. Five stores have now been done, this rating there is little to go for except with encouraging results. Three more are being fuilher bid speculation. considered and two large stores have also been identified as candidates. This will be the first Share price relative to All-Share Index time a larger store has been refurbished and will 1 month 3 months 12 months allow them to up-grade it to the standard of new -3% +5%+33%openings. icL! RESULTS A 1 for 1 capitalisation issue is proposed. After the four openings this year, one store will definitely open in 1986/7 and they appear Hillards have reported a 14%increase in pre-tax optimistic for at least one more. Having profits on a 10%sales gain. However the figure achieved a rate of only two new stores per m§ includes a profit after redundancy costs and annum over the last five years they hope to other expenses ol £235,000relating to the sale increase the rate to three per annum over the of the Peterborough store. Excluding such next 5 years. Surprisingly, perhaps, there profits the increase is only 9% to £7.5m. appears to be no problem in obtaining sufficient The sales increase of 10%came4.4% from sites at the moment even when having to inflation, compete with the superior financial power of 7% from new stores and a volume the majors. decline of about1%. This decline was concentrated in mining areas in the first half, and by the second half it had levelled out. Only This expansion plan is, however, imposing one store opened last year, at Rotherham in strains on Hillards cash flow. Capital September, and that is the principal reason for expenditure was £11.6m. last year and led to a the slowdown in sales in the second half. cash outflow of £2.6m. This year's expenditure Margins rose again last year in spite of the will be between £13m and £16m. Again there volume decline. Lack of opening expenses was will be a cash outflow but they will still be one reason, the other main- positive factor was comfortably within the facilities negotiated at further gains in productivity which they the beginning of this expansion programme and estimate improved by over1%. Gross margins which should be adequate for the next three lA-' fell in the first half but rose again in the second years . A rights issue is not expected and it is •',V since when they have held their higher level in worth pointing out that it is possible to identify ' spite of Asda's promotional activity. family holdings of 17% in the accounts alone. Analyst: Richard Perks All-Share Index:603.26 22nd July,1985• P-v rrdephb.ne; Oi -906,p622' .''ropfc Equity l-'aqcs: .iG05()-26ob9
Read by machine
    Pre-tax                    Tax    E.P.S.      Gross     Dividend
-end        profit            rate        actual  div.     cover      ratio
              (£m)             (%)     (p)            (p)        HCA

1983       6.8                  34    18.2        6.9           3.8
1984       77                   23    24.4         8.3          4.2    14.2
1985 E     8.3                  30    24.0         9.1          3.8    14.4
1986E      9.3                  35    24.7             10.1     3.5    14.0
Market capitalisation: £85m  Net      borrowing/equity: 24%      5-year div. growth rate: 22%
Results dates: January & July   PER relative to 500 Index: 127   Yield relative to All-Share: 51


Price 12 month range): 346p      (413p-202p)                        New Stores Development
Recommendation: HOLD
1985/86 will be   a  year    of consolidation     as the            After only   one     opening last   year Hillards   plan to
opening costs of 4     new   stores and     a rising tax            open    4 stores in    1985/86, adding     115,000  sq. ft.
charge     will  remove      all  earnings       growth.            or 18% to    net     selling  area.     Scunthorpe has just
1986/87 will be   more       exciting    as   these  new            opened and the other three will follow               around
stores   begin    to   make        profits   but  rising            the end of this half      year.      One of these, Lincoln,
interest   costs  and  tax          charge   will  again            is a resite. The refurbishment        programme     is also
reduce the impact at the earnings level.              On            continuing.     Five   stores   have    now  been     done,
this     rating there  is little  to     go  for  except            with encouraging results. Three         more are      being
    speculation.                                                    identified
further bid                                                         considered and two large stores have also been
Share price        to All-Share Index                               lime            as candidates.  This will    be the   first
                                                                         a           larger store has been refurbished and will
1  month      3 months                        12 months             allow them to up-grade it to the standard of            new
   —3%         +     5%                                             openings.

RESULTS
A 1  for  1 capitalisation   issue is proposed.                     After the four openings this        year, one   store  will
                                                                    definitely   open     in     1986/7   and    they    appear
Hillards have reporteda 14% increase in pre-tax                     optimistic   for     at     least   one  more.       Having
profits  on a   10% sales           gain. However the figure        achieved     a     rate  of  only   two  new stores     per
includes    a   profit after        redundancy   costs   and        annum over     the       last five  years    they hope   to
other expenses    of         £235,000 relating  to  the sale        increase       the rate   to three  per annum     over  the
of   the    Peterborough     store.     Excluding       such        next    5    years.     Surprisingly,    perhaps,     there
profits the increase is only 9%     to £7.5m.                       appears      to be no   problem in obtaining     sufficient
The   sales   increase    of 10%    came       4.4%     from        sites    al  the   moment     even      when    having   to
inflation,  7%   from  new      stores   and     a        volume    compete      with     the superior    financial   power  of
decline     of  about 1%.        This       decline      was        the majors.
concentrated     in mining   areas     in   the  first half,
and by the second half it had levelled out. Only                     This   expansion         plan  is, however,       imposing
one  store    opened   last  year,   al     Rotherham     in         strains        on     Hillards   cash   flow.      Capital
September, and that is the principal            reason   for         expendilure     was    £11.6m. last    year and led   to a
the slowdown in sales in the second half.                            cash outflow     of £2.6m. This         year’s expenditure
Margins     rose  again last        in        spite of       the     will   be   between             £13m and £16m. Again there
volume decline. Lack             year                                will   be   a               but        they will still  be
                         of        opening          expenses was                   cash     outflow
one  reason,    the other main. positive        factor       was     comfortably within          the  facilities negotiated   at
further     gains   in        productivity    which         they     the         beginning of this expansion programme      and
estimate    improved by      over 1%.              Gross margins     which     should     be  adequate   for the next   three
fell in the first half but   rose again in the            second     years.    A rights     issue  is not expected    and it  is
since when they have held their higher           level in            worth pointing out that it is possible to identify
spite of Asda’s promotional activity.                                family holdings of       17% in the accounts alone.
Analyst: Richard Perks                                         All-Share Index:  603.26                     22nd July,
Pre-tax Tax E.P.S. Gross Dividend -end profit rate actual div. cover ratio (£m) (%) (p) (p) HCA 1983 6.8 34 18.2 6.9 3.8 1984 77 23 24.4 8.3 4.2 14.2 1985 E 8.3 30 24.0 9.1 3.8 14.4 1986E 9.3 35 24.7 10.1 3.5 14.0 Market capitalisation: £85m Net borrowing/equity: 24%5-year div. growth rate:22% Results dates: January & July PER relative to 500Index:127 Yield relative to All-Share: 51 Price 12 month range): 346p (413p-202p) New Stores Development Recommendation: HOLD 1985/86will be a year of consolidation as the After only one opening last year Hillards plan to opening costs of 4 new stores and a rising tax open 4 stores in 1985/86,adding115,000 sq. ft. charge will remove all earnings growth. or 18% to net selling area. Scunthorpe has just 1986/87will be more exciting as these new opened and the other three will follow around stores begin to make profits but rising the end of this half year. One of these, Lincoln, interest costs and tax charge will again is a resite. The refurbishment programme is also reduce the impact at the earnings level. On continuing. Five stores have now been done, this rating there is little to go for except with encouraging results. Three more are being speculation. identified further bid considered and two large stores have also been Share price to All-Share Index lime as candidates. This will be the first a larger store has been refurbished and will 1 month 3 months 12 months allow them to up-grade it to the standard of new -3% + 5% openings. RESULTS A 1 for 1 capitalisation issue is proposed. After the four openings this year, one store will definitely open in 1986/7 and they appear Hillards have reporteda 14%increase in pre-tax optimistic for at least one more. Having profits on a 10%sales gain. However the figure achieved a rate of only two new stores per includes a profit after redundancy costs and annum over the last five years they hope to other expenses of £235,000relating to the sale increase the rate to three per annum over the of the Peterborough store. Excluding such next 5 years. Surprisingly, perhaps, there profits the increase is only 9% to £7.5m. appears to be no problem in obtaining sufficient The sales increase of 10%came4.4% from sites al the moment even when having to inflation, 7% from new stores and a volume compete with the superior financial power of decline of about1%. This decline was the majors. concentrated in mining areas in the first half, and by the second half it had levelled out. Only This expansion plan is, however, imposing one store opened last year, al Rotherham in strains on Hillards cash flow. Capital September, and that is the principal reason for expendilure was £11.6m. last year and led to a the slowdown in sales in the second half. cash outflow of £2.6m. This year's expenditure Margins rose again last in spite of the will be between £13m and £16m. Again there volume decline. Lack year will be a but they will still be of opening expenses was cash outflow one reason, the other main. positive factor was comfortably within the facilities negotiated at further gains in productivity which they the beginning of this expansion programme and estimate improved by over1%. Gross margins which should be adequate for the next three fell in the first half but rose again in the second years. A rights issue is not expected and it is since when they have held their higher level in worth pointing out that it is possible to identify spite of Asda's promotional activity. family holdings of 17% in the accounts alone. Analyst: Richard Perks All-Share Index:603.26 22nd July,
Read by machine, contrast corrected highest quality of the three
    Pre-tax                         E.P.S.        Gross     Dividend
-end        profit                        actual  div.     cover      ratio
Dec.          (£m)    (p)                               (p)      HCA

1983       6.8       18.2                           6.9         3.8
1984       77        24.4                          8.3          4.2    14,2
1985 E     8.3       24.0                          9.1          3.8    14.4
           9.3       24.7                              10.1     3.5    14.0
Market capitalisation: £85m     Net   borrowing/equity: 24%      5-year div. growth rate: 22%    ea
Results dates: January & July   PER relative to 500 Index: 127   Yield relative to All-Share: 51


Price 12 month range): 346p      (413p-202p)                        New Stores Development
Recommendation: HOLD
1985/86 will be   a year     of consolidation     as the            After only   one     opening last   year Hillards   plan to    a
opening costs of 4     new   stores and     a rising tax            open    4 stores in    1985/86, adding     115,000  sq. ft.
charge     will  remove      all  earnings       growth.            or 18% to    net     selling  area.     Scunthorpe has just
1986/87 will be   more       exciting    as   these  new            opened and the other three will follow               around
stores   begin    to   make        profits   but  rising            the end of this half      year.      One of these, Lincoln,
interest   costs  and  tax          charge   will  again            is a resite. The refurbishment        programme     is also
reduce the impact at the earnings level.              On            continuing.     Five   stores   have    now  been     done,
this     rating  there is little  to     go  for  except            with encouraging results. Three         more are      being
    speculation.                                                    identified
further bid                                                         considered and two large stores have also been
Share price        to All-Share Index                               lime            as candidates.  This will    be the   first
                                                                         a           larger store has been refurbished and will
1  month      3 months                        12 months             allow them to up-grade it to the standard of            new
   —3%                                                              openings.

RESULTS
A 1  for  1 capitalisation   issue is proposed.                     After the four openings this        year, one   store  will
                                                                    definitely   open     in     1986/7   and    they        appear
Hillards have                        14% increase in pre-tax        optimistic   for     at     least   one  more.       Having
profits  on a   10% sales           gain. However the figure        achieved     a     rate  of  only   two  new stores         per
includes    a   profit after        redundancy   costs   and        annum over     the       last five  years    they hope       to
other expenses    of         £235,000 relating  to  the sale        increase       the rate   to three  per annum     over  the
of   the    Peterborough     store.     Excluding       such        next      5  years.     Surprisingly,    perhaps,     there
profits the increase is only 9%     to £7.5m.                       appears      to be no   problem in obtaining     sufficient
The   sales   increase    of 10%    came       4.4%     from        sites    al  the   moment     even      when    having       to
inflation,  7%   from  new      stores   and     a        volume    compete      with     the superior    financial   power      of
decline     of   about 1%.       This       decline      was        the majors.
concentrated     in mining   areas     in   the  first half,
and by the second half it had levelled out. Only                     This   expansion         plan  is, however,           imposing
one  store    opened   last  year,   al     Rotherham     in         strains        on     Hillards   cash   flow.          Capital
September, and that is the principal            reason   for         expendilure     was    £11.6m. last    year and led   to     a
the slowdown in sales in the second half.                            cash outflow     of £2.6m. This             year’s expenditure
Margins     rose  again last        in        spite of       the     will   be   between                 £13m and £16m. Again there
volume decline. Lack             year                                will   be   a               but        they will still      be
                         of        opening          expenses was                   cash     outflow
one  reason,     the other main. positive       factor       was     comfortably within          the  facilities negotiated      at
further     gains    in       productivity    which         they     the         beginning of this expansion programme          and
estimate    improved by      over 1%.              Gross margins     which     should     be  adequate   for the next         three
fell in the first half but   rose again in the            second     years.    A rights     issue  is not expected    and it     is
since when they have held their higher           level in            worth pointing out that it is possible to identify
spite of Asda’s promotional activity.                                family holdings of       17% in the accounts alone.
Analyst: Richard Perks                                         All-Share Index:  603.26                             22nd July, 1985
Pre-tax E.P.S. Gross Dividend -end profit actual div. cover ratio Dec. (£m) (p) (p) HCA 1983 6.8 18.2 6.9 3.8 1984 77 24.4 8.3 4.2 14,2 1985 E 8.3 24.0 9.1 3.8 14.4 9.3 24.7 10.1 3.5 14.0 Market capitalisation: £85m Net borrowing/equity: 24%5-year div. growth rate:22% ea Results dates: January & July PER relative to 500Index:127 Yield relative to All-Share: 51 Price 12 month range): 346p (413p-202p) New Stores Development Recommendation: HOLD 1985/86will be a year of consolidation as the After only one opening last year Hillards plan to a opening costs of 4 new stores and a rising tax open 4 stores in 1985/86,adding115,000 sq. ft. charge will remove all earnings growth. or 18% to net selling area. Scunthorpe has just 1986/87will be more exciting as these new opened and the other three will follow around stores begin to make profits but rising the end of this half year. One of these, Lincoln, interest costs and tax charge will again is a resite. The refurbishment programme is also reduce the impact at the earnings level. On continuing. Five stores have now been done, this rating there is little to go for except with encouraging results. Three more are being speculation. identified further bid considered and two large stores have also been Share price to All-Share Index lime as candidates. This will be the first a larger store has been refurbished and will 1 month 3 months 12 months allow them to up-grade it to the standard of new -3%openings. RESULTS A 1 for 1 capitalisation issue is proposed. After the four openings this year, one store will definitely open in 1986/7 and they appear Hillards have14% increase in pre-tax optimistic for at least one more. Having profits on a 10%sales gain. However the figure achieved a rate of only two new stores per includes a profit after redundancy costs and annum over the last five years they hope to other expenses of £235,000relating to the sale increase the rate to three per annum over the of the Peterborough store. Excluding such next 5 years. Surprisingly, perhaps, there profits the increase is only 9% to £7.5m. appears to be no problem in obtaining sufficient The sales increase of 10%came4.4% from sites al the moment even when having to inflation, 7% from new stores and a volume compete with the superior financial power of decline of about1%. This decline was the majors. concentrated in mining areas in the first half, and by the second half it had levelled out. Only This expansion plan is, however, imposing one store opened last year, al Rotherham in strains on Hillards cash flow. Capital September, and that is the principal reason for expendilure was £11.6m. last year and led to a the slowdown in sales in the second half. cash outflow of £2.6m. This year's expenditure Margins rose again last in spite of the will be between £13m and £16m. Again there volume decline. Lack year will be a but they will still be of opening expenses was cash outflow one reason, the other main. positive factor was comfortably within the facilities negotiated at further gains in productivity which they the beginning of this expansion programme and estimate improved by over1%. Gross margins which should be adequate for the next three fell in the first half but rose again in the second years. A rights issue is not expected and it is since when they have held their higher level in worth pointing out that it is possible to identify spite of Asda's promotional activity. family holdings of 17% in the accounts alone. Analyst: Richard Perks All-Share Index:603.26 22nd July,1985