Comment on 1984/85 results page 4 of 4 previous
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan highest quality of the three
          that     the  new    store  investment    will     lead    to higher   cash flow    capable  of
          accomodating higher spending levels internally.              The company has stated that it has
          no present intention of making a rights issue, although we would assume that some
          kind of funding      exercise must remain a possibility over the next 1-2 years.
          1985/86 Profit Estimate
          The     We are forecasting a 16 per cent increase in pre-tax profits         to £9.0    million
          would    tax- charge is expected    to emerge    in   the 28-32  per cent range:    30 per cent
          gross)   produce    EPS    of 25.7p.    A pro-rata    dividend   increase  to 6.75p  net (9 64d
                    would thus be    covered 3.8 times.                                  *              ^
          Investment Appraisal
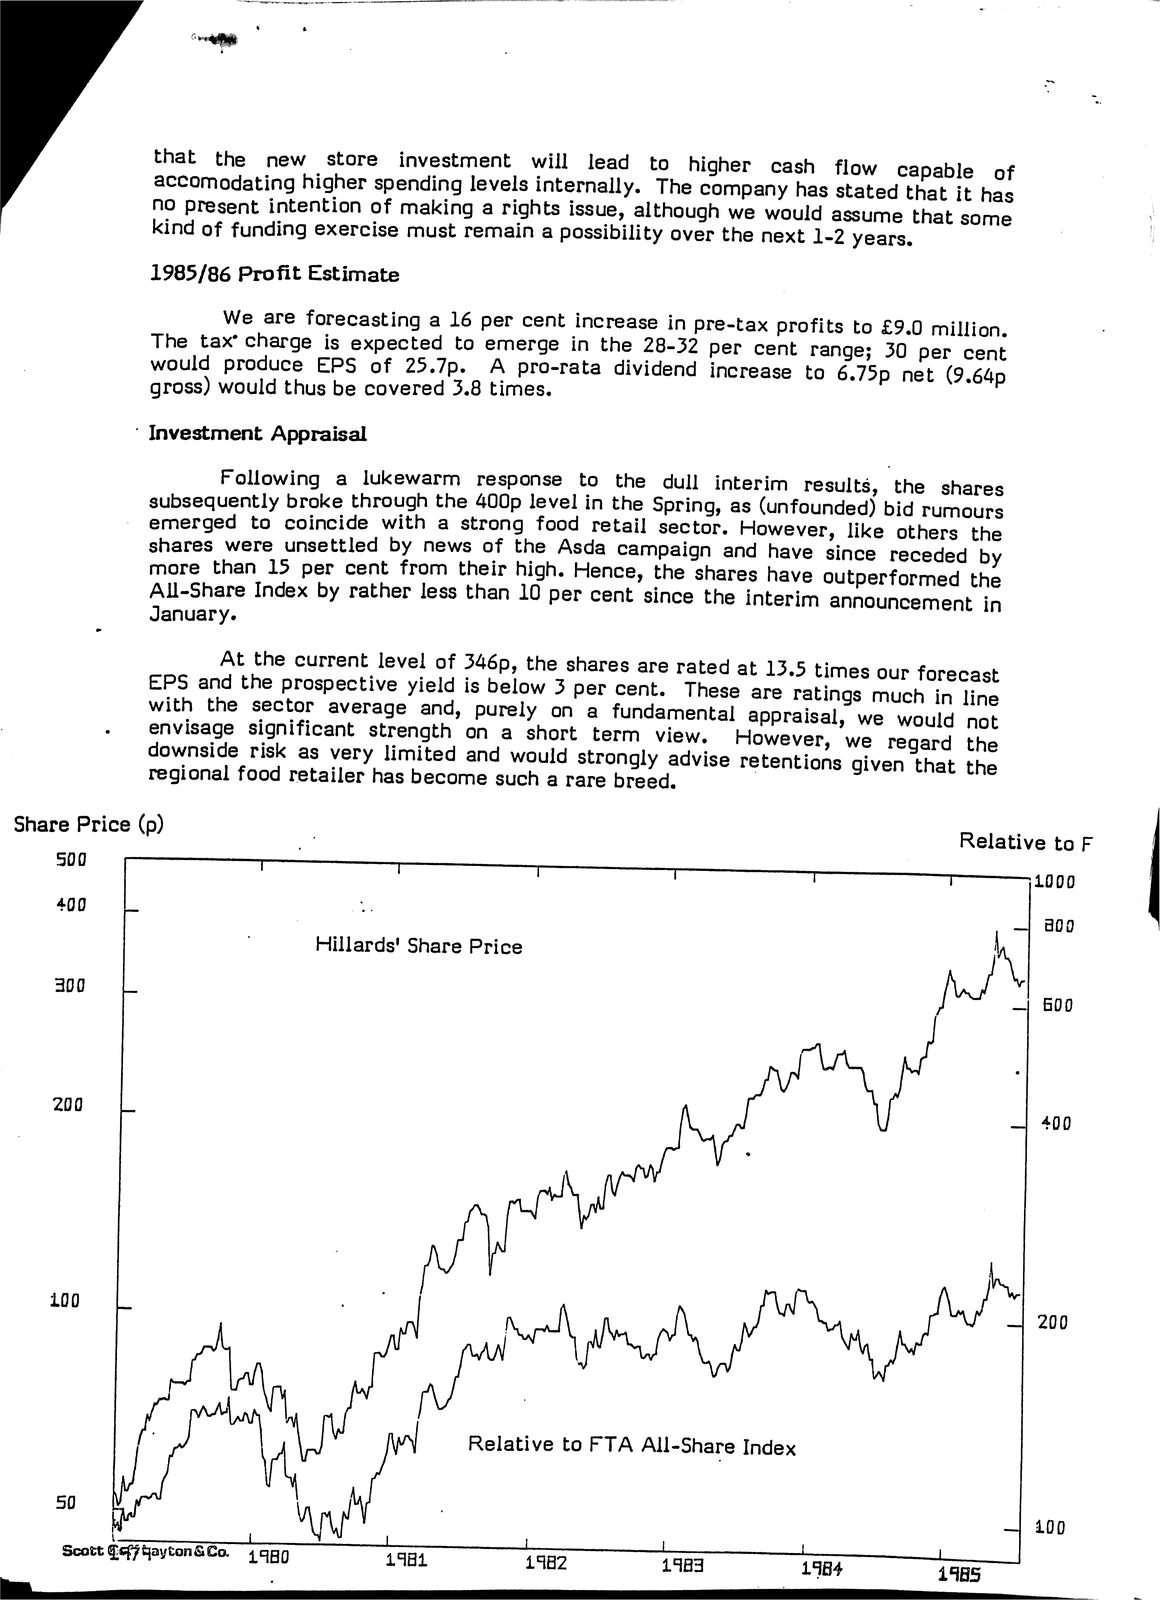
              Following        a   lukewarm    response     to  the  dull  interim   results, the  shares
          subsequently broke through the 400p level in the Spring,             as (unfounded) bid rumours
          emerged      to   coincide  with a strong    food   retail sector. However, like  others    the
          shares      were  unsettled by news of the Asda       campaign and     have since receded    bv
          more     than 15  per cent from     their high.  Hence,    the shares  have outperformed    the
          AU-Share Index by rather less than 10 per cent since          the interim       announcement in
          UaiiLlaF^•
          .roc              current level      Is   the shares              at 13   ratings
          with   the   «c or   average   and,  purely    on   a fundamental appraisal, we         wouW nM
          envisage     significant   strength  on   a short   term   view.  How^ever,  we         1^^ the
          downside     risk as very limited and     would strongly advise retentions   given     that  he
          regional food retailer has become       such a rare breed.
Share Price (p)                                                                          Relative
   500                                                                                                    to F

                               Hillards' Share Price

                                                                                                         - EOO


                                               Relative to FTA All-Share Index


   Scott(§|£^c]aytonaCa ^*=100
                                                                                 15B4  I'iBS
that the new store investment will lead to higher cash flow capable of accomodating higher spending levels internally. The company has stated that it has no present intention of making a rights issue, although we would assume that some kind of funding exercise must remain a possibility over the next1-2 years. 1985/86Profit Estimate The We are forecasting a 16 per cent increase in pre-tax profits to £9.0million would tax- charge is expected to emerge in the 28-32percent range: 30 per cent gross) produce EPS of 25.7p. A pro-rata dividend increase to 6.75p net (9 64d would thus be covered3.8 times. * ^ Investment Appraisal Following a lukewarm response to the dull interim results, the shares subsequently broke through the 400p level in the Spring, as (unfounded) bid rumours emerged to coincide with a strong food retail sector. However, like others the shares were unsettled by news of the Asda campaign and have since receded bv more than 15 per cent from their high. Hence, the shares have outperformed the AU-Share Index by rather less than 10 per cent since the interim announcement in UaiiLlaF^• .roc current level Is the shares at 13 ratings with the «c or average and, purely on a fundamental appraisal, we wouW nM envisage significant strength on a short term view. How^ever, we 1^^ the downside risk as very limited and would strongly advise retentions given that he regional food retailer has become such a rare breed. Share Price (p) Relative 500 to F Hillards' Share Price - EOO Relative to FTA All-Share Index Scott(§|£^c]aytonaCa ^*=100 15B4 I'iBS
Read by machine
             that   the      mew store      investment       will  lead    to  higher     cash     flow     capable of
             accomodating     higher   spending levels internally.         The     company   has   stated that   it
        no present intention of making a rights issue, although we would assume that has
             kind      of funding exercise    must remain    a possibility     over the  next 1-2  years.     some
             1985/86 Profit Estimate

                 We      are     forecasting  a 16   per     cent increase     in pre-tax profits  to     £9.0 million.
             The  tax’ charge    is expected    to   emerge     in     the   28-32  per cent    range;     30 per cent
             would  produce      EPS   of     25.7p. A        pro-rata    dividend  increase    to 6.75p   net (9.64p
             gross) would thus   be covered 3.8 times.

        ‘    Investment Appraisal

                 Following       a   lukewarm        response     to   the    dull  interim     results,   the shares
        subsequently broke through the 400p level in the Spring, as (unfounded) bid rumours
             emerged     to   coincide  with  a strong       food  retail  sector.      However,   like    others  the
             shares were      unsettled by    news   of  the   Asda    campaign     and   have     since   receded  by
             more   than 15   per   cent     from their  high.     Hence,  the    shares  have    outperformed     the
             All-Share Index by rather less than         10  per cent      since    the interim    announcement     in
             January.

                 At the       current   level of 346p,       the shares    are rated    at 13.5   times      forecast
             EPS and the prospective     yield    is below 3     per cent.     These    are            our
             with  the   sector  average     and,    purely  on    a   fundamental           ratings    much in  line
             envisage    significant   strength   on a       short term    view.        appraisal, we     would   not
             downside    risk as very   limited   and would     strongly     advise     However,   we     regard  the
             regional food    retailer has    become such    a   rare  breed.           retentions given     that the
Share Price (p)                                                                                        Relative          to F
    500                  T               T                   T             T                  T        T                1000
    400    LL
                                                                                                                     —|  300
    400                          Hillards'    Share Price                                              pl
                                                                                                                     —|  600


    200 =
                                                                                                                   400


    100                                                                                                            s.


                                                  Relative toFTA All-Share          Index

    50       it               Wy           l                                                                       400
    Scott                         1984     Gy                          l                 it        |
                                                                                         1584      4985
that the mew store investment will lead to higher cash flow capable of accomodating higher spending levels internally. The company has stated that it no present intention of making a rights issue, although we would assume that has kind of funding exercise must remain a possibility over the next1-2 years. some 1985/86Profit Estimate We are forecasting a 16 per cent increase in pre-tax profits to £9.0million. The tax' charge is expected to emerge in the 28-32percent range; 30 per cent would produce EPS of 25.7p. A pro-rata dividend increase to 6.75p net (9.64p gross) would thus be covered3.8 times. ' Investment Appraisal Following a lukewarm response to the dull interim results, the shares subsequently broke through the 400p level in the Spring, as (unfounded) bid rumours emerged to coincide with a strong food retail sector. However, like others the shares were unsettled by news of the Asda campaign and have since receded by more than 15 per cent from their high. Hence, the shares have outperformed the All-Share Index by rather less than 10 per cent since the interim announcement in January. At the current level of 346p, the shares are rated at 13.5times forecast EPS and the prospective yield is below 3 per cent. These are our with the sector average and, purely on a fundamental ratings much in line envisage significant strength on a short term view. appraisal, we would not downside risk as very limited and would strongly advise However, we regard the regional food retailer has become such a rare breed. retentions given that the Share Price (p) Relative to F 500 TTTTTT 1000 400 LL -| 300 400Hillards' Share Price pl -| 600 200 = 400 100 s. Relative toFTA All-Share Index 50 it Wy l 400 Scott1984 Gy l it | 1584 4985
Read by machine, contrast corrected
             that   the      mew store      investment       will  lead    to  higher     cash     flow     capable of
             accomodating     higher   spending levels internally.         The     company   has   stated that   it
        no present intention of making a rights issue, although we would assume that has
             kind      of funding exercise    must remain    a possibility     over the  next 1-2  years.     some
             1985/86 Profit Estimate

                 We      are     forecasting  a 16   per     cent increase     in pre-tax profits  to     £9.0 million.
             The  tax’ charge    is expected    to   emerge     in     the   28-32  per cent    range;     30 per cent
             would  produce      EPS   of     25.7p. A        pro-rata    dividend  increase    to 6.75p   net (9.64p
             gross) would thus   be covered 3.8 times.

        ‘    Investment Appraisal

                 Following       a   lukewarm        response     to   the    dull  interim     results,   the shares
        subsequently broke through the 400p level in the Spring, as (unfounded) bid rumours
             emerged     to   coincide  with  a strong       food  retail  sector.      However,   like    others  the
             shares were      unsettled by    news   of  the   Asda    campaign     and   have     since   receded  by
             more   than 15   per   cent     from their  high.     Hence,  the    shares  have    outperformed     the
             All-Share Index by rather less than         10  per cent      since    the interim    announcement     in
             January.

                 At the       current   level of 346p,       the shares    are rated    at 13.5   times      forecast
             EPS and the prospective     yield    is below 3     per cent.     These    are            our
             with  the   sector  average     and,    purely  on    a   fundamental           ratings    much in  line
             envisage    significant   strength   on a       short term    view.        appraisal, we     would   not
             downside    risk as very   limited   and would     strongly     advise     However,   we     regard  the
             regional food    retailer has    become such    a   rare  breed.           retentions given     that the
Share Price (p)                                                                                        Relative          to F
    500                  T               T                   T             T                  T        T                1000
    400    LL
                                                                                                                     —|  300
    400                          Hillards'    Share Price                                              pl
                                                                                                                     —|  600


    200 =
                                                                                                                   400


    100                                                                                                            s.


                                                  Relative toFTA All-Share          Index

    50       it               Wy           l                                                                       400
    Scott                         1984     Gy                          l                 it        |
                                                                                         1584      4985
that the mew store investment will lead to higher cash flow capable of accomodating higher spending levels internally. The company has stated that it no present intention of making a rights issue, although we would assume that has kind of funding exercise must remain a possibility over the next1-2 years. some 1985/86Profit Estimate We are forecasting a 16 per cent increase in pre-tax profits to £9.0million. The tax' charge is expected to emerge in the 28-32percent range; 30 per cent would produce EPS of 25.7p. A pro-rata dividend increase to 6.75p net (9.64p gross) would thus be covered3.8 times. ' Investment Appraisal Following a lukewarm response to the dull interim results, the shares subsequently broke through the 400p level in the Spring, as (unfounded) bid rumours emerged to coincide with a strong food retail sector. However, like others the shares were unsettled by news of the Asda campaign and have since receded by more than 15 per cent from their high. Hence, the shares have outperformed the All-Share Index by rather less than 10 per cent since the interim announcement in January. At the current level of 346p, the shares are rated at 13.5times forecast EPS and the prospective yield is below 3 per cent. These are our with the sector average and, purely on a fundamental ratings much in line envisage significant strength on a short term view. appraisal, we would not downside risk as very limited and would strongly advise However, we regard the regional food retailer has become such a rare breed. retentions given that the Share Price (p) Relative to F 500 TTTTTT 1000 400 LL -| 300 400Hillards' Share Price pl -| 600 200 = 400 100 s. Relative toFTA All-Share Index 50 it Wy l 400 Scott1984 Gy l it | 1584 4985