Comment on 1984/85 results page 1 of 4 next
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
                                                    Telephone: 0 1-6284433
                                                         SIX 4 14 1
                                                    Telex:886594
   Salisbury House,London Wali,London,EC2B\^5SX     Fax:0 1-6282634
                                                    (Groups 2 or3l


   HILLARDS PLC                                                                                        23rd July, 1985
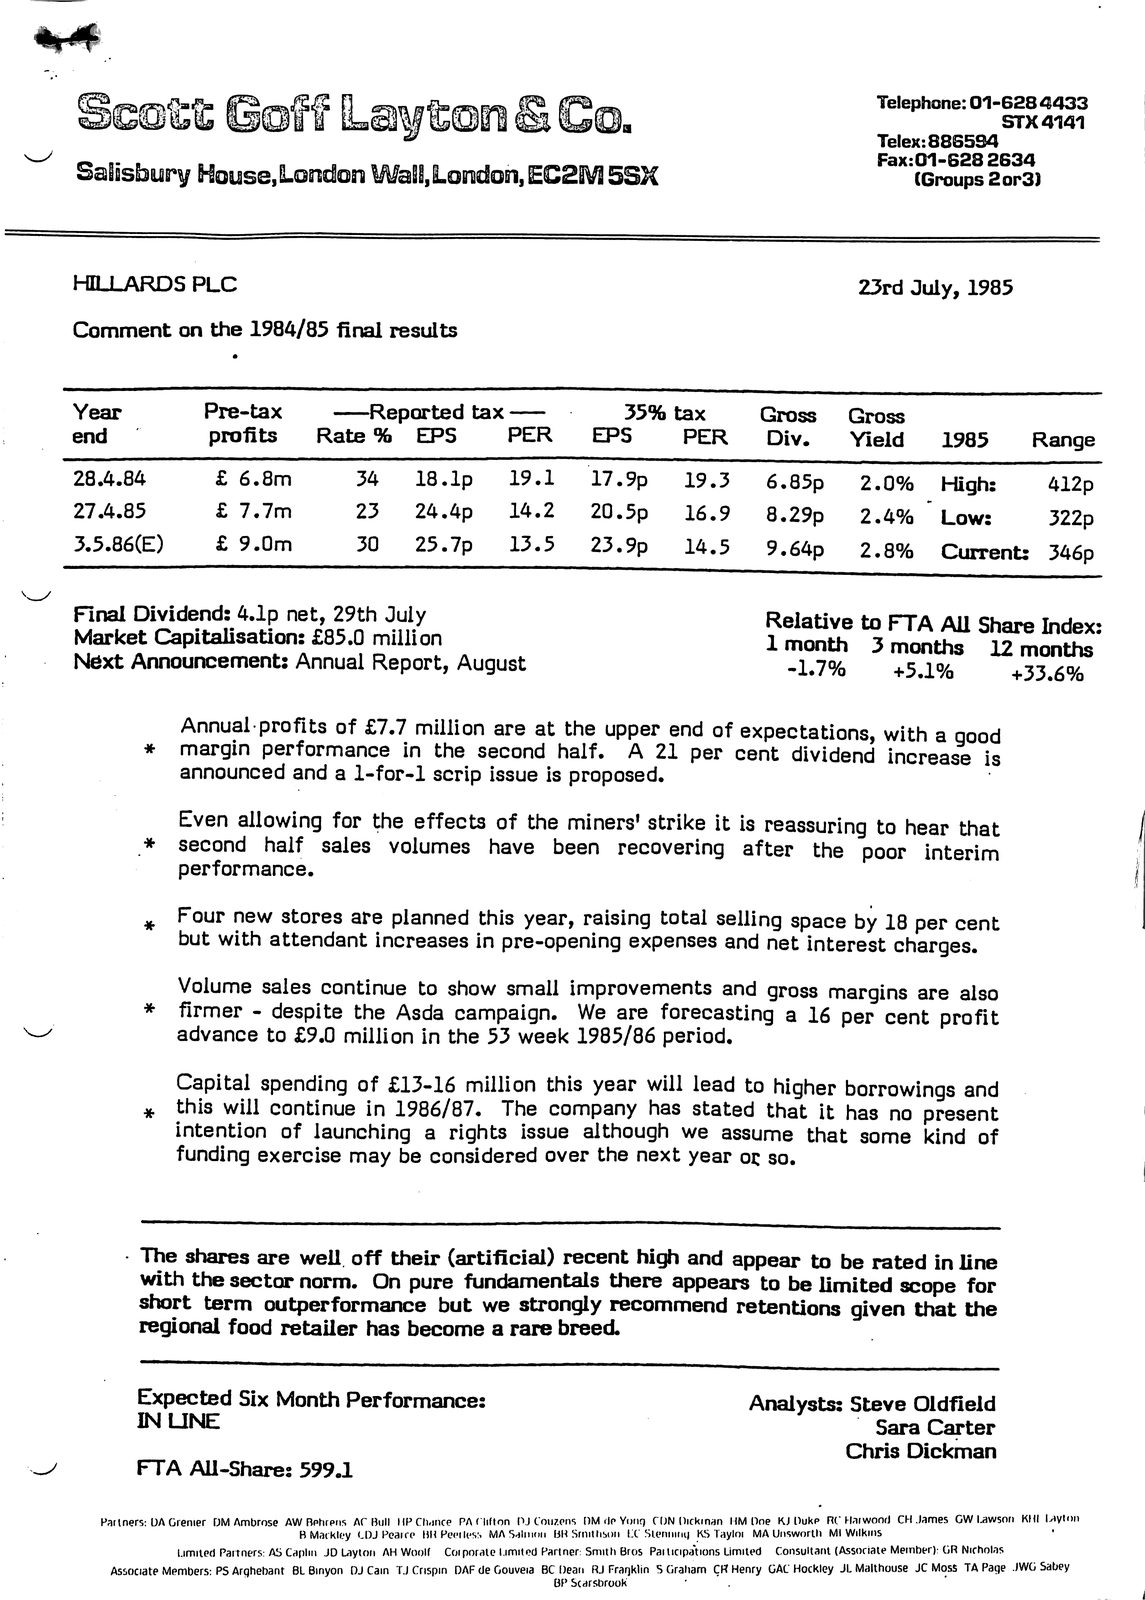
   Comment on the 1984/85 final results

   Year         Pre-tax                 Reported tax                   35% tax           Gross     Gross
   end          profits      Rate %          EPS           PER     EPS       PER          Div.     Yield       1985    Range
   28.4.84           £   6.8m         34     18 .Ip    19   .1     17.9p     19 .3        6.85p        2.0%    High:   412p
   27.4.85           £   7.7m         23     24.4p        14.2     20.5p     16.9         8.29p        2.4%    Low:    322p
   3.5.86(E)         £   9.0m         30     25.7p     13   .5     23.9p     14.5         9.64p        2.8%    Current: 346p

   Rnal Dividend: 4.1p net, 29th July                                                     Relative to FTA All Share Index:
   Market Capitalisation: £85.0 million                                                   1 month      3 months  12 months
   Ndxt Announcement: Annual Report, August                                                   -1.7%    +5.1%       +33.6%
                Annual profits of £7.7 million are                         at the upper end ofexpectations, with a good
          *     margin       performance    in the     second     half. A 21 per cent dividend         increase      is
                announced and a 1-for-l scrip issue is proposed.
                Even allowing for       the  effects of the miners' strike      it    is  reassuring       to hear that
          *     second       half sales     volumes  have     been     recovering     after     the    poor interim
                performance.
          ^     Four new stores are planned this     year, raising     total selling               space by 18 per cent
                but with attendant increases in pre-opening expenses and net interest charges.
                Volume sales continue        to show small improvements                  and gross margins are also
          *     firmer   -   despite  the Asda campaign.          We are forecasting      a 16          per cent profit
                advance to £9.0 million in the 53 week 1985/86 period.
                Capital spending      of £13-16   million     this year will          lead to higher borrowings and
          *     this    will continue in 1986/87.     The     company has    stated that it        has   no present
                intention    of   launching  a rights   issue     although  we         assume that     some kind of
                funding                  exercise may be considered over the next year or so.


   The shares are well   off their (artificial) recent high and                                                         appear to be rated in line
   with the sector norm.              On pure fundamentals there appears to be limited scope                                                   for
   short term outperformance                                                                   but we strongly recommend retentions given that the
   regional food retailer has become a rare breed.

   Expected Six Month Performance:                                                                                        Analysts: Steve Oldfield
   INUNE                                                                                                                               Sara Carter
   FTA AU-Share: 599 .1                                                                                                              Chris Dickman

   Parlners: UA Grenier DM Ambrose AW Behrens AC Bull IIP Chunce PA(lifton DJ Couzens DM <Ip Votiq CDN Dickman HM One KJ Duke  RCHnrwood CM James GWl^wsnn KHI
                         BMackloy LDJ Pcarre BRPeerless MA Salmon     BRSmithson     LC Slenning KS Taylor        MA Unsworth  MlWtlkrns *
      Limited Partners:AS Caplin JD Liytori AH Woolf CorporateLimited Partner: Smith Bros ParticipationsLimited Consultant(Associate Member): GRNicholas
Associate Members: PS Arghebant BL Binyon OJ Cam TJCrispin OAF deGouveia BC Dean RJ Fragklin SGraham (TR Henry GAC Hockley JL Malthouse JC Moss TA Page JWG Sabey
       BP Scarsbrook
Telephone:01-6284433 SIX 4 14 1 Telex:886594 Salisbury House,London Wali,London,EC2B\^5SX Fax:0 1-6282634 (Groups 2 or3l HILLARDS PLC 23rd July,1985 Comment on the 1984/85final results Year Pre-tax Reported tax 35% tax Gross Gross end profits Rate % EPS PER EPS PER Div. Yield1985 Range 28.4.84 £ 6.8m 34 18 .Ip 19 .1 17.9p 19 .3 6.85p 2.0%High: 412p 27.4.85 £ 7.7m 23 24.4p 14.2 20.5p 16.9 8.29p2.4%Low: 322p 3.5.86(E) £ 9.0m 30 25.7p 13 .5 23.9p 14.5 9.64p 2.8%Current: 346p Rnal Dividend: 4.1p net, 29th July Relative to FTA All Share Index: Market Capitalisation:£85.0 million 1 month 3 months 12 months Ndxt Announcement: Annual Report, August-1.7%+5.1% +33.6% Annual profits of £7.7million are at the upper end ofexpectations, with a good * margin performance in the second half. A 21 per cent dividend increase is announced and a 1-for-l scrip issue is proposed. Even allowing for the effects of the miners' strike it is reassuring to hear that * second half sales volumes have been recovering after the poor interim performance. ^ Four new stores are planned this year, raising total selling space by 18 per cent but with attendant increases in pre-opening expenses and net interest charges. Volume sales continue to show small improvements and gross margins are also * firmer - despite the Asda campaign. We are forecasting a 16 per cent profit advance to £9.0million in the 53week1985/86 period. Capital spending of £13-16million this year will lead to higher borrowings and * this will continue in 1986/87. The company has stated that it has no present intention of launching a rights issue although we assume that some kind of funding exercise may be considered over the next year or so. The shares are well off their (artificial) recent high and appear to be rated in line with the sector norm. On pure fundamentals there appears to be limited scope for short term outperformance but we strongly recommend retentions given that the regional food retailer has become a rare breed. Expected Six Month Performance: Analysts: Steve Oldfield INUNE Sara Carter FTA AU-Share: 599.1Chris Dickman Parlners: UA Grenier DM Ambrose AW Behrens AC Bull IIP Chunce PA(lifton DJ Couzens DM <Ip Votiq CDN Dickman HM One KJ Duke RCHnrwood CM James GWl^wsnn KHI BMackloy LDJ Pcarre BRPeerless MA Salmon BRSmithson LC Slenning KS Taylor MA Unsworth MlWtlkrns * Limited Partners:AS Caplin JD Liytori AH Woolf CorporateLimited Partner: Smith Bros ParticipationsLimited Consultant(Associate Member): GRNicholas Associate Members: PS Arghebant BL Binyon OJ Cam TJCrispin OAF deGouveia BC Dean RJ Fragklin SGraham (TR Henry GAC Hockley JL Malthouse JC Moss TA Page JWG Sabey BP Scarsbrook
Read by machine highest quality of the three
   scott Goff    €
   Salisbury House,London Wall,London,  SSK    oe (Groups 2or3)


   HILLARDS PLC    23rd July, 1985

   Comment on the  1984/85 final results


                                                                ———    ——
       Year             Pre-tax      —      Reported tax——_.              35%   tax                      Gross
       end   —          profits      Rate %        EPS         PER     EPS          PER        Div.      Yield       1985    Range
       28.4.84              £  6.8m        34      18.lp      19.1                  19.3       6.85p      2.0%       Highs    412p
       27.4.85              £  7.7m        23.     24.4p      14.2     20.5p        16.9       8.299      2.4%     Low:       322p
       3.5.86(E)            £  9.0m        300     25.7p               23.9p        14.5                  2.8%       Current: 346p
                                   —
                                                                                                  —

 NY
       Final Dividend:            net,   29th July                                              Relative  to FTA
       Market     Capitalisation: £85.0 million                                                 1 month    3         All Share Index:
       Next  Announcement: Annual Report, August                                                  -1.7%       °          12 months
                        Annual profits   of £7.7   million are  at the  upper   end of     expectations,      with   a    good
                  *     margin   performance     in the  second   half.   A 21      per     cent  dividend     increase is
                        announced and    a 1-for-1 scrip    issue is   proposed.

                        Even allowing  for  the    effects  of   the miners! strike     it  is  reassuring  to    hear    that
                 .*     second   half sales     volumes     have  been    recovering     after      the   poor         interim
                        performance.

                       Four   new stores   are    planned   this year, raising  total     selling space  by     18 per    cent
       but with attendant increases in pre-opening expenses and net interest charges.
                        Volume sales   continue    to    show small    improvements and        gross    margins    are    also
                  *     firmer -  despite  the    Asda campaign.       We are   forecasting       a 16  per     cent    profit
 WY                    advance   to £9.0  million in the 53 week       1985/86  period.
                       Capital   spending   of £13-16     million this    year will lead    to  higher          borrowings and
                 *%    this will  continue  in    1986/87.  The        company  has stated     that it   has    no
                       intention  of   launching       rights    issue although     we                                 present
                                                    a                                   assume     that  some      kind     of
       funding exercise may be considered over the next year or so.


   ——
       —
 . The shares are well off their (artificial) recent high and appear to be rated in line
       with the              sector     norm.     On pure     fundamentals there            appears to be limited scope                             for
   short                term   outperformance        but                      we strongly recommend retentions given that the
   regional food                                       retailer has become    a rare    breed.

                                        -                                        —_     —

   Expected                                         Six Month Performance:                  Analysts:
                                                                         3                                                         ysts: Steve Oldfield
   IN LINE                                                                                                                                  Sara Carter
   FTA All-Share:                       599.1                                                                                             Chris Dickman

       Partners:  DA Grenier DM Ambrose AW Behrens AC Bull HP Chance  PA Clifton DJ Couzens 0M de Yong CON Dickinan HM Doe KJ Duke RC Harwood CH James GW Lawson KHI Layton
                                        B Mackley  CDJ Pearce BH Peerless     MA Salmon BR Smithson EC  KS Taylor   MA Unsworth    MI Wilkins        '
      lumited Partners: AS Caplin JD Layton AH Woolf Corporate Limited Partner: Smith Bros Participations Limited Consultant (Associate Member): GR Nicholas
Associate Members: PS Arghebant BL Binyon OJ Cain TJ Crispin DAF de Gouveia BC Dean RJ Franklin S Graham CR Henry GAC Hockley JL Malthouse JC Moss TA Page JWG Sabey
       .
                                                                BP Scarsbrook               .
scott Goff € Salisbury House,London Wall,London, SSK oe (Groups 2or3) HILLARDS PLC 23rd July,1985 Comment on the 1984/85final results --- -- Year Pre-tax - Reported tax--_. 35% tax Gross end - profits Rate % EPS PER EPS PER Div. Yield1985 Range 28.4.84 £ 6.8m 34 18.lp 19.1 19.3 6.85p 2.0%Highs 412p 27.4.85 £ 7.7m 23. 24.4p 14.2 20.5p 16.9 8.299 2.4% Low: 322p 3.5.86(E) £ 9.0m 300 25.7p 23.9p 14.52.8%Current: 346p - - NY Final Dividend: net, 29th July Relative to FTA Market Capitalisation:£85.0 million 1 month 3 All Share Index: Next Announcement: Annual Report, August-1.7%° 12 months Annual profits of £7.7million are at the upper end of expectations, with a good * margin performance in the second half. A 21 per cent dividend increase is announced and a 1-for-1 scrip issue is proposed. Even allowing for the effects of the miners! strike it is reassuring to hear that .* second half sales volumes have been recovering after the poor interim performance. Four new stores are planned this year, raising total selling space by 18 per cent but with attendant increases in pre-opening expenses and net interest charges. Volume sales continue to show small improvements and gross margins are also * firmer - despite the Asda campaign. We are forecasting a 16 per cent profit WY advance to £9.0million in the 53week1985/86 period. Capital spending of £13-16million this year will lead to higher borrowings and *% this will continue in 1986/87. The company has stated that it has no intention of launching rights issue although we present a assume that some kind of funding exercise may be considered over the next year or so. -- - . The shares are well off their (artificial) recent high and appear to be rated in line with the sector norm. On pure fundamentals there appears to be limited scope for short term outperformance but we strongly recommend retentions given that the regional food retailer has become a rare breed. - -_ - Expected Six Month Performance: Analysts: 3 ysts: Steve Oldfield IN LINE Sara Carter FTA All-Share: 599.1Chris Dickman Partners: DA Grenier DM Ambrose AW Behrens AC Bull HP Chance PA Clifton DJ Couzens 0M de Yong CON Dickinan HM Doe KJ Duke RC Harwood CH James GW Lawson KHI Layton B Mackley CDJ Pearce BH Peerless MA Salmon BR Smithson EC KS Taylor MA Unsworth MI Wilkins ' lumited Partners: AS Caplin JD Layton AH Woolf Corporate Limited Partner: Smith Bros Participations Limited Consultant (Associate Member): GR Nicholas Associate Members: PS Arghebant BL Binyon OJ Cain TJ Crispin DAF de Gouveia BC Dean RJ Franklin S Graham CR Henry GAC Hockley JL Malthouse JC Moss TA Page JWG Sabey . BP Scarsbrook .
Read by machine, contrast corrected
   scott Goff    €
   Salisbury House,London Wall,London,  SSK    oe (Groups 2or3)


   HILLARDS PLC    23rd July, 1985

   Comment on the  1984/85 final results


                                                                ———    ——
       Year             Pre-tax      —      Reported tax——_.              35%   tax                      Gross
       end   —          profits      Rate %        EPS         PER     EPS          PER        Div.      Yield       1985    Range
       28.4.84              £  6.8m        34      18.lp      19.1                  19.3       6.85p      2.0%       Highs    412p
       27.4.85              £  7.7m        23.     24.4p      14.2     20.5p        16.9       8.299      2.4%     Low:       322p
       3.5.86(E)            £  9.0m        300     25.7p               23.9p        14.5                  2.8%       Current: 346p
                                   —
                                                                                                  —

 NY
       Final Dividend:            net,   29th July                                              Relative  to FTA
       Market     Capitalisation: £85.0 million                                                 1 month    3         All Share Index:
       Next  Announcement: Annual Report, August                                                  -1.7%       °          12 months
                        Annual profits   of £7.7   million are  at the  upper   end of     expectations,      with   a    good
                  *     margin   performance     in the  second   half.   A 21      per     cent  dividend     increase is
                        announced and    a 1-for-1 scrip    issue is   proposed.

                        Even allowing  for  the    effects  of   the miners! strike     it  is  reassuring  to    hear    that
                 .*     second   half sales     volumes     have  been    recovering     after      the   poor         interim
                        performance.

                       Four   new stores   are    planned   this year, raising  total     selling space  by     18 per    cent
       but with attendant increases in pre-opening expenses and net interest charges.
                        Volume sales   continue    to    show small    improvements and        gross    margins    are    also
                  *     firmer -  despite  the    Asda campaign.       We are   forecasting       a 16  per     cent    profit
 WY                    advance   to £9.0  million in the 53 week       1985/86  period.
                       Capital   spending   of £13-16     million this    year will lead    to  higher          borrowings and
                 *%    this will  continue  in    1986/87.  The        company  has stated     that it   has    no
                       intention  of   launching       rights    issue although     we                                 present
                                                    a                                   assume     that  some      kind     of
       funding exercise may be considered over the next year or so.


   ——
       —
 . The shares are well off their (artificial) recent high and appear to be rated in line
       with the              sector     norm.     On pure     fundamentals there            appears to be limited scope                             for
   short                term   outperformance        but                      we strongly recommend retentions given that the
   regional food                                       retailer has become    a rare    breed.

                                        -                                        —_     —

   Expected                                         Six Month Performance:                  Analysts:
                                                                         3                                                         ysts: Steve Oldfield
   IN LINE                                                                                                                                  Sara Carter
   FTA All-Share:                       599.1                                                                                             Chris Dickman

       Partners:  DA Grenier DM Ambrose AW Behrens AC Bull HP Chance  PA Clifton DJ Couzens 0M de Yong CON Dickinan HM Doe KJ Duke RC Harwood CH James GW Lawson KHI Layton
                                        B Mackley  CDJ Pearce BH Peerless     MA Salmon BR Smithson EC  KS Taylor   MA Unsworth    MI Wilkins        '
      lumited Partners: AS Caplin JD Layton AH Woolf Corporate Limited Partner: Smith Bros Participations Limited Consultant (Associate Member): GR Nicholas
Associate Members: PS Arghebant BL Binyon OJ Cain TJ Crispin DAF de Gouveia BC Dean RJ Franklin S Graham CR Henry GAC Hockley JL Malthouse JC Moss TA Page JWG Sabey
       .
                                                                BP Scarsbrook               .
scott Goff € Salisbury House,London Wall,London, SSK oe (Groups 2or3) HILLARDS PLC 23rd July,1985 Comment on the 1984/85final results --- -- Year Pre-tax - Reported tax--_. 35% tax Gross end - profits Rate % EPS PER EPS PER Div. Yield1985 Range 28.4.84 £ 6.8m 34 18.lp 19.1 19.3 6.85p 2.0%Highs 412p 27.4.85 £ 7.7m 23. 24.4p 14.2 20.5p 16.9 8.299 2.4% Low: 322p 3.5.86(E) £ 9.0m 300 25.7p 23.9p 14.52.8%Current: 346p - - NY Final Dividend: net, 29th July Relative to FTA Market Capitalisation:£85.0 million 1 month 3 All Share Index: Next Announcement: Annual Report, August-1.7%° 12 months Annual profits of £7.7million are at the upper end of expectations, with a good * margin performance in the second half. A 21 per cent dividend increase is announced and a 1-for-1 scrip issue is proposed. Even allowing for the effects of the miners! strike it is reassuring to hear that .* second half sales volumes have been recovering after the poor interim performance. Four new stores are planned this year, raising total selling space by 18 per cent but with attendant increases in pre-opening expenses and net interest charges. Volume sales continue to show small improvements and gross margins are also * firmer - despite the Asda campaign. We are forecasting a 16 per cent profit WY advance to £9.0million in the 53week1985/86 period. Capital spending of £13-16million this year will lead to higher borrowings and *% this will continue in 1986/87. The company has stated that it has no intention of launching rights issue although we present a assume that some kind of funding exercise may be considered over the next year or so. -- - . The shares are well off their (artificial) recent high and appear to be rated in line with the sector norm. On pure fundamentals there appears to be limited scope for short term outperformance but we strongly recommend retentions given that the regional food retailer has become a rare breed. - -_ - Expected Six Month Performance: Analysts: 3 ysts: Steve Oldfield IN LINE Sara Carter FTA All-Share: 599.1Chris Dickman Partners: DA Grenier DM Ambrose AW Behrens AC Bull HP Chance PA Clifton DJ Couzens 0M de Yong CON Dickinan HM Doe KJ Duke RC Harwood CH James GW Lawson KHI Layton B Mackley CDJ Pearce BH Peerless MA Salmon BR Smithson EC KS Taylor MA Unsworth MI Wilkins ' lumited Partners: AS Caplin JD Layton AH Woolf Corporate Limited Partner: Smith Bros Participations Limited Consultant (Associate Member): GR Nicholas Associate Members: PS Arghebant BL Binyon OJ Cain TJ Crispin DAF de Gouveia BC Dean RJ Franklin S Graham CR Henry GAC Hockley JL Malthouse JC Moss TA Page JWG Sabey . BP Scarsbrook .