Auditors Discussion Points 1984 page 10 of 10 previous
Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
                                                     -           5      -

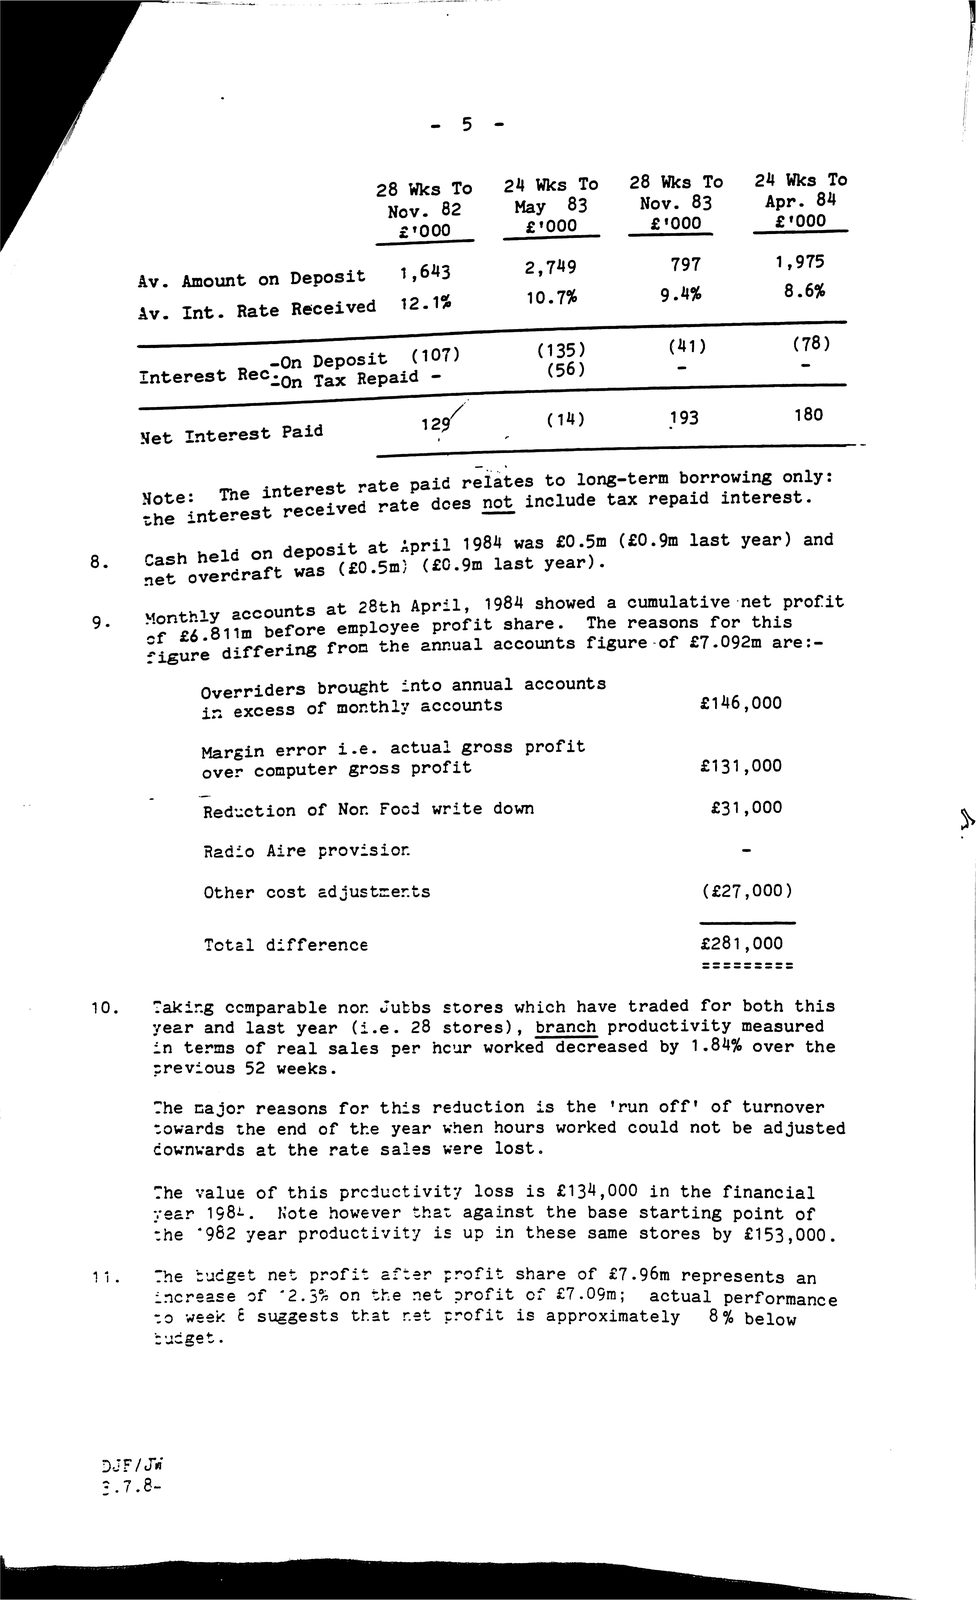
28 Wks                                                          To       24     Wks  To    28  Wks    To    24   Wks To
 Nov.                                                       82             May      83      Nov.   83       Apr.     84
                                                     £*000                  £'000              £'000            £'000
                                                                                                                1,975
        Av.  Amount        on Deposit               1> 6^3                  10.7%                               8 .6%
        Av.  Int .     Rate     Received             12.1%
        Interest           -On Deposit                   (107)
                       Rec^Q^j            Repaid     -

        Net  Interest           Paid

         Note:    The      •           ^              paid                                            borrowing only:
         ^he       interest     rece-vc«   ^.^te     dees         not include             tax repaid      interest.
                                deoosit    at                                       £0.5m             last  year) and April 1984 was (£0.9m
   8 .   Sifoverran waa                <£0.5m;                  <£0.9a  laat       year).

           r^'prsilm             before employee     profit share.                    The  reasons for       this
   9 .   "            accounts at                      28th April,     1984     showed    a cumulative      net  profit
         '^ure        differing       fron  the                 annual  accounts      figure-of    £7.092m      are:-
                  Overriders        brought                        annual   accounts into
                  in   excess of monthly         accounts                                               £146,000
                  Margin       error   i.e.         actual          gross   profit
                  over     computer    gross                profit                                      £131,000
                  Reduction     of     Nor. Food     write              down                            £3 1,000

                  Radio    Aire     provision
                  Other    cost       adjustments                                                     (£27,000)

                    Total  difference                                                                   £281,000

   10.   Taking       comparable       nor. Jutbs         stores           which     have  traded     for   both this
         year      and  last    year   (i.e.   28         stores),              branch    productivity measured
         in      terms  of real       sales  per     hcur                 worked   decreased   by   1.84% over    the
         previous       52     weeks.
         The      major    reasons     for  this     reduction                  is the    'run    off of turnover
         cowards       the  end     of the   year         when          hours      worked  could    not be  adjusted
         downwards         at   the rate    sales         were          lost .

         The      value    of this     productivity                  loss   is     £134,000    in the     financial
         year       198^.  Note       however         that    against            the  base  starting       point  of
         the      *982 year         productivity     is             up  in  these     same  stores      by  £153,000.
   11.   The      tucget   net  profit      after         profit           share   of     £7.96m      represents  an
         increase       of      '2.3%  on   the net                profit   of     £7.09m;     actual     performance
         to      week  £   suggests    that   net         profit           is    approximately          8%  below
         tudget.


     DJF/J""
     -.7 .8-
- 5 - 28 Wks To 24 Wks To 28 Wks To 24 Wks To Nov. 82 May 83 Nov. 83 Apr. 84 £*000 £'000 £'000 £'000 1,975 Av. Amount on Deposit1>6^3 10.7% 8 .6% Av. Int . Rate Received12.1% Interest -On Deposit(107) Rec^Q^j Repaid - Net Interest Paid Note: The • ^ paid borrowing only: ^he interest rece-vc« ^.^te dees not include tax repaid interest. deoosit at £0.5m last year) and April1984 was (£0.9m 8 . Sifoverran waa <£0.5m; <£0.9a laat year). r^'prsilm before employee profit share. The reasons for this 9 . " accounts at 28th April,1984 showed a cumulative net profit '^ure differing fron the annual accounts figure-of £7.092mare:- Overriders brought annual accounts into in excess of monthly accounts£146,000 Margin error i.e. actual gross profit over computer gross profit£131,000 Reduction of Nor. Food write down£31,000 Radio Aire provision Other cost adjustments(£27,000) Total difference£281,000 10.Taking comparable nor. Jutbs stores which have traded for both this year and last year (i.e. 28 stores), branch productivity measured in terms of real sales per hcur worked decreased by 1.84%over the previous 52 weeks. The major reasons for this reduction is the 'run off of turnover cowards the end of the year when hours worked could not be adjusted downwards at the rate sales were lost . The value of this productivity loss is £134,000 in the financial year198^. Note however that against the base starting point of the *982year productivity is up in these same stores by £153,000. 11. The tucget net profit after profit share of £7.96m represents an increase of '2.3% on the net profit of £7.09m; actual performance to week £ suggests that net profit is approximately 8% below tudget. DJF/J"" -.7 .8-
Read by machine highest quality of the three
                                 28 Wks     To      24 Wks       To       28 Wks     To  24    Wks To
                                     .  62              May     83        Nov.   83      Apr.     84
                                                         £'000               £'000           £'000

 Av.  Amount    on  Deposit        1,643                 2,749               797
 Av.  Int.  Rate    Received       12.1%              10.7%                  9.4%            .
                -On    Deposit        (107)               (135)              (41)            (78)
 Interest   Rec-o,        Tax    Repaid -                    (56)            _
 Net  Interest     Paid                 129         ;        (14)            193             180
                     interest rate    paic     relates       to   long-term        borrowing  only:
 Note:    Tie      received      rate  does     not      include      tax repaid     interest.
 che  interest
       held    on  deposit     at    April     1984     was     £0.5m    (£0.9m last     year)  and
                    was    (£0.5m}    (£0.9m     last          year).
                              28th    April,     1984     showed      a           cumulative
 Monthly   accounts        at                                                            net   profit
               before       employee    profit      share.           The  reasons    for this
          differing        from   the annual     accounts            figure -of £7.092m      are:-
       Overriders      brought           annual          accounts
       in  excess      of     monthly   accounts                                    £146 ,000
       Margin     error    i.e.   actual     gross       profit
       over    computer        gross  profit                                        £131,000

       Reduction       of  Nor   Food   write     down                               £31,000

       Redio   Aire         provisior

       Other   cost                                                                  (£27 ,000 )

       Tetel   difference                                                           £281,000


 10.   Taking    cemparable     nor  Jutbs  stores    which      have     traded    for  both this
       year  and    last year   (i.e.   28  stores),     branch       productivity       measured
   in terms of real sales per heur worked decreased by 1.84% over the
     52 weeks.

       The   maior   reasons    for  this  reduction     is  the      'run  off'     of  turnover
wv
                 the end     of  the  year  when  hours      worked       could  not    be adjusted
                     at  the  rate   sales  were  lost.

       The   value   of  this   preductivity     loss    is  £134,000      in   the  financial
             1984.      Note  however     that  against    the  base  starting          point of
       the          year   productivity    is up  in     these  same  stores        by   £153,000.

 14     The  tucget    net profit    after  profit    share    of     £7.96m    represents    an
       increase     of  “2.3%   on  the net    profit    of  £7.09m;       actual    performance
       =o   week €   suggests   that   ret  rrofit    is    approximately           8%   below


 / TH
 DIF
28 Wks To 24 Wks To 28 Wks To 24 Wks To . 62 May 83 Nov. 83 Apr. 84 £'000 £'000 £'000 Av. Amount on Deposit1,6432,749 797 Av. Int. Rate Received12.1%10.7% 9.4% . -On Deposit(107)(135) (41) (78) Interest Rec-o, Tax Repaid-(56) _ Net Interest Paid129; (14) 193 180 interest rate paic relates to long-term borrowing only: Note: Tie received rate does not include tax repaid interest. che interest held on deposit at April1984 was £0.5m (£0.9m last year) and was (£0.5m} (£0.9m last year). 28th April,1984 showed a cumulative Monthly accounts at net profit before employee profit share. The reasons for this differing from the annual accounts figure -of £7.092mare:- Overriders brought annual accounts in excess of monthly accounts£146,000 Margin error i.e. actual gross profit over computer gross profit£131,000 Reduction of Nor Food write down£31,000 Redio Aire provisior Other cost(£27,000 ) Tetel difference£281,000 10.Taking cemparable nor Jutbs stores which have traded for both this year and last year (i.e. 28 stores), branch productivity measured in terms of real sales per heur worked decreased by 1.84%over the 52 weeks. The maior reasons for this reduction is the 'run off' of turnover wv the end of the year when hours worked could not be adjusted at the rate sales were lost. The value of this preductivity loss is £134,000 in the financial 1984.Note however that against the base starting point of the year productivity is up in these same stores by £153,000. 14 The tucget net profit after profit share of £7.96m represents an increase of "2.3% on the net profit of £7.09m; actual performance =o week € suggests that ret rrofit is approximately 8% below / TH DIF
Read by machine, contrast corrected
                                 28 Wks     To      24 Wks       To       28 Wks     To  24    Wks To
                                     .  62              May     83        Nov.   83      Apr.     84
                                                         £'000               £'000           £'000

 Av.  Amount    on  Deposit        1,643                 2,749               797
 Av.  Int.  Rate    Received       12.1%              10.7%                  9.4%            .
                -On    Deposit        (107)               (135)              (41)            (78)
 Interest   Rec-o,        Tax    Repaid -                    (56)            _
 Net  Interest     Paid                 129         ;        (14)            193             180
                     interest rate    paic     relates       to   long-term        borrowing  only:
 Note:    Tie      received      rate  does     not      include      tax repaid     interest.
 che  interest
       held    on  deposit     at    April     1984     was     £0.5m    (£0.9m last     year)  and
                    was    (£0.5m}    (£0.9m     last          year).
                              28th    April,     1984     showed      a           cumulative
 Monthly   accounts        at                                                            net   profit
               before       employee    profit      share.           The  reasons    for this
          differing        from   the annual     accounts            figure -of £7.092m      are:-
       Overriders      brought           annual          accounts
       in  excess      of     monthly   accounts                                    £146 ,000
       Margin     error    i.e.   actual     gross       profit
       over    computer        gross  profit                                        £131,000

       Reduction       of  Nor   Food   write     down                               £31,000

       Redio   Aire         provisior

       Other   cost                                                                  (£27 ,000 )

       Tetel   difference                                                           £281,000


 10.   Taking    cemparable     nor  Jutbs  stores    which      have     traded    for  both this
       year  and    last year   (i.e.   28  stores),     branch       productivity       measured
   in terms of real sales per heur worked decreased by 1.84% over the
     52 weeks.

       The   maior   reasons    for  this  reduction     is  the      'run  off'     of  turnover
wv
                 the end     of  the  year  when  hours      worked       could  not    be adjusted
                     at  the  rate   sales  were  lost.

       The   value   of  this   preductivity     loss    is  £134,000      in   the  financial
             1984.      Note  however     that  against    the  base  starting          point of
       the          year   productivity    is up  in     these  same  stores        by   £153,000.

 14     The  tucget    net profit    after  profit    share    of     £7.96m    represents    an
       increase     of  “2.3%   on  the net    profit    of  £7.09m;       actual    performance
       =o   week €   suggests   that   ret  rrofit    is    approximately           8%   below


 / TH
 DIF
28 Wks To 24 Wks To 28 Wks To 24 Wks To . 62 May 83 Nov. 83 Apr. 84 £'000 £'000 £'000 Av. Amount on Deposit1,6432,749 797 Av. Int. Rate Received12.1%10.7% 9.4% . -On Deposit(107)(135) (41) (78) Interest Rec-o, Tax Repaid-(56) _ Net Interest Paid129; (14) 193 180 interest rate paic relates to long-term borrowing only: Note: Tie received rate does not include tax repaid interest. che interest held on deposit at April1984 was £0.5m (£0.9m last year) and was (£0.5m} (£0.9m last year). 28th April,1984 showed a cumulative Monthly accounts at net profit before employee profit share. The reasons for this differing from the annual accounts figure -of £7.092mare:- Overriders brought annual accounts in excess of monthly accounts£146,000 Margin error i.e. actual gross profit over computer gross profit£131,000 Reduction of Nor Food write down£31,000 Redio Aire provisior Other cost(£27,000 ) Tetel difference£281,000 10.Taking cemparable nor Jutbs stores which have traded for both this year and last year (i.e. 28 stores), branch productivity measured in terms of real sales per heur worked decreased by 1.84%over the 52 weeks. The maior reasons for this reduction is the 'run off' of turnover wv the end of the year when hours worked could not be adjusted at the rate sales were lost. The value of this preductivity loss is £134,000 in the financial 1984.Note however that against the base starting point of the year productivity is up in these same stores by £153,000. 14 The tucget net profit after profit share of £7.96m represents an increase of "2.3% on the net profit of £7.09m; actual performance =o week € suggests that ret rrofit is approximately 8% below / TH DIF