Below is what the machine read from this scan, three times over. They are kept separate rather than merged: where they disagree, the disagreement is itself worth seeing, and a single tidy transcription would hide it.
The left column is raw output. The right is the same text after the repairs that make it searchable — joining letter-spaced words, mending split ones.
Text already in the scan
    rowntree mackintosh
               owntree Mackintosh  switched to average exchange rate profit translation in               last    Interim due its
      mancial year so earnings shouldn't be nearly as badly upset by forex changes as
       ose of rival        Cadbury Schweppes,                                                      recently, a   "first thing" Even so, dollar weakness and, more
    CO  apsed  Rand      have     taken the   edge     of expectations which     are        now mostly in the    19th September
    low/mid £80ms compared with last year's £74.5m.
    uch   estimates      fit   in with  a picture  of steady,     but unspectacular, growth.              the In
    cornerstone    UK Confectionery           Division,       volumes  are running   below   earlier    hopes
    but  pricing   has   been               OK and continued  "real"       profit improvement is anticipated.
    Grocery Products should also be                 higher.   The same goes for        Rileys where new snack
    capacity is  being brought on stream                      and where margins should be starting to reflect
    lower raw material costs.
    In  the USA Toms is involved       in           a hefty  capital  expenditure        programme which will
    mean a higher depreciation                   charge and  moderation   in     progress.  An initial contri
    bution from          Original  Cookie could         add   £2y2-3m  to   the trading    profit  line which
    could  end   up being converted     at           a rate   similar to last year's average      Si.34 = £1.
    At Laura Secord and                             Rowntree Mackintosh Canada the imposition of 10% purchase
% tax and higher prices could make it difficult to achieve much 1985 profit improve
     ment.
    Th^picture       in  Europe is  likely    to have               remained one of slow but steady progress.    Slow But Steady
    Prolj^^ms  in  Benelux     have     been   tidied     up and                German management has been up    European Progress
    grade.     Marketing     investment       remains         heavy,  however, and the     achievement     of
    proper      returns  on  £100m     plus   of Continental capital employed     is       still   some years
    off.
    Overseas the      Rand occupies centre stage.                   Quitewhere it will end the day in 1985 is
    anybody's guess but translation           of the South African profit stream stands to             make a
    nasty dent.    The same applies     (to      a lesser     extent)  in Australia where  profits are     on
    the   up after    a  major overhaul     and  under        new management.               Good margins were
    locked   in to    a  UK Export Division business which has a distinct first                  half bias so
    stronger sterling    shouldn't have too much current year impact.
    After a rather higher     interest    charge                   our present arithmetic adds to a £80m 1985    £80m Target
    Rowntree Mackintosh            forecast.   The first      half currency calculation    should still    be    For '85
    mildly     positive  which     points to   an outcome of around        £25m compared with last
    year's £22.4m.                       Mind you, a slightly more cautious presentation wouldn't surprise us
    on  19th September.
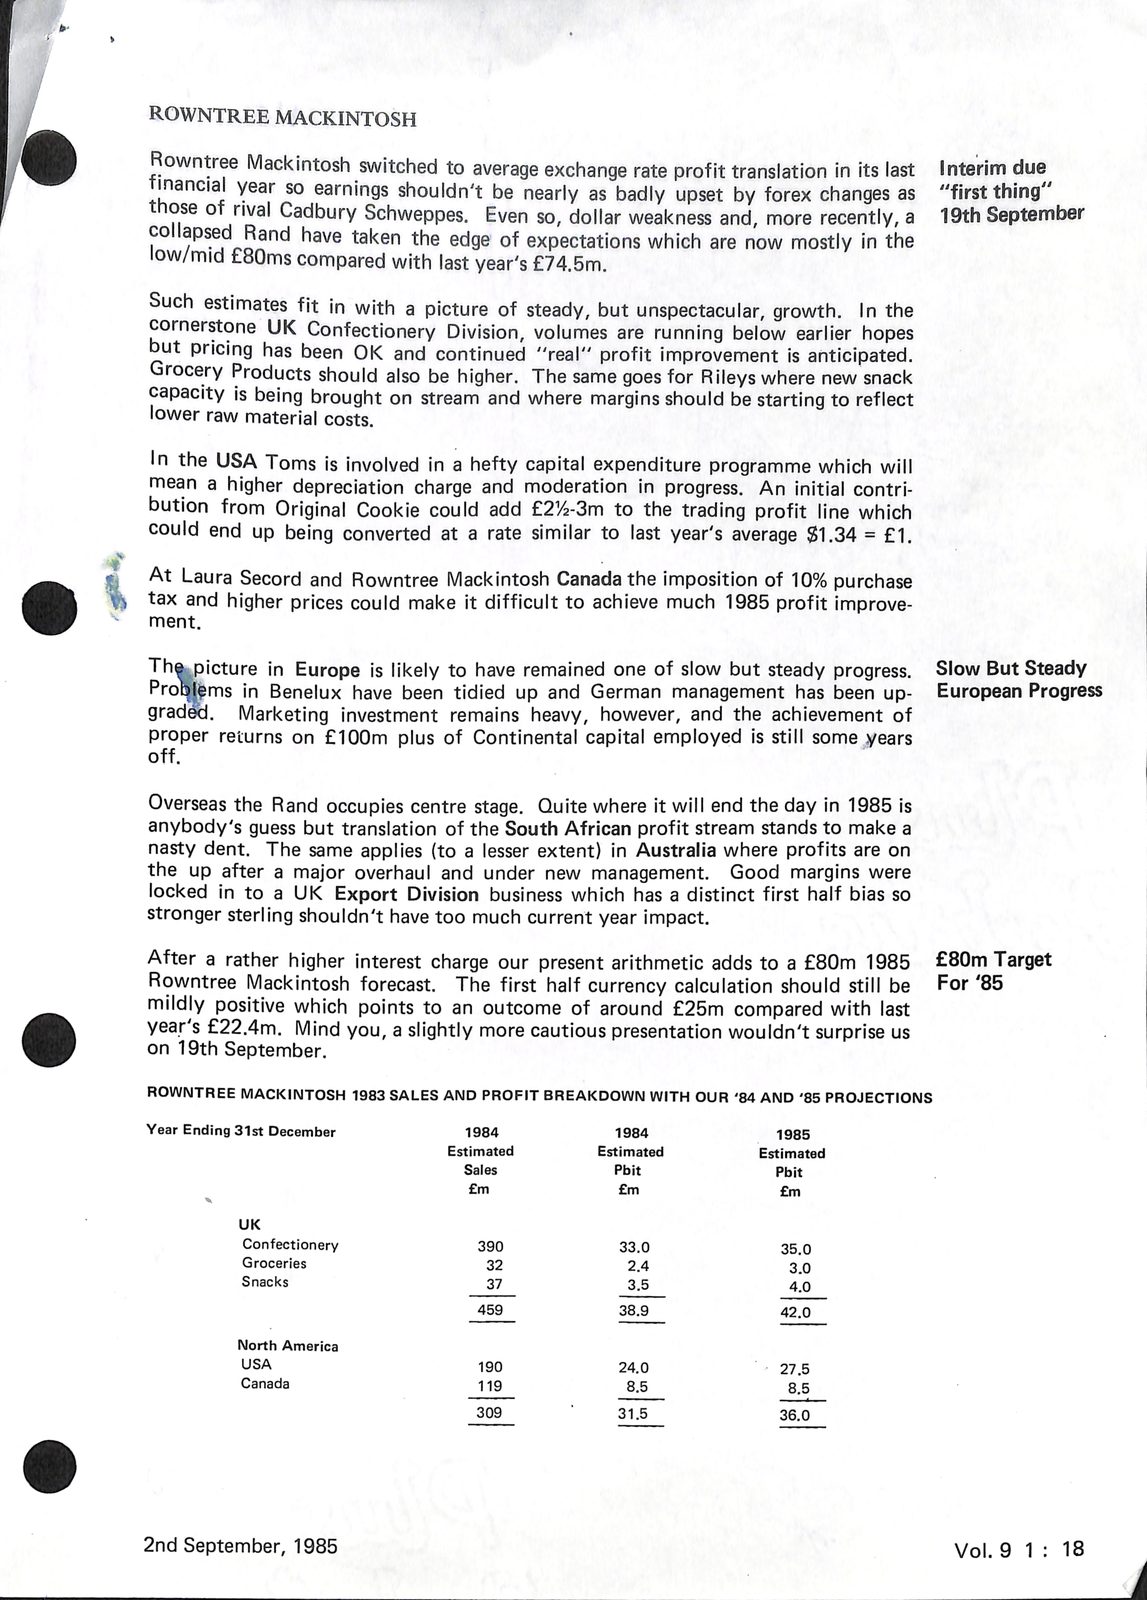
    ROWNTREE MACKINTOSH 1983 SALES AND PROFITBREAKDOWN WITH OUR '84 AND '85 PROJECTIONS
    Year Ending 31st December                   1984                   1984                1985
                                              Estimated           Estimated                Estimated
                                               Sales                   Pbit                Pbit
   £m                                                                 £m                   £m
              UK
               Confectionery                     390                        33.0              35.0
               Groceries                          32                         2.4               3.0
               Snacks                             37                         3.5               4.0
                                                 459                        38.9           42.0
                    North America
               USA                               190                        24.0           27.5
               Canada                            1 19                        8.5           8.5
                                                 309                   3 1.5               36.0


    2nd September, 1985                                                                                          Vol. 9 1 : 18
                                                                                                                     i
rowntree mackintosh owntree Mackintosh switched to average exchange rate profit translation in last Interim due its mancial year so earnings shouldn't be nearly as badly upset by forex changes as ose of rival Cadbury Schweppes, recently, a "first thing" Even so, dollar weakness and, more CO apsed Rand have taken the edge of expectations which are now mostly in the 19th September low/mid £80ms compared with last year's £74.5m. uch estimates fit in with a picture of steady, but unspectacular, growth. the In cornerstone UK Confectionery Division, volumes are running below earlier hopes but pricing has been OK and continued "real" profit improvement is anticipated. Grocery Products should also be higher. The same goes for Rileys where new snack capacity is being brought on stream and where margins should be starting to reflect lower raw material costs. In the USA Toms is involved in a hefty capital expenditure programme which will mean a higher depreciation charge and moderation in progress. An initial contri bution from Original Cookie could add £2y2-3m to the trading profit line which could end up being converted at a rate similar to last year's average Si.34 = £1. At Laura Secord and Rowntree Mackintosh Canada the imposition of 10%purchase % tax and higher prices could make it difficult to achieve much1985 profit improve ment. Th^picture in Europe is likely to have remained one of slow but steady progress. Slow But Steady Prolj^^ms in Benelux have been tidied up and German management has been up European Progress grade. Marketing investment remains heavy, however, and the achievement of proper returns on £100m plus of Continental capital employed is still some years off. Overseas the Rand occupies centre stage. Quitewhere it will end the day in 1985 is anybody's guess but translation of the South African profit stream stands to make a nasty dent. The same applies (to a lesser extent) in Australia where profits are on the up after a major overhaul and under new management. Good margins were locked in to a UK Export Division business which has a distinct first half bias so stronger sterling shouldn't have too much current year impact. After a rather higher interest charge our present arithmetic adds to a £80m 1985 £80m Target Rowntree Mackintosh forecast. The first half currency calculation should still be For '85 mildly positive which points to an outcome of around £25m compared with last year's £22.4m. Mind you, a slightly more cautious presentation wouldn't surprise us on 19th September. ROWNTREE MACKINTOSH1983 SALES AND PROFITBREAKDOWN WITH OUR '84 AND '85PROJECTIONS Year Ending 31st December19841984 1985 Estimated Estimated Estimated Sales Pbit Pbit £m £m £m UK Confectionery39033.0 35.0 Groceries322.4 3.0 Snacks373.5 4.0 459 38.9 42.0 North America USA 190 24.0 27.5 Canada 1 19 8.5 8.5 309 3 1.5 36.0 2nd September,1985 Vol. 9 1 : 18 i
Read by machine
   J|   ROWNTREE         MACKINTOSH
 &      Rowntree     Mackintosh        switched    to   average   exchange      rate    profit translation  in  its  last      Interim due
        financial  year     so    earnings   shouldn‘t   be     nearly  as badly     upset by forex      changes          as   “first thing
        those  of rival     Cadbury    Schweppes.        Even     so, dollar                                      recently,a   19th weakness and, more September
        collapsed    Rand      have    taken  the  edge  of expectations          which    are now   mostly     in     the
        low/mid   £80ms        compared with last       year’s  £74.5m.
        Such   estimates       fit in  with   a picture  of     steady, but unspectacular,           growth.    In     the
        cornerstone      UK Confectionery     Division,         volumes    are     running below      earlier        hopes
        but  pricing     has   been    OK and continued           ‘‘real’’ profit            improvement is anticipated.
        Grocery   Products         should also  be  higher.     The   same    goes     for Rileys   where  new       snack
        Capacity  is being        brought   on  stream                 and where margins should be starting to     reflect
        lower  raw   material costs.

        In  the  USA     Toms      is  involved in a   hefty    capital    expenditure     programme            which will
        mean    a     higher   depreciation     charge   and    moderation      in     progress.  An initial     contri-
        bution    from     Original    Cookie      could add    £2%-3m     to     the   trading   profit   line    which
        could   end  up     being     converted at     a rate   similar    to last     year’s average     $1.34 =    £1.
   4,   At  Laura    Secord       and   Rowntree Mackintosh            Canada                                     purchase the imposition of 10%
        tax       and higher   prices could    make it difficult to     achieve     much            1985 profit improve-
    ~   ment.

                          in   Europe  is   likely to   have remained     one     of slow        but steady    progress,      Slow But Steady
        Problems     in     Benelux    have   been  tidied     up and     German     management         has been       up-    European Progress
        grad         Marketing     investment     remains       heavy,     however,     and     the  achievement        of
        Proper       returns   on  £100m plus of        Continental     capital     employed     is  still some      years
        off.

        Overseas  the     Rand occupies     centre      stage.    Quite where it will     end the day in         1985 is
        anybody’s    guess     but translation     of the South African profit stream stands to make                   a
        nasty  dent.     The      same applies  (to   a  lesser   extent)  in   Australia where      profits    are   on
        the  up     after  a   major   overhaul    and   under    new     management.     Good              margins were
        locked    in   to  a   UK     Export  Division   business     which     has     a distinct  first  half bias  so
        stronger sterling shouldn‘t have     too        much    current    year     impact.

        After  a  rather     higher    interest charge   our      present  arithmetic adds     to    a         £80m 1985      £80m Target
        Rowntree     Mackintosh        forecast.    The first     half  currency     calculation                      be      For should     still     ‘85
        mildly      positive   which   points   to an    outcome     of    around     £25m compared with            last
        year’s £22.4m.            Mind you, a slightly                                                                us more cautious presentation wouldn‘t surprise
        on  19th  September.

        ROWNTREE MACKINTOSH 1983 SALES AND PROFIT BREAKDOWN WITH OUR ‘84 AND ‘85 PROJECTIONS

        Year Ending 31st  December         1984                                 1984                   1985
Estimated                                                           Estimated        Estimated
  Sales                                                                     Pbit                     Pbit
   £m                                                                      £m                        £m

                     UK
                     Confectionery                       390               33.0                        35.0
                     Groceries                            32                     2.4                    3.0
                     Snacks                               37                     3.5                    4.0
                                                         459                    38.9                   42.0

                         North America
                     USA                                 190                    24.0                    275
                     Canada                              119                     8.5                    8.5
                                                         309                    31.5                   36.0


    2nd September,       1985                                                                                                  Vol.9 1: 18
                                                                                                                                   |
J| ROWNTREE MACKINTOSH & Rowntree Mackintosh switched to average exchange rate profit translation in its last Interim due financial year so earnings shouldn't be nearly as badly upset by forex changes as "first thing those of rival Cadbury Schweppes. Even so, dollar recently,a 19th weakness and, more September collapsed Rand have taken the edge of expectations which are now mostly in the low/mid £80ms compared with last year's £74.5m. Such estimates fit in with a picture of steady, but unspectacular, growth. In the cornerstone UK Confectionery Division, volumes are running below earlier hopes but pricing has been OK and continued ''real'' profit improvement is anticipated. Grocery Products should also be higher. The same goes for Rileys where new snack Capacity is being brought on stream and where margins should be starting to reflect lower raw material costs. In the USA Toms is involved in a hefty capital expenditure programme which will mean a higher depreciation charge and moderation in progress. An initial contri- bution from Original Cookie could add £2%-3m to the trading profit line which could end up being converted at a rate similar to last year's average$1.34= £1. 4, At Laura Secord and Rowntree Mackintosh Canada purchase the imposition of 10% tax and higher prices could make it difficult to achieve much1985 profit improve- ~ ment. in Europe is likely to have remained one of slow but steady progress, Slow But Steady Problems in Benelux have been tidied up and German management has been up- European Progress grad Marketing investment remains heavy, however, and the achievement of Proper returns on £100m plus of Continental capital employed is still some years off. Overseas the Rand occupies centre stage. Quite where it will end the day in 1985 is anybody's guess but translation of the South African profit stream stands to make a nasty dent. The same applies (to a lesser extent) in Australia where profits are on the up after a major overhaul and under new management. Good margins were locked in to a UK Export Division business which has a distinct first half bias so stronger sterling shouldn't have too much current year impact. After a rather higher interest charge our present arithmetic adds to a £80m 1985 £80m Target Rowntree Mackintosh forecast. The first half currency calculation be For should still'85 mildly positive which points to an outcome of around £25m compared with last year's £22.4m. Mind you, a slightly us more cautious presentation wouldn't surprise on 19th September. ROWNTREE MACKINTOSH1983 SALES AND PROFIT BREAKDOWN WITH OUR '84 AND '85PROJECTIONS Year Ending 31st December19841984 1985 Estimated Estimated Estimated Sales Pbit Pbit £m £m £m UK Confectionery39033.0 35.0 Groceries322.4 3.0 Snacks373.5 4.0 459 38.9 42.0 North America USA 190 24.0 275 Canada1198.5 8.5 309 31.5 36.0 2nd September,1985 Vol.9 1: 18 |
Read by machine, contrast corrected highest quality of the three
   /|   ROWNTREE         MACKINTOSH
 &      Rowntree     Mackintosh        switched    to   average    exchange      rate    profit translation  in  its  last      Interim due
        financial  year     so    earnings   shouldn‘t   be     nearly  as badly     upset  by forex      changes          as   “first thing
        those  of rival     Cadbury    Schweppes.           Even   so, dollar                                      recently,a   19th weakness and, more September
        collapsed    Rand      have    taken  the  edge  of      expectations which     are now       mostly     in     the
        low/mid   £80ms        compared with last       year’s   £74.5m.
        Such   estimates       fit in  with   a picture  of      steady, but unspectacular,           growth.    In     the
        cornerstone      UK Confectionery     Division,          volumes   are     running  below      earlier        hopes
        but  pricing     has   been    OK and continued            ‘‘real’’ profit            improvement is anticipated.
        Grocery   Products         should also  be   higher.     The   same    goes     for Rileys   where  new       snack
        Capacity  is being        brought   on  stream                  and where margins should be starting to     reflect
        lower  raw   material      costs,

        In  the  USA     Toms      is  involved in a   hefty    capital     expenditure     programme            which will
        mean    a     higher   depreciation     charge   and    moderation       in     progress.  An initial     contri-
        bution    from     Original    Cookie      could add     £2%-3m     to     the   trading   profit   line    which
        could   end  up     being      converted at    a rate    similar    to last     year’s average     $1.34 =    £1.
   4,   At  Laura    Secord       and    Rowntree Mackintosh            Canada                                     purchase the imposition of 10%
        tax       and higher   prices could    make it difficult to     achieve     much             1985 profit improve-
    ~   ment.

                          in   Europe  is   likely to   have remained     one      of slow        but steady    progress.      Slow But Steady
        Problems     in     Benelux    have   been   tidied     up and     German     management         has been       up-    European Progress
        grad         Marketing         investment  remains       heavy,     however,     and     the  achievement        of
        Proper       returns   on  £100m plus of        Continental     capital     employed      is  still some      years
        off.

        Overseas  the     Rand occupies     centre      stage.     Quite where it will     end the day in         1985 is
        anybody’s    guess     but translation     of the South African profit stream stands to make                    a
        nasty  dent.     The      same applies   (to  a   lesser   extent)  in   Australia where      profits    are   on
        the  up     after  a   major   overhaul    and   under     new     management.     Good       margins        were
        locked    in   to  a   UK     Export  Division   business     which      has     a distinct  first  half bias  so
        stronger sterling shouldn‘t have     too        much     current    year     impact.

        After  a  rather     higher    interest  charge      our   present  arithmetic adds     to    a         £80m 1985      £80m Target
        Rowntree     Mackintosh        forecast.     The first     half  currency     calculation                      be      For should     still     ‘85
        mildly      positive   which   points   to an    outcome     of     around     £25m compared with            last
        year’s £22.4m.            Mind you, a slightly                                                                 us more cautious presentation wouldn‘t surprise
        on  19th  September.

        ROWNTREE MACKINTOSH 1983 SALES AND PROFIT BREAKDOWN WITH OUR ‘84 AND ‘85 PROJECTIONS

        Year Ending 31st  December         1984                                  1984                   1985
Estimated                                                           Estimated        Estimated
  Sales                                                                      Pbit                     Pbit
   £m                                                                       £m                        £m

                     UK
                     Confectionery                       390                33.0                        35.0
                     Groceries                            32                      2.4                    3.0
                     Snacks                               37                      3.5                    4.0
                                                         459                     38.9                   42.0

                         North America
                     USA                                 190                     24.0                    275
                     Canada                              119                      8.5                    8.5
                                                         309                     31.5                   36.0


    2nd September,       1985                                                                                                   Vol.9 1: 18
                                                                                                                                    |
/| ROWNTREE MACKINTOSH & Rowntree Mackintosh switched to average exchange rate profit translation in its last Interim due financial year so earnings shouldn't be nearly as badly upset by forex changes as "first thing those of rival Cadbury Schweppes. Even so, dollar recently,a 19th weakness and, more September collapsed Rand have taken the edge of expectations which are now mostly in the low/mid £80ms compared with last year's £74.5m. Such estimates fit in with a picture of steady, but unspectacular, growth. In the cornerstone UK Confectionery Division, volumes are running below earlier hopes but pricing has been OK and continued ''real'' profit improvement is anticipated. Grocery Products should also be higher. The same goes for Rileys where new snack Capacity is being brought on stream and where margins should be starting to reflect lower raw material costs, In the USA Toms is involved in a hefty capital expenditure programme which will mean a higher depreciation charge and moderation in progress. An initial contri- bution from Original Cookie could add £2%-3m to the trading profit line which could end up being converted at a rate similar to last year's average$1.34= £1. 4, At Laura Secord and Rowntree Mackintosh Canada purchase the imposition of 10% tax and higher prices could make it difficult to achieve much1985 profit improve- ~ ment. in Europe is likely to have remained one of slow but steady progress. Slow But Steady Problems in Benelux have been tidied up and German management has been up- European Progress grad Marketing investment remains heavy, however, and the achievement of Proper returns on £100m plus of Continental capital employed is still some years off. Overseas the Rand occupies centre stage. Quite where it will end the day in 1985 is anybody's guess but translation of the South African profit stream stands to make a nasty dent. The same applies (to a lesser extent) in Australia where profits are on the up after a major overhaul and under new management. Good margins were locked in to a UK Export Division business which has a distinct first half bias so stronger sterling shouldn't have too much current year impact. After a rather higher interest charge our present arithmetic adds to a £80m 1985 £80m Target Rowntree Mackintosh forecast. The first half currency calculation be For should still'85 mildly positive which points to an outcome of around £25m compared with last year's £22.4m. Mind you, a slightly us more cautious presentation wouldn't surprise on 19th September. ROWNTREE MACKINTOSH1983 SALES AND PROFIT BREAKDOWN WITH OUR '84 AND '85PROJECTIONS Year Ending 31st December19841984 1985 Estimated Estimated Estimated Sales Pbit Pbit £m £m £m UK Confectionery39033.0 35.0 Groceries322.4 3.0 Snacks373.5 4.0 459 38.9 42.0 North America USA 190 24.0 275 Canada1198.5 8.5 309 31.5 36.0 2nd September,1985 Vol.9 1: 18 |